Categories
Commentary

The Mar-a-Lago Accords

“Good investing doesn’t come from buying good things, but from buying things well.” – Howard Marks

There is a lot of noise—it’s exhausting. Today, we will sift through the noise and focus on how we can protect and potentially grow our portfolios this year. This is a follow-up to our Market Tremors letter. But first, let’s clarify the context for our approach. This is a long newsletter, so you may have to view it in another window.


Inflation is back in focus, gold is soaring, and investors are optimistic about stocks. Correlations remain low, dispersion is high, and the market’s volatility pricing/positioning obscures potential risks lurking beneath the surface. The macro landscape is shifting rapidly, yet when we zoom out, we’re confronted with something we’ve discussed before: inflation is here to stay!

For a long time, the expectation was that inflation would take a particular shape—a transitory spike and a manageable trend. Instead, structurally, we’re dealing with a world that is moving away from the low-inflation paradigms of the past. The pillars supporting cheap capital and abundant liquidity—globalization and dovish monetary policy—are shifting.

These shifts are neither sudden nor unexpected. In 2023, we wrote much about the narrative of the ideological struggle between the West and East, particularly with the Russia-Ukraine conflict sparking. Historically, whenever Eastern economies prosper, the West adjusts the rules. Now, it’s more about who controls what. Control over assets, inflation, and interest rates define economic power. Folks like Zoltan Pozsar have warned that the fundamental drivers of the low-inflation era—globalization and financialization—are unraveling, leaving policymakers with little choice.

The well-respected Kai Volatility’s Cem Karsan, a mentor to many, has pointed out in excruciating, albeit digestible detail that the trends favoring high-beta portfolios over the past four decades are reversing. Monetary authorities, particularly the Federal Reserve, have been constrained in their ability to address the widening wealth divide. Their response to inflation in the early 2020s—from creating demand to absorb surplus supplies of low-priced items to structurally restricting demand in response to shortages—was intended to guide the economy along a path of managed declines in activity while maneuvering interest rates to prevent another inflationary flare. Rising populism is a byproduct manifesting as shifts in public demand and political sentiment.

Thus, today’s Mar-a-Lago Accords and the broader economic overhaul signify a significant trade, monetary policy, and financial stability restructuring. Tariffs, a U.S. sovereign wealth fund, and global security restructuring are the key issues at this forefront. The implications of this shift are profound, and markets have yet to adjust. A portfolio for this new environment could creatively layer exposure to stocks, bonds, commodities, and volatility. Understanding the pieces herein will be critical for structuring trades and managing risk. Let’s dive in.


Macro Context: A New Economic Framework

#1 – Tariffs

One significant component of this broader economic overhaul is tariffs. Economist Stephen Miran, nominated by the U.S. President to be Chairman of the Council of Economic Advisers, has outlined how tariffs, historically used to influence trade flows, are being retooled as protectionist instruments and an alternative revenue source.

According to Miran’s A User’s Guide to Restructuring the Global Trading System and fantastic explanations by Bianco Research founder Jim Bianco, a core issue is a persistently strong dollar distorting global trade balances. If paired with currency adjustments, tariffs could redistribute the costs away from U.S. consumers, “present[ing] minimal inflationary or otherwise adverse side effects, consistent with the [U.S.-China trade war] experience in 2018-2019.” However, this approach risks retaliation or distancing from key trading partners, further fracturing global supply chains.

To mitigate these risks, policymakers consider implementing tariffs in phases, gradually increasing rates to address inflationary pressures and market volatility. Even during the 2018-2019 trade war, tariff rate increases were implemented over time. Additionally, tariffs will be driven by national security concerns, targeting industries essential to defense and technological innovation. From this perspective, policymakers view access to the U.S. market as a privilege.

#2 – Sovereign Wealth Fund

A significant consideration is a U.S. sovereign wealth fund leaning on undervalued national assets to restore fiscal stability. Unlike traditional sovereign wealth funds built on surpluses, this fund would operate by revaluing and monetizing domestic reserves.

Key assets under consideration include undervalued gold reserves and billions in government-possessed bitcoin, which could be integrated into this fund. Bianco says these could total nearly $1 trillion.

This strategy introduces volatility concerns. Those concerned say government exposure and potential speculation on financial assets could lead to instability. Should we invest now for later?

#3 – Global Security Agreements

Beyond trade and monetary policy, a core element of the broader economic overhaul is linking military alliances to economic policy. The longstanding framework in which the U.S. provided security to allies without direct compensation is being rethought. The warnings are explicit; note the President’s Davos remarks and the Vice President’s Munich Security Conference speech.

Under a new paradigm, Bianco summarizes that NATO members may be required to contribute more to defense (say ~5% of GDP), foreign-held U.S. Treasury bonds may be converted into 100-year zero-coupon bonds, reducing short-term debt burdens, and tariff structures may be adjusted based on a country’s alignment with U.S. security interests.

“What Miran said in his paper is: you owe us so much for the last 80 years that what we want to do is a debt swap,” Bianco explains how the U.S. can be paid for being the world’s protector. “Those NATO countries have trillions of dollars of debt. [You’ll] swap it for 100-year or perpetual zero coupon non-marketable Treasury securit[ies]. So, you’re going to swap $10 billion worth of Treasuries for a $10 billion coupon century bond [that] won’t mature for 100 years, [and] won’t get any interest.”

In short, this is a fundamental shift that requires allies to bear a more significant share of security and costs. It’s the Mar-a-Lago Accords, a new financial order and policy framework akin to past agreements that reshaped the global economy, such as the Bretton Woods Agreement of 1944, which established the U.S. dollar as the international reserve currency, and the Plaza Accord of 1985, which coordinated currency adjustments to correct trade imbalances.

The proposed Mar-a-Lago Accords aim to reprice U.S. debt through asset monetization, weaken the dollar to improve U.S. export competitiveness and enforce tariff structures to rebalance global trade.


Positioning Context: Market Positioning Obscures

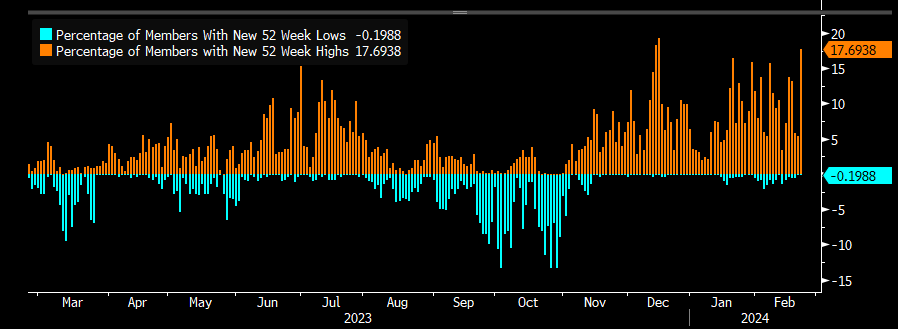
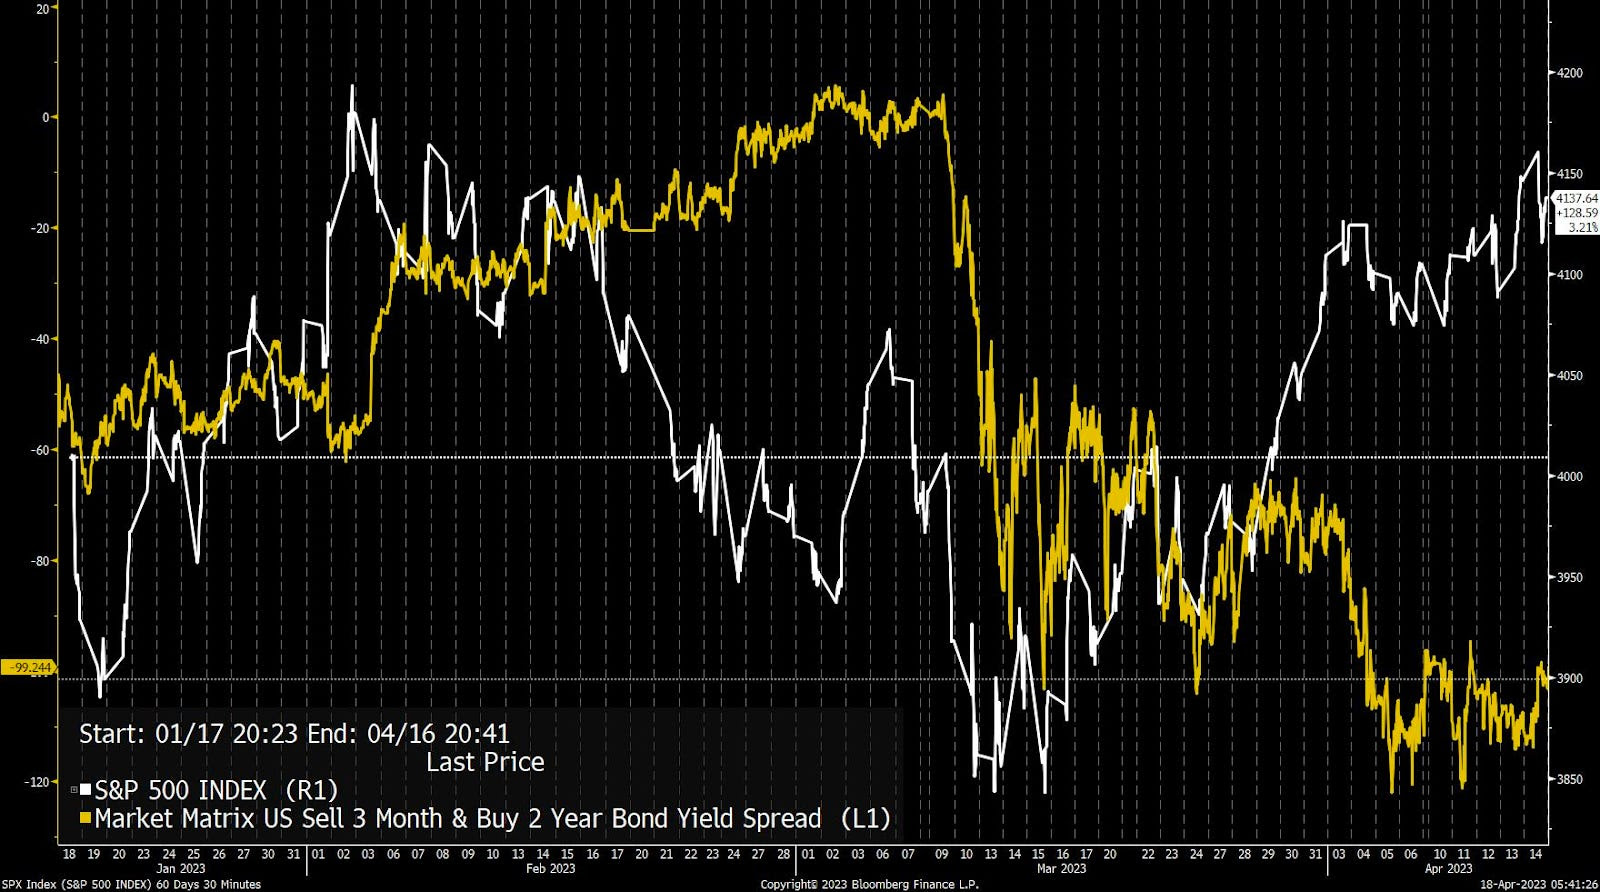
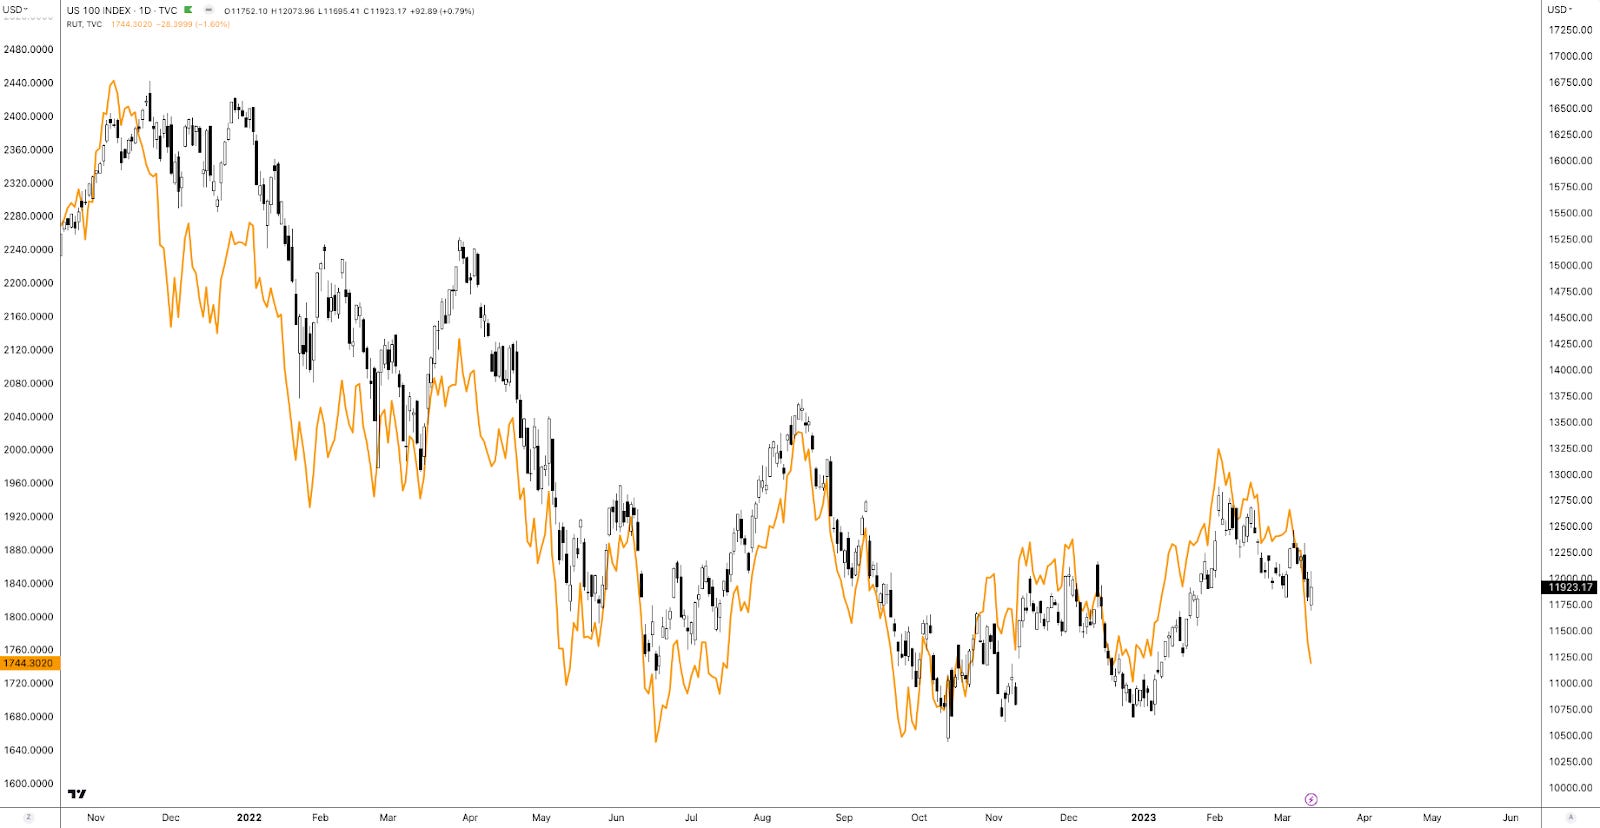
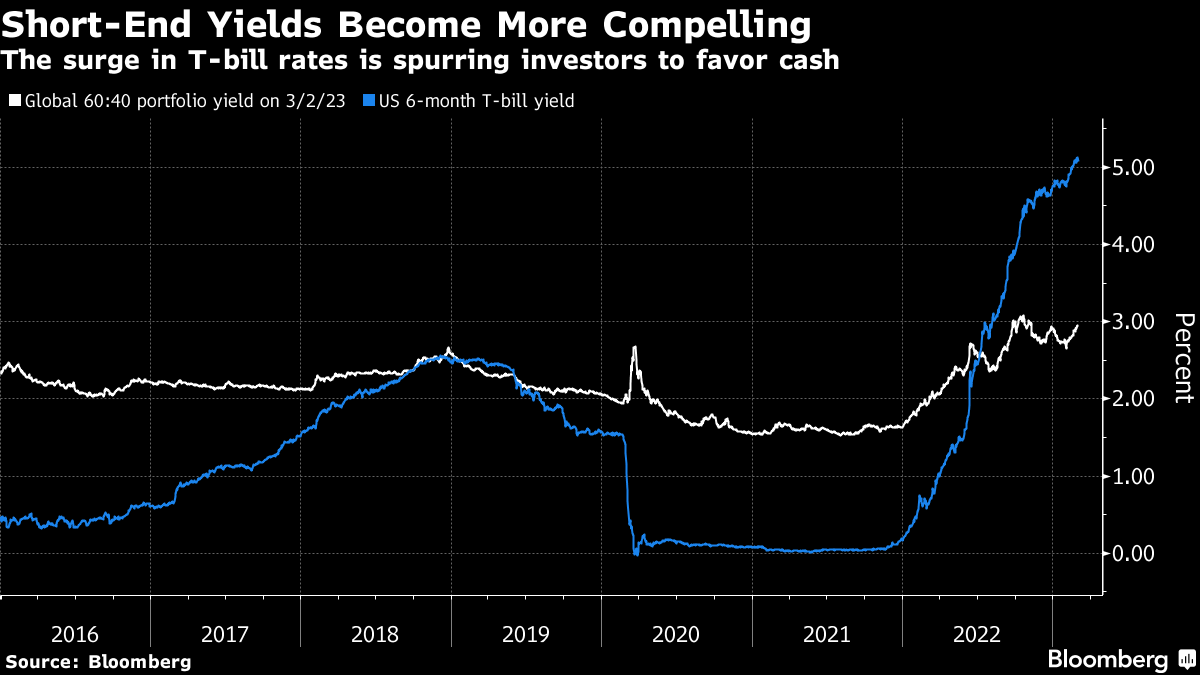
Tariff-driven price pressures, a weaker dollar, and a floor under interest rates raise bond yields, corporate borrowing costs, and strain leveraged players. This backdrop favors debasement plays and perceived safe havens like bitcoin and gold, which have been climbing for reasons discussed in the past and present.

Graphic: Retrieved from Bloomberg via @convertbond.

Equities face a less promising outlook. Oaktree Capital highlights that decade-long returns have historically been lackluster when investors bought the S&P 500 at today’s multiples. As Howard Marks puts it, earning +/-2% annually isn’t disastrous—but the real risk lies in a sharp valuation reset, compressed into just a few years, much like the brutal selloffs of the 1970s and 2000s.
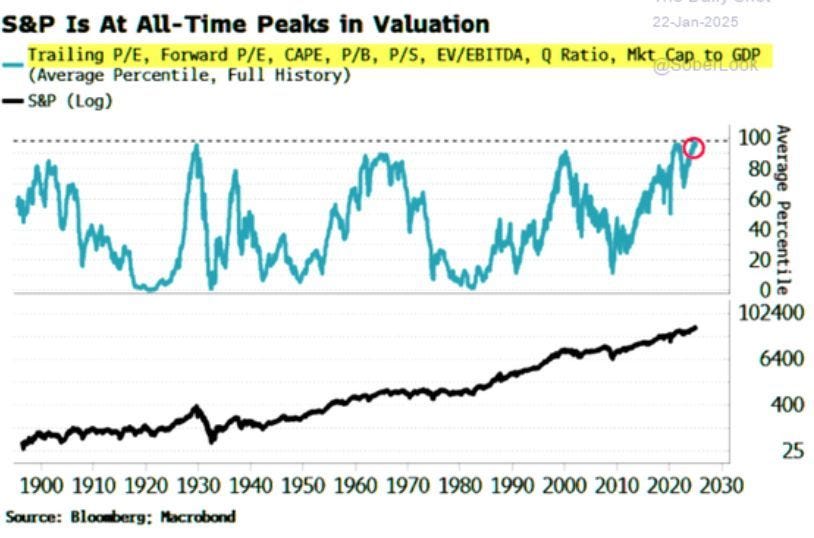
Graphic: Retrieved from Bloomberg via Bob Elliott.

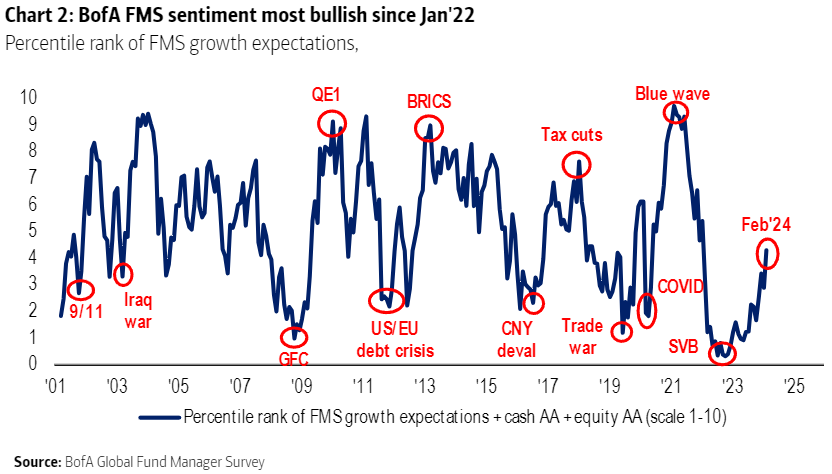
While the current market environment may feel frothy, with stretched valuations and narrow leadership, we’re not in an imbalanced 1970s scenario. Also, the possibility of a dollar devaluation serves as a tailwind for S&P 500 earnings, potentially boosting stock prices, Fallacy Alarm explains. Markets are not irrational; instead, they could face modest returns of around 5-6% annually for stocks and bonds over the next decade. Such sanguine sentiment is evident in the options/volatility market, reflecting the distribution of future possible outcomes; the trading and hedging of options make them a robust gauge of future outcomes—offering a view of where markets stand and where they might be headed.
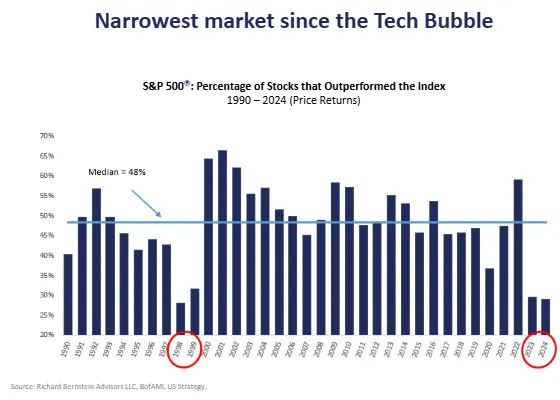
Graphic: Retrieved from Bank of America via Bloomberg.

We observe several key happenings:

#1 – Hedging Volatility Spikes, Not Market Crashes

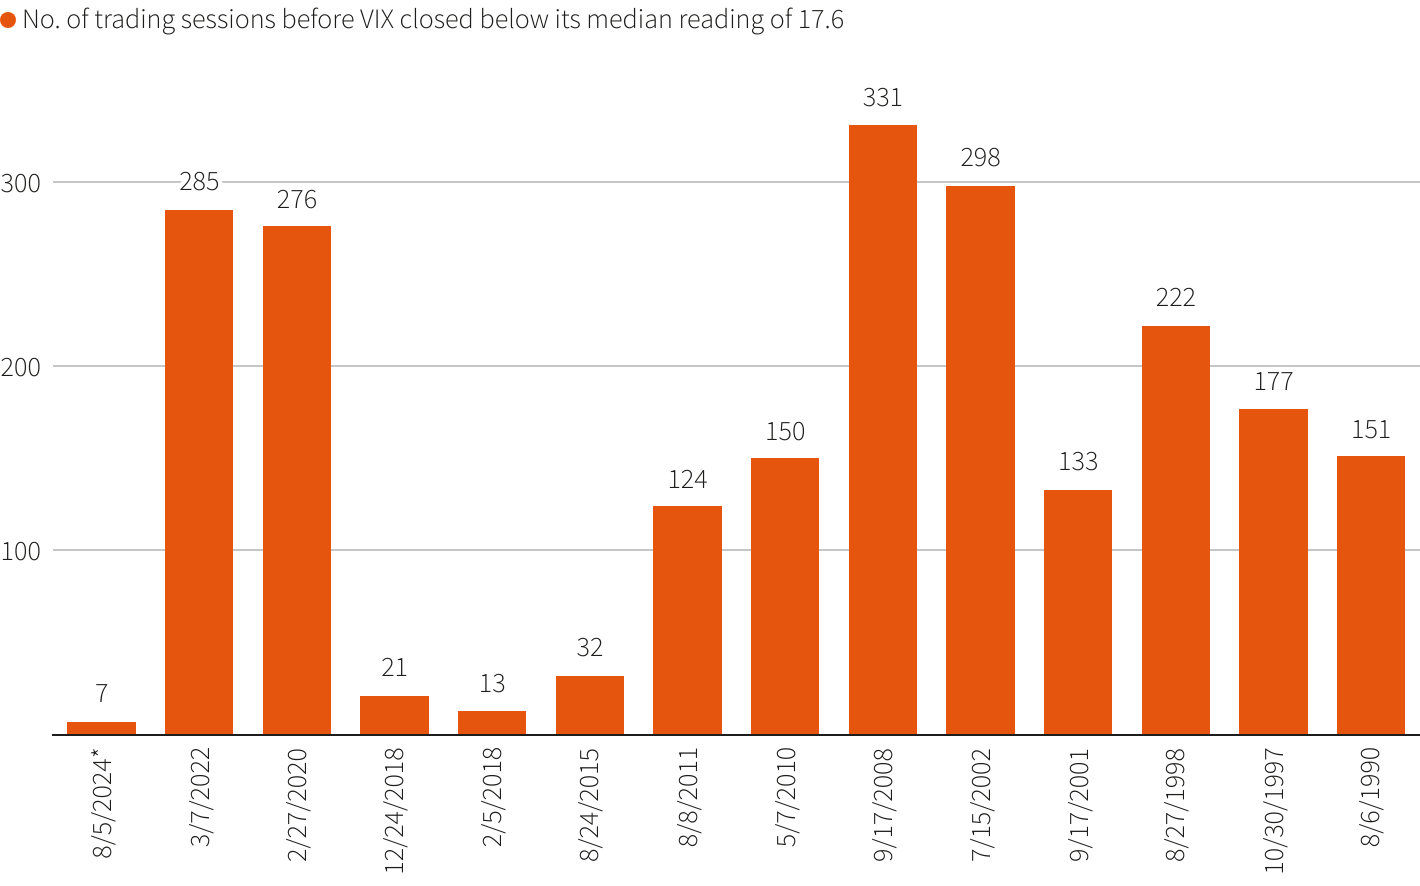
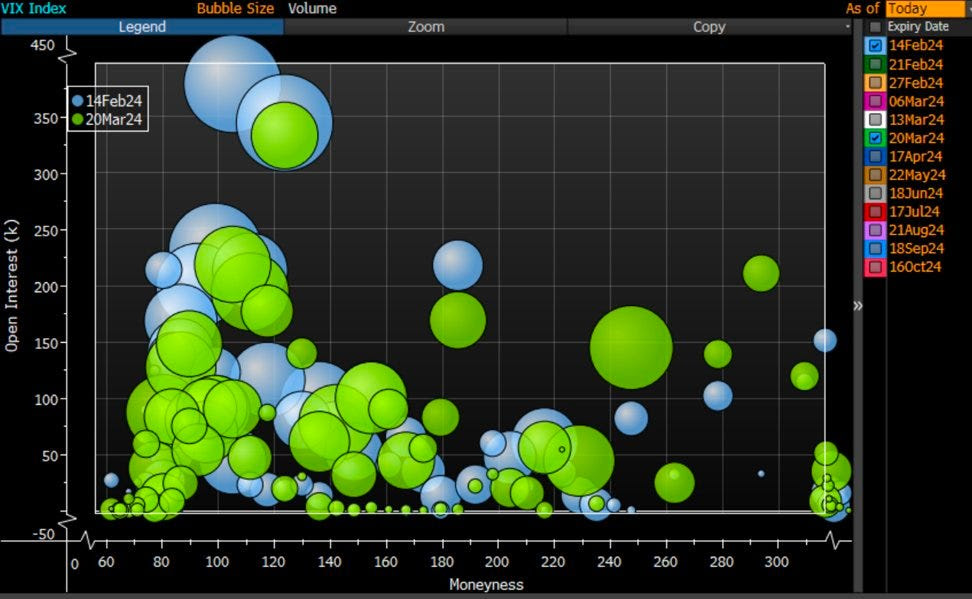
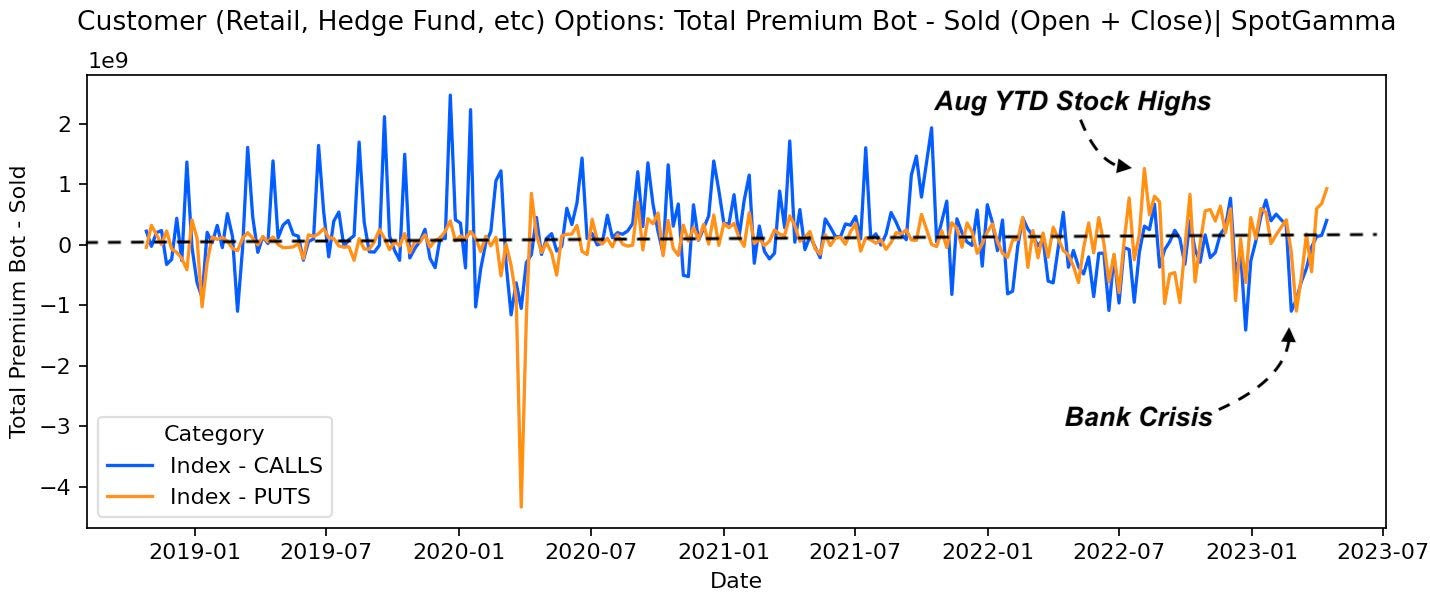
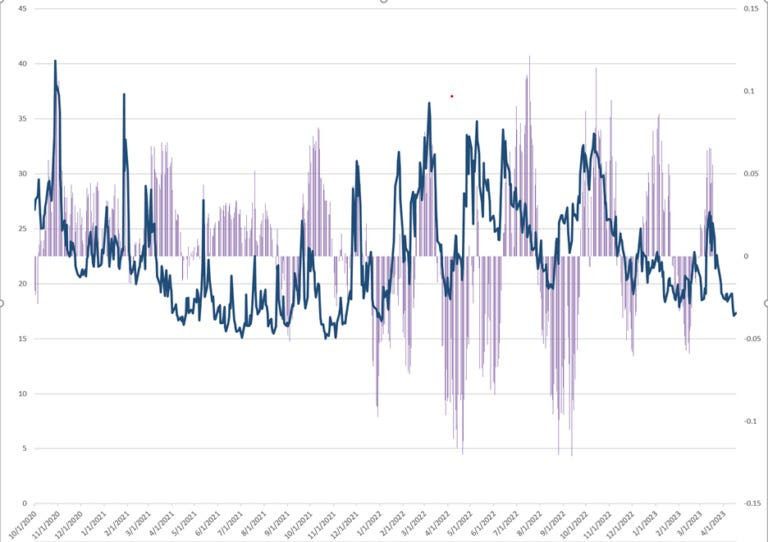
Investors are hedging against potential volatility spikes like those seen on August 5, 2024, when the VIX exploded higher. While the S&P 500 grinds upward and the VIX drifts lower and appears cheap (<16), the VVIX—“VIX of the VIX”—remains elevated. This unusual divergence manifests from demand for VIX calls, suggesting the market worries sharp repricings of risk are more likely than broad equity selloffs. The dynamic boils down to supply and demand; SPX options remain underappreciated—why protect when the market seems stable—meanwhile, VIX options are in demand, bolstering VVIX.

SpotGamma highlights this massive VIX call buying, noting dealer short convexity positioning suggests that, should volatility “wake up,” there could be significant downside pressure on equities and upside pressure on volatility, reinforcing the view that the VVIX’s elevated levels could signal a potential volatility spike, rather than a broad market crash.
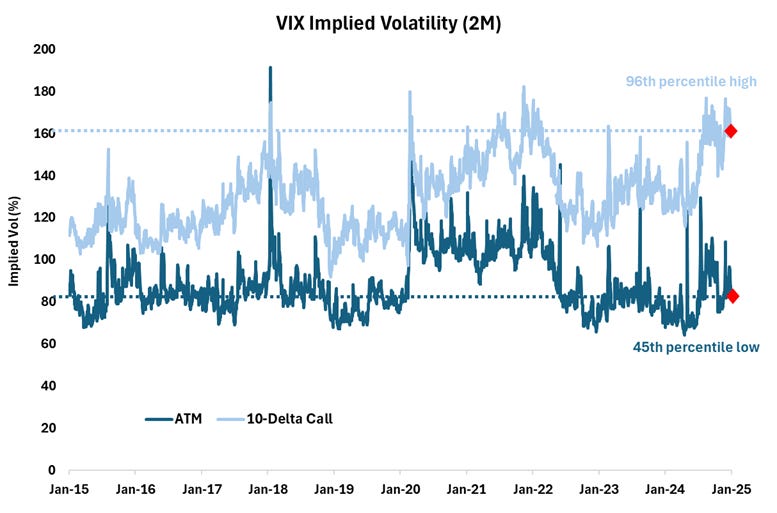
Graphic: Retrieved from Cboe Global Markets.

“The aforementioned vega supply is indeed large, but it is innocuous unless provoked,” SpotGamma’s founder Brent Kochuba explains. Still, “with correlation stretched and IVs at lows, there is the potential for an SPX index short vol cover/single stock spasm to push into this upside vega convexity – something that we think a sharp NVDA [earnings] miss could spark.”
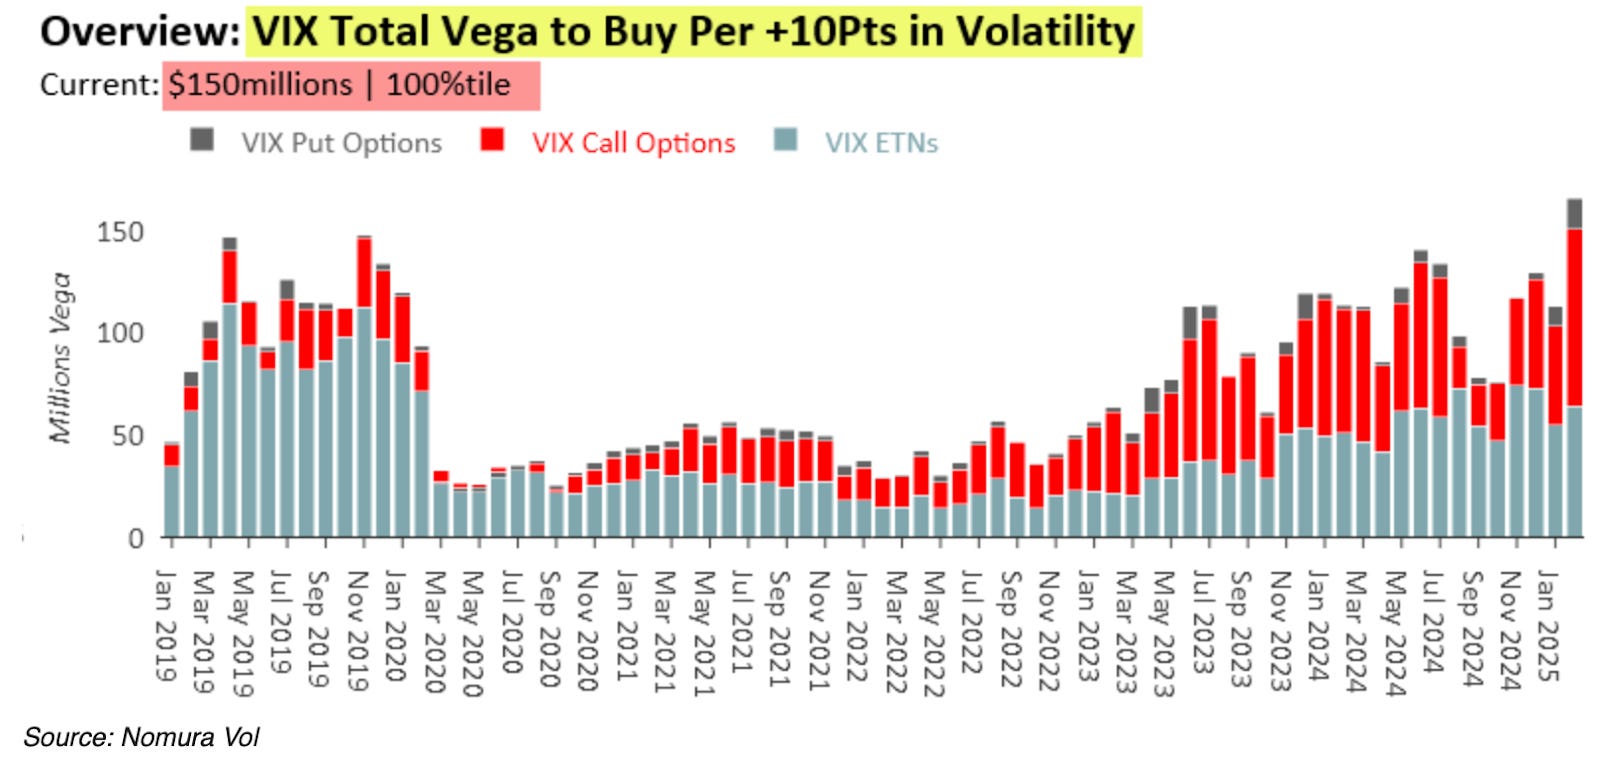
Graphic: Retrieved from Nomura via SpotGamma.

#2 – Options Selling and the ‘Buy My Course’ Gurus

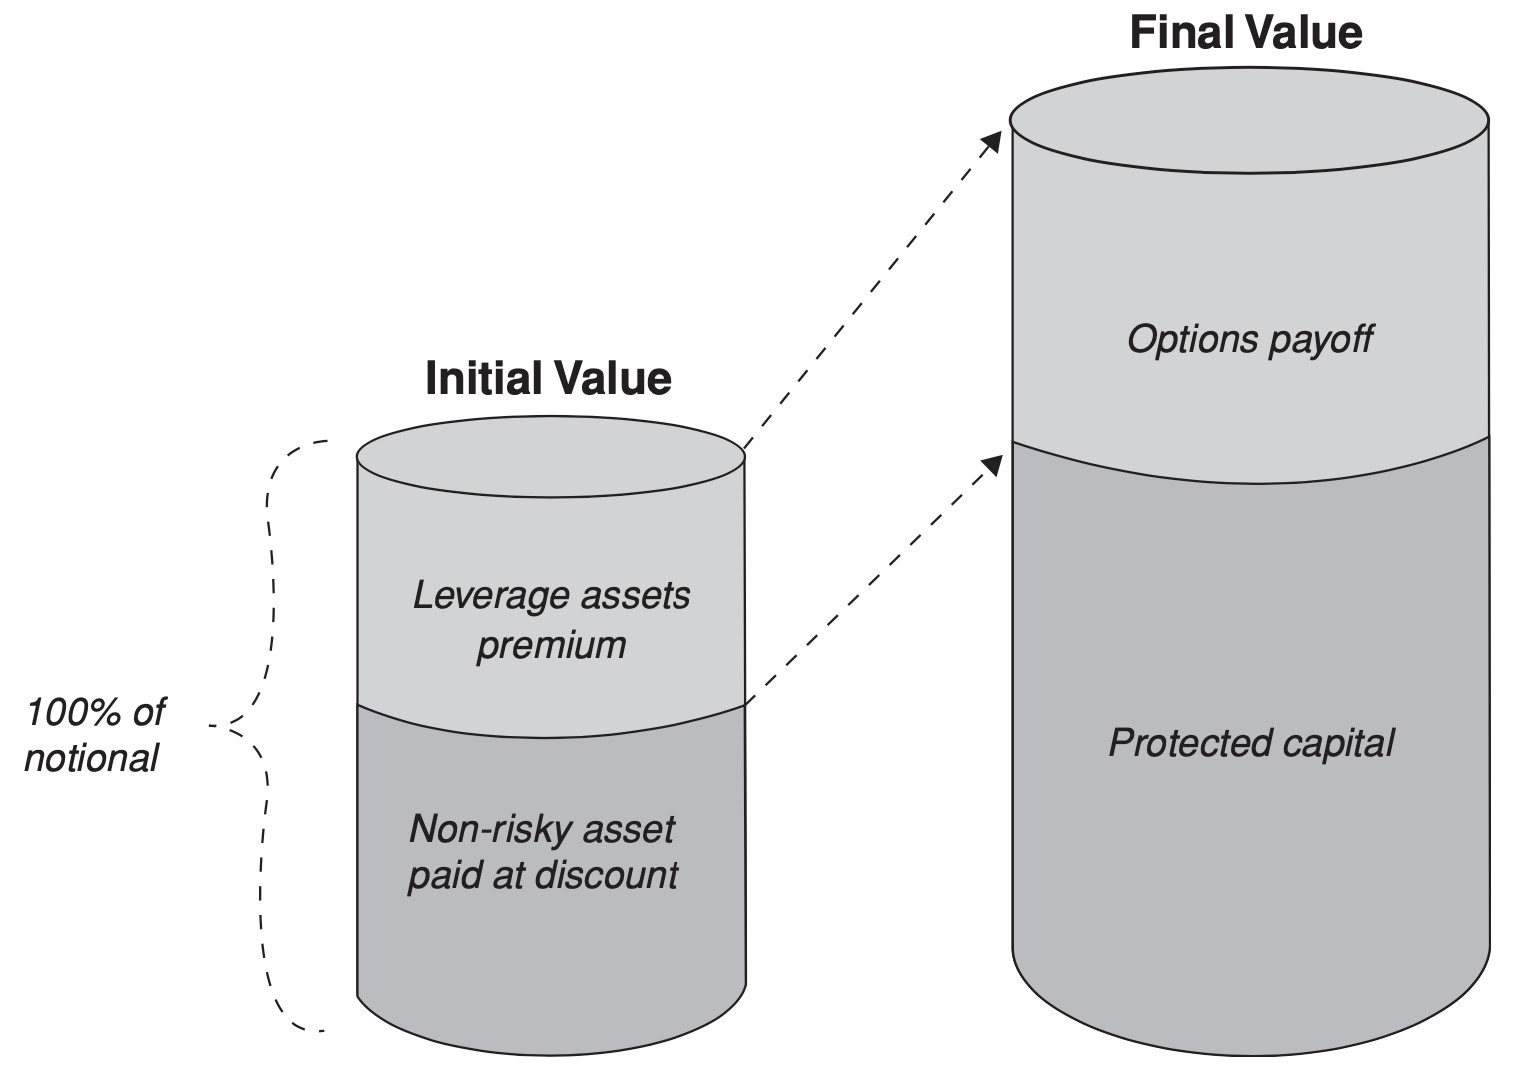
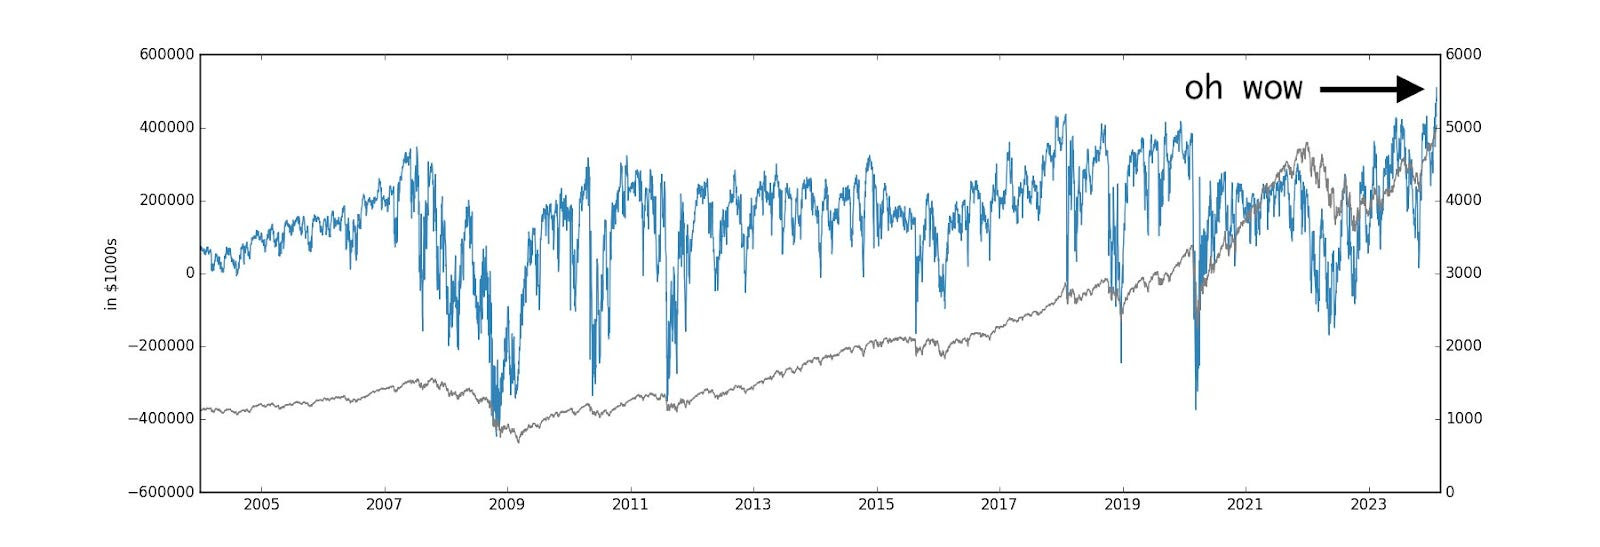
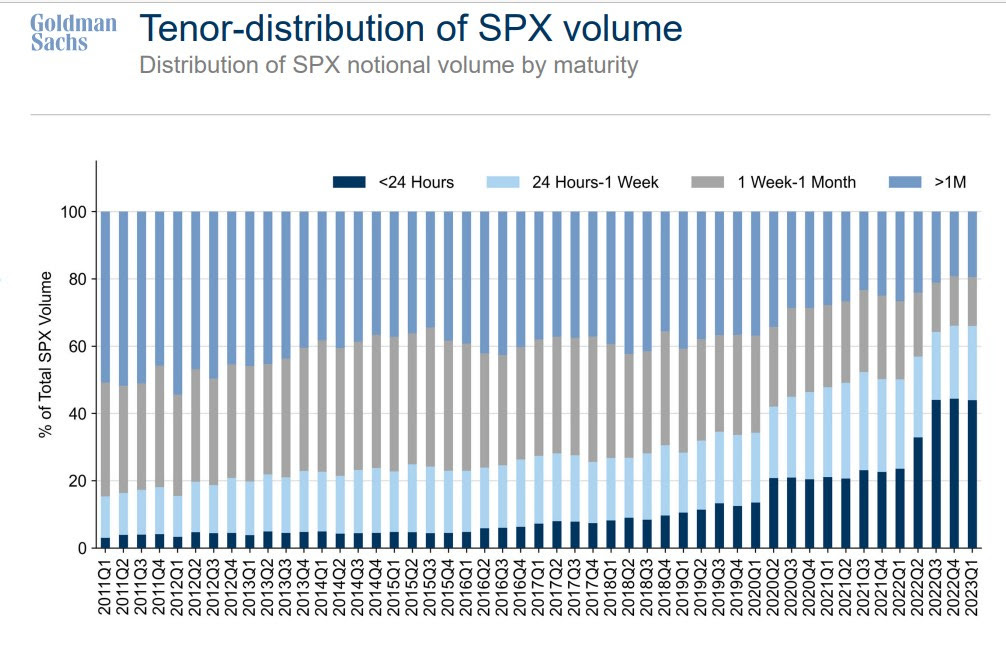
Investors are leaning toward short-dated options selling (sometimes packaged within an ETF structure, without regard for price and thoroughly assessing broader market positioning) and structured products.
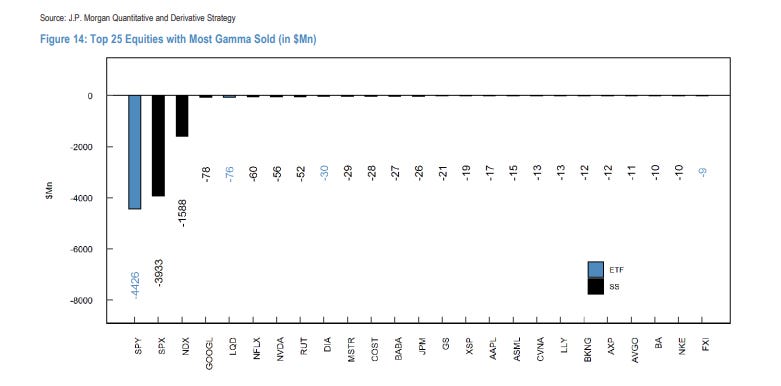
Graphic: Retrieved from JPMorgan via @jaredhstocks.

As QVR Advisors’ Benn Eifert explains, dynamic creates opportunity: deep out-of-the-money, long-dated volatility in single stocks looks attractive for tail-risk hedging. But there’s a catch—the persistence of this activity reinforces spot-vol covariance (i.e., the relationship between the underlying movements or spot and its volatility or vol). If the market shifts and volatility rises as the underlying asset moves up/down (the usual pattern flips), long volatility positions could become highly profitable, as it is then they would benefit from this reversal in spot-vol dynamics (e.g., 2020).
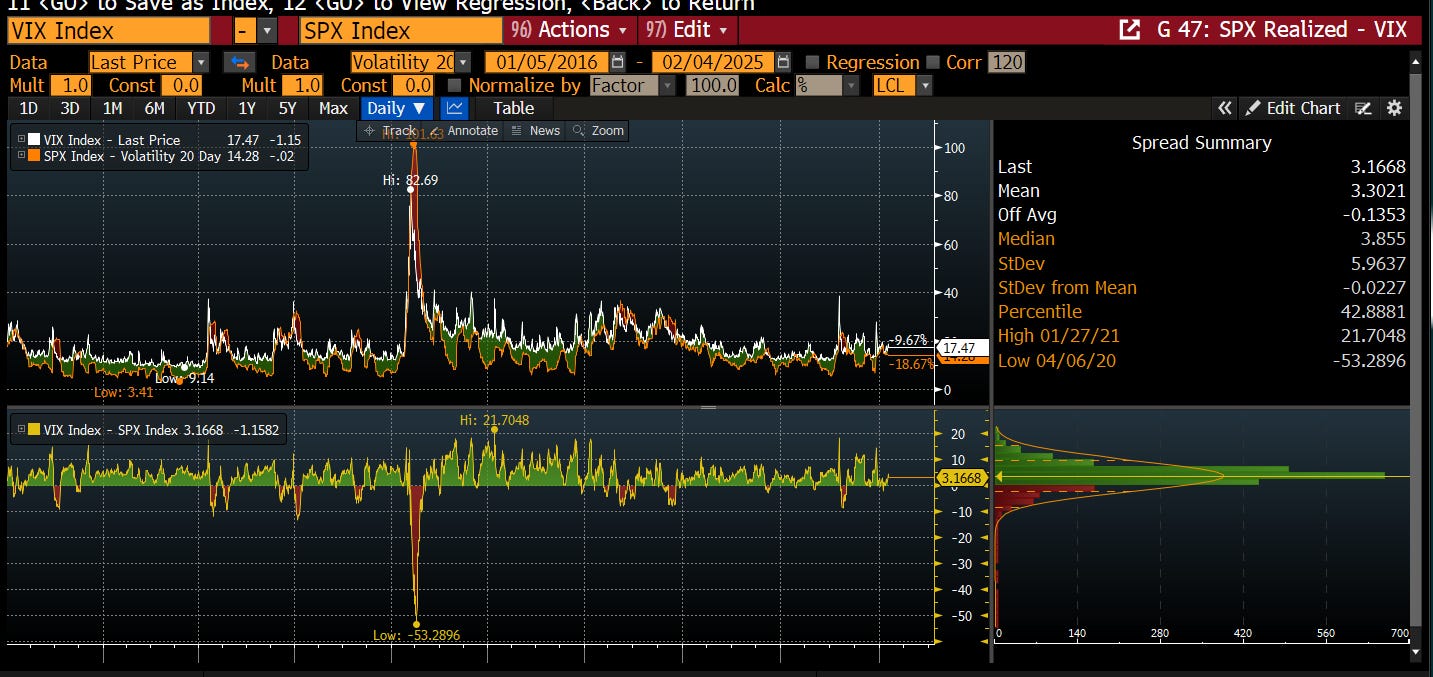
Graphic: Retrieved from Bloomberg via Kris Sidial. Volatility is fair in indexes; “much better opportunities in singles right now.”

As SpotGamma elaborated, if strength through earnings persists, “it will supply a final equity vol and correlation drop (a ‘final vol squeeze’), ushering in a blow-off equity top. At the same time, these metrics are low enough to justify owning 3-6 month downside protection, as bad things usually happen from these vol levels.”

Graphic: Correlation via TradingView. Stocks are expected to move more independently. Peep the pre-2018 Volmageddon levels.

As an aside, implied correlation measures the degree to which the prices of the assets in the basket are expected to move together (positively correlated) or in opposite directions (negatively correlated). Low correlation, in this case, indicates that the stocks are expected to move independently or in opposite directions; hence, dispersion trades betting on this have performed well.
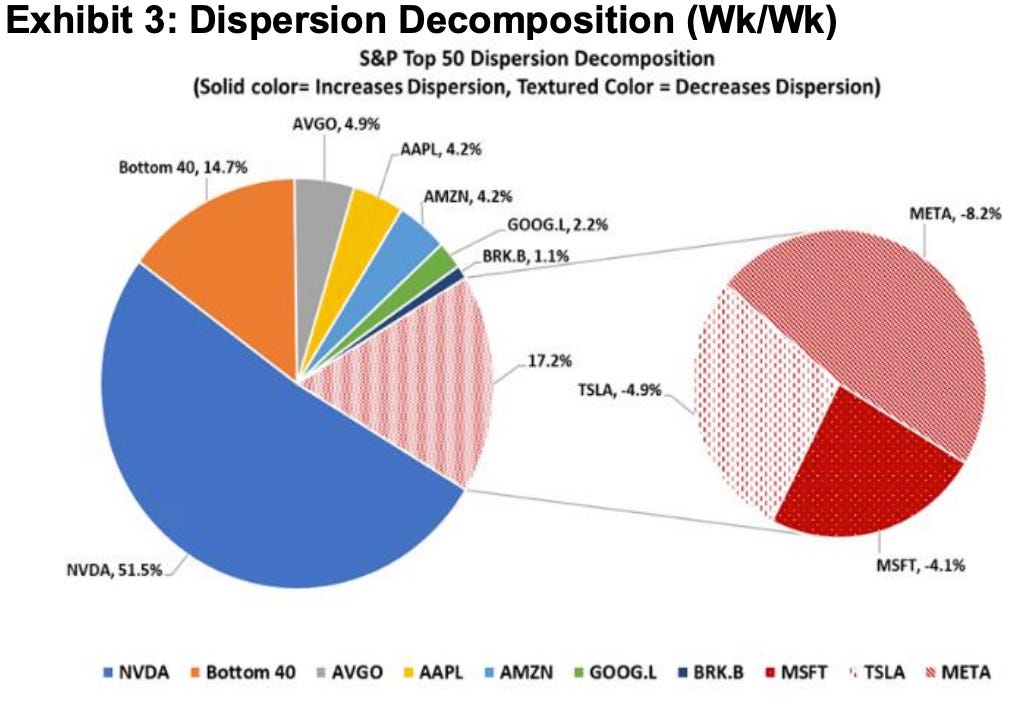
Graphic: Retrieved from Cboe Global Markets.

#4 – The Changing Narrative of Bitcoin and Its Maximalists

Similar patterns emerge in bitcoin. As countries face currency debasement and economic stresses, bitcoin stands out as a hedge to some. Like equities, bitcoin options are underappreciated.

For example, implied volatility has traded under 50% for one-month options, representing an attractive entry point for those looking to position themselves for a surge. This low volatility environment in Bitcoin mirrors the opportunities in equities. Here, bitcoin benefits from any volatility reversal, presenting a compelling case for those looking to participate in a big market move.
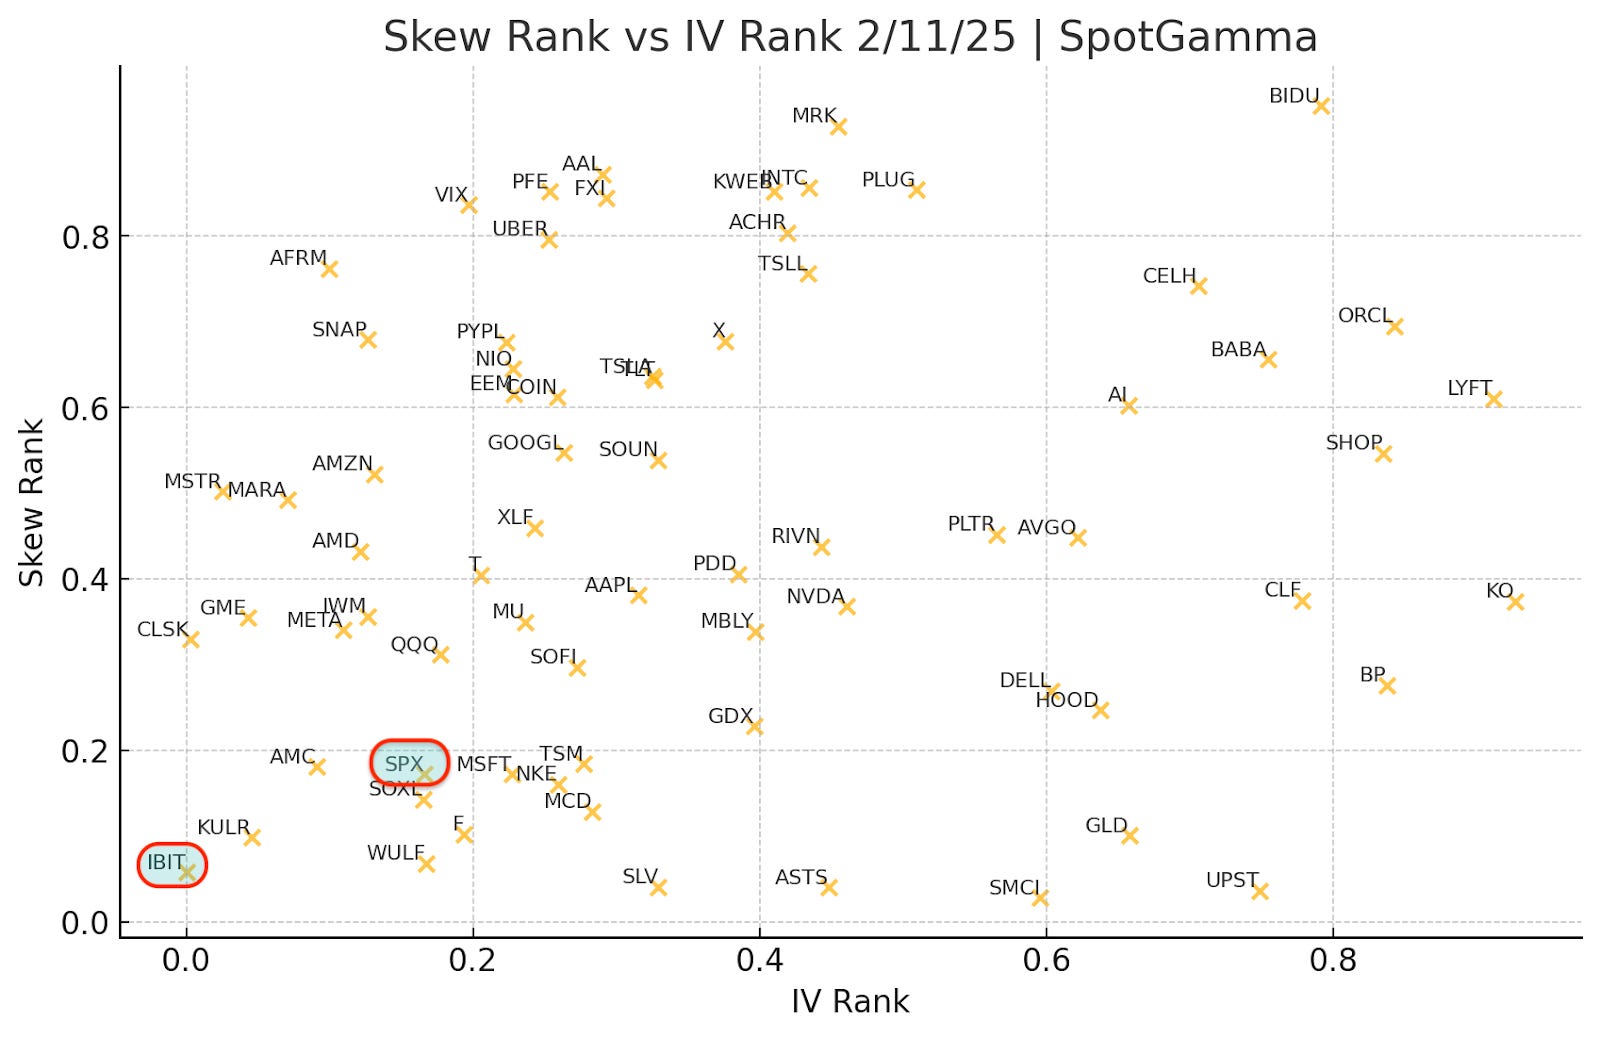
Graphic: Retrieved from SpotGamma. Higher skew and IV rank suggest calls are expensive and moves are stretched.

Context Applied: Trade Structuring

Trade structuring this year is all about creativity. We’ve added the following to our portfolios.

#1 – Rates

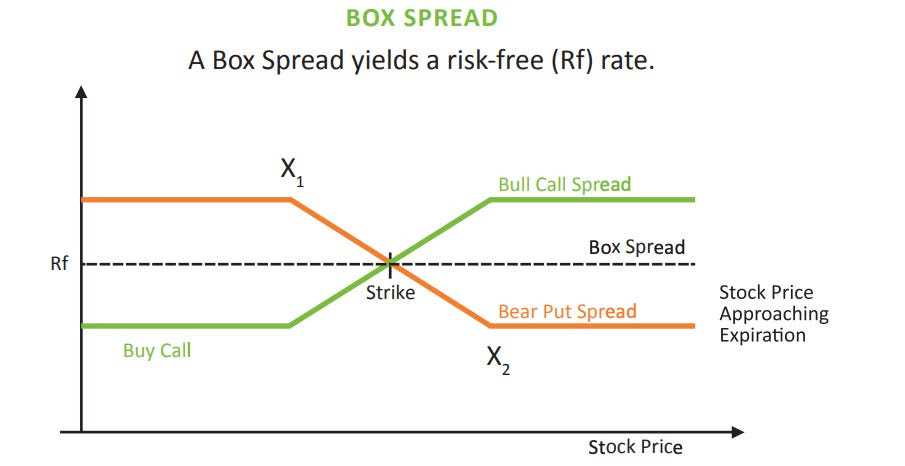
One efficient structure for safeguarding cash is the box spread, which offers several key benefits: a convenience yield, capital efficiency (especially for users of portfolio margin), easy execution via most retail brokers, and favorable tax treatment—60% long-term and 40% short-term if executed using cash-settled index options (e.g., SPX). This strategy combines a bull call spread and a bear put spread, matching lower and higher strikes and the same expiration date.

We frequently trade such structures. For instance, here’s one we purchased at the beginning of this year: BOT +1 IRON CONDOR SPX 100 (Quarterlys) 31 DEC 25 4000/7100/7100/4000 CALL/PUT @2964.25 CBOE

In this case, we invest $296,425 now to receive $310,000 in a year. This represents an implied interest rate of 5.32% or ((3100-2964.25)/2964.25)*(365/314)=0.053234. Note that there is a convenience yield, and that’s due to counterparty risk, as box spreads depend on the Options Clearing Corporation (OCC) to guarantee the transaction.

Tools like boxtrades.com help with tracking yields and finding attractive box structures.
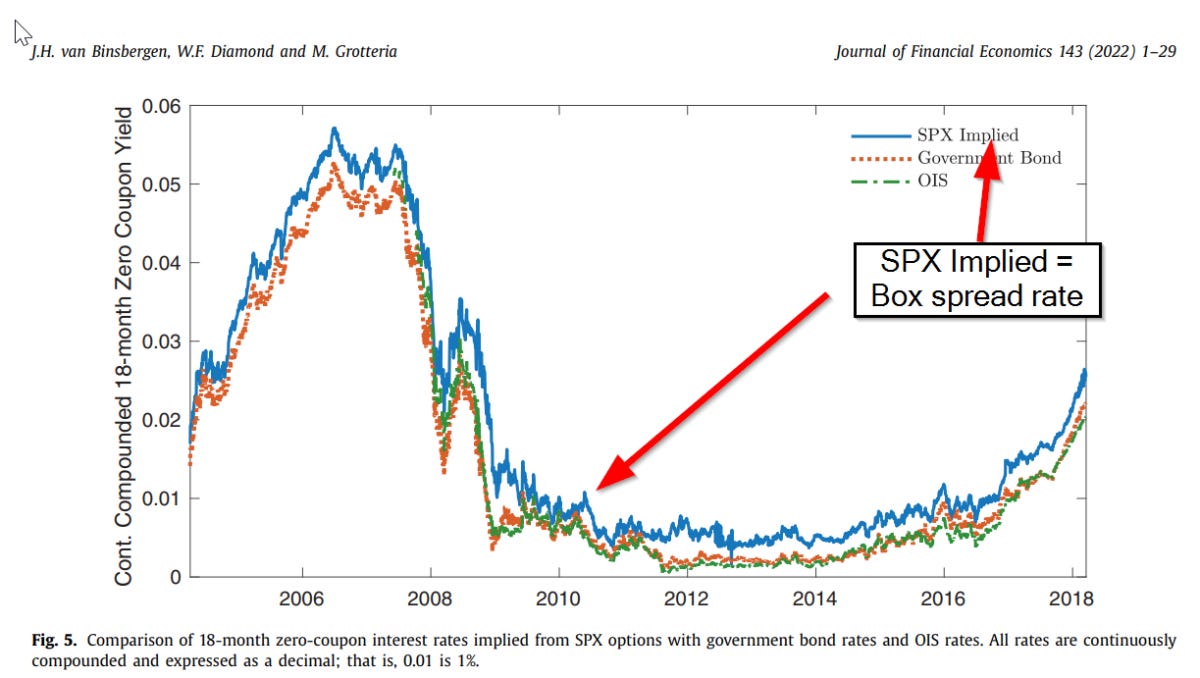
Graphic: Retrieved via Alpha Architect.

Box trades unlock the power of yield stacking, enhancing returns by layering multiple exposures without increasing capital outlay. They preserve full buying power with portfolio margin for margin-intensive trades like synthetic longs.

For non-portfolio margin traders, yield stacking is less applicable. Instead, you can allocate ~95% of cash to box spreads, locking in your principal at maturity while risking only ~5% (the interest you stand to make), with limited downside.
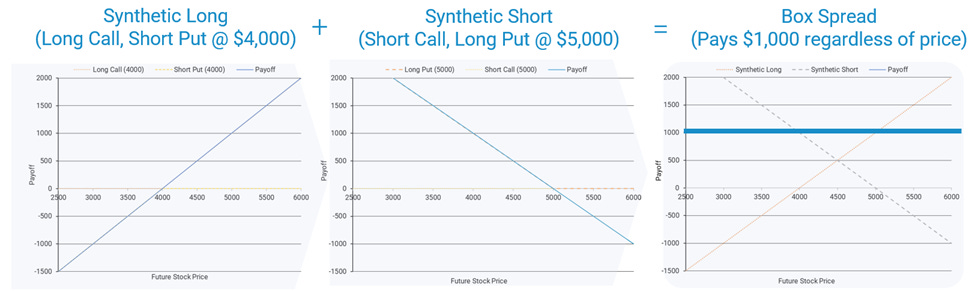
Graphic: Retrieved from Cboe Global Markets.

#2 – Upside

Low correlation and subdued implied volatility signal stability, but any disruption could spark sharp moves.

As we explained better in Reality Is Path-Dependent, Cem Karsan notes that a slow grind higher cheapens options, fueled by continued volatility selling. Eventually, realized upside volatility will surpass implied, prompting smart money to buy options at these discounts. If the VIX holds steady or rises, it suggests fixed-strike volatility is creeping up, potentially forcing options counterparties to cut exposure or hedge, boosting markets higher; increased call demand could push counterparties to hedge by buying the underlying asset, reinforcing stability and giving a floor to options prices and the market by that token.

The play here? Replace stock exposure with options. You can buy calls outright and hedge them by selling stock—gains on the calls should outpace hedge losses. Karsan has talked about this a lot. One of our moves is to structure broken-wing butterflies or similar: buy an option near the money, sell a larger number of options further out, and cap risk with an even farther out option. In this environment, you can often put on these trades for little cost and exit at multiples higher if the market drifts sideways or up. Please see our website for case studies and example trades.

Don’t overlook crypto, either. Implied volatility remains underappreciated in bitcoin, making synthetic exposures compelling. Swapping spot for synthetic alternatives is a play on these opportunities. Though we haven’t touched them, check out Cboe’s cash-settled options on spot bitcoin: the Cboe Bitcoin US ETF Index (CBTX) and Cboe Mini Bitcoin US ETF Index (MBTX).

#3 – Hedging

Though less attractive now, VIX calls and call spreads remain a powerful tool for hedging tail risks. In our Reality Is Path-Dependent letter, we explore this topic further.

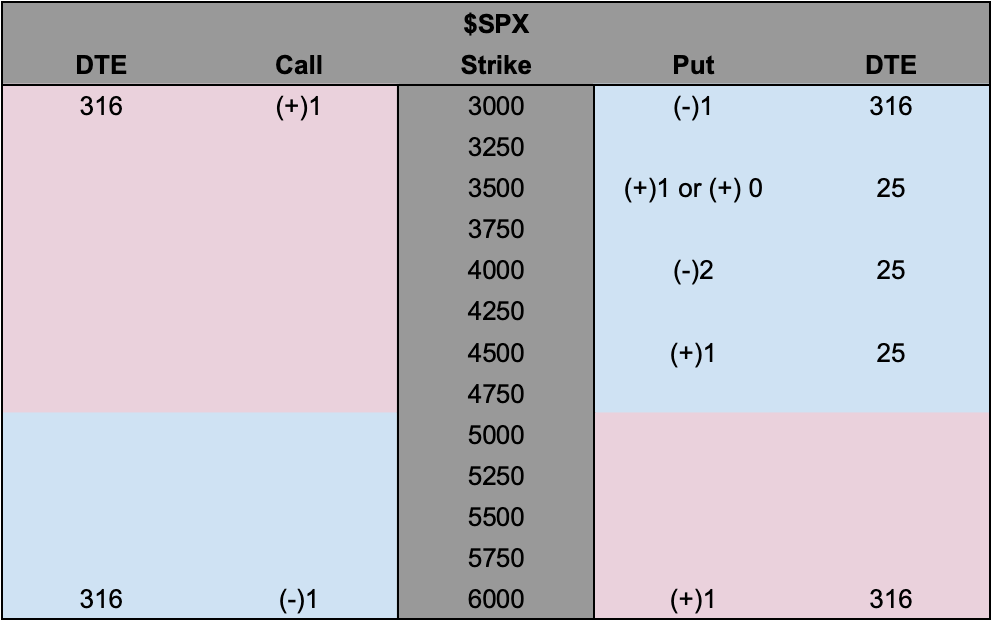
There are more compelling structures within the S&P 500 complex, particularly back spreads. For example, a put back spread involves selling a higher strike put option and buying a larger number of lower strike put options, positioning you to profit from substantial volatility shifts—similar to what we saw on August 5, 2024.

Although this structure takes advantage of the market’s unappealing volatility skew, drift presents challenges; if volatility fails to perform well during a downturn, you risk losing more money than you initially invested in the spread. Caution!
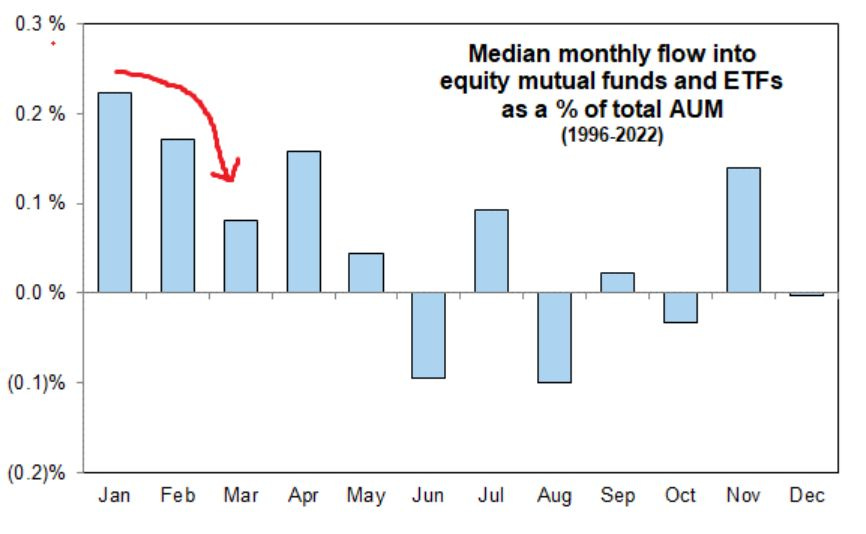
Graphic: Retrieved from Bloomberg via Goldman Sachs.

Bonus: From the White House to Wall Street

We had the opportunity to catch up with Steven Orr, founder of Quasar Markets. We discussed his career and the future of fintech and trading technology. Before Quasar Markets, Orr worked as an executive at Money.net and Benzinga. He also serves on the board of the American Blockchain and Cryptocurrency Association. His diverse background includes positions with the White House, the U.S. State Department, the PGA Tour, the NBA, and various professional sports leagues. Orr frequently shares his insights on TV and appears at events like the World Economic Forum. Check it out, and thank you, Steven!


Disclaimer

By viewing our content, you agree to be bound by the terms and conditions outlined in this disclaimer. Consume our content only if you agree to the terms and conditions below.

Physik Invest is not registered with the US Securities and Exchange Commission or any other securities regulatory authority. Our content is for informational purposes only and should not be considered investment advice or a recommendation to buy or sell any security or other investment. The information provided is not tailored to your financial situation or investment objectives.

We do not guarantee the accuracy, completeness, or timeliness of any information. Please do not rely solely on our content to make investment decisions or undertake any investment strategy. Trading is risky, and investors can lose all or more than their initial investment. Hypothetical performance results have limitations and may not reflect actual trading results. Other factors related to the markets and specific trading programs can adversely affect actual trading results. We recommend seeking independent financial advice from a licensed professional before making investment decisions.

We don’t make any claims, representations, or warranties about the accuracy, completeness, timeliness, or reliability of any information we provide. We are not liable for any loss or damage caused by reliance on any information we provide. We are not liable for direct, indirect, incidental, consequential, or damages from the information provided. We do not have a professional relationship with you and are not your financial advisor. We do not provide personalized investment advice.

Our content is provided without warranties, is the property of our company, and is protected by copyright and other intellectual property laws. You may not be able to reproduce, distribute, or use any content provided through our services without our prior written consent. Please email renato@physikinvest for consent.

We reserve the right to modify these terms and conditions at any time. Following any such modification, your continued consumption of our content means you accept the modified terms. This disclaimer is governed by the laws of the jurisdiction in which our company is located.
Categories
Commentary

The Alchemy of Forecasting

This week’s letter is about 6,000 words and may be cut off. If so, try viewing it in a browser window!

Our recent focus reflexivity manifests in politics through reinforcing shared beliefs and narratives. When political group members share an ideology, their interactions often confirm and amplify their existing views, creating feedback loops. These loops can shape the group’s perception of political realities, such as the strength of their candidate, which in turn influences voter turnout and campaign contributions. This homogeneity also leads to a lack of exposure to opposing views, increasing the risk of misreading voter sentiment and making strategic errors in political campaigns.

This dynamic was evident in the 2016 U.S. presidential election. Many in liberal circles were convinced of Hillary Clinton’s victory, relying on polling data and a widespread belief in her inevitability. This perception reinforced within these groups created a reflexive cycle that contributed to complacency and lower turnout in critical swing states. Those in the Republican bubble who supported Donald Trump also experienced their form of reflexivity; early support and momentum generated enthusiasm that ultimately led to his victory. Both sides exhibited fallibility—Democrats overestimated Clinton’s support, while Republicans underestimated the opposition to Trump.

Vuk Vukovic, the CIO and co-founder of Oraclum Capital, is acutely aware of reflexivity and fallibility’s impact on politics and economics. Over the past decade, he has applied his academic research in political economics to accurately predict the outcomes of the past two U.S. elections and the Brexit referendum, as well as influence policy in his home country of Croatia. Following the pandemic, Vuković and his co-founders sought to monetize their predictive success, leading them to the financial markets. Today, they use the wisdom of crowds and their understanding of social networks to outperform markets with their hedge fund. Vuković graciously joined Physik Invest’s Market Intelligence podcast to discuss his career, research, starting and operating a hedge fund, trading psychology, and investment processes. The video can be accessed at this link and below. An edited transcript follows.

We spoke in April, and Oraclum Capital, your upstart hedge fund, sat at ~$8.6 million in assets under management. Has this number changed?

We’re going into September with $17 million under management, so it has been going well.

I want to go back in time before you studied economics. What were some of your big interests growing up, and how did they guide your pursuit of economics in school?

My interest in economics partly stemmed from my parents, who were both involved in that field. But even as a kid, I was fascinated by currencies and stock markets. Something about them attracted me—maybe it was the whole money aspect, but I think it was more profound than that. However, as I pursued my education, I diverted from finance and instead focused on political economics, which is more theoretical and combines public choice theory with macroeconomics. You can’t fully understand economics without understanding politics. Fast forward to today, I’ve returned to my first love, finance.

The idea of making money got me engaged in markets, but the details and the process kept me engaged. So, structuring trades, learning how markets work, and things like credit and positioning kept me involved. Does this resonate?

That’s the primary motivation, and you learn things that make it more or less attractive. In our case, it was more attractive.

So you went to the London School of Economics and the University of Oxford. Why those two?

Before that, I earned my Bachelor of Economics at the University of Zagreb in Croatia. During the summers of 2009 and 2010, I went to the United States—first to attend a summer school at Berkeley and then Harvard the following year. 

I considered staying in Zagreb, but after those experiences, I realized I should go abroad. I chose the United Kingdom because it was closer and less expensive than the United States, especially at the master’s level. In Europe, you typically pursue a master’s before a PhD, allowing you to finance your education gradually.

The LSE is a prestigious institution with a political economy program aligned with my interests. If I wanted to go to the United States immediately, I would have had to choose an economics PhD and then branch out from there, which is not what I wanted.

Did you get a lot of value from those summer schools? 

Absolutely. They showed me that I could compete in an environment where I wasn’t sure I would be able to.

I earned straight A’s at Berkeley and Harvard. I took an Intermediate Macroeconomics course and a Contemporary Theories of Political Economy course at Berkeley. At Harvard, I studied International Monetary Economics, taught by a former assistant to Milton Friedman. I also took a course on global financial crises there, which was particularly interesting to me because the Global Financial Crisis had just started in 2008. At that time, I was in my second or third year of university, and it shaped my research focus ever since. I found my niche by exploring the financial crisis from a political economy perspective, examining the political causes of the crisis, such as why banks were allowed to take on so much risk, and so on.

You wrote a couple of papers. How did you develop your theses, and how long did it take you to research and defend them?

Most of my political economics research explicitly focuses on corruption and lobbying. When I came to Oxford, my attention was primarily on the collusion between politics and economics—essentially, the relationship between the corporate and political worlds. 

It all began with a paper on corruption in Croatia, where I examined the connection between firms and people in power and how this relationship affected reelection chances. I also attempted to measure corruption through public procurements awarded to specific firms. Unfortunately, my findings showed a significant impact of corruption on the reelection chances of Croatian mayors, cities, and municipalities.

The second paper I worked on centered around bank bailouts in the United States during the 2008 crisis, which has been a focal point of my research interests. I aimed to determine whether banks better connected to congresspeople received a more favorable bailout deal relative to their assets, and indeed, they did. With these two ideas and the supporting data, I developed a more unified theory on how corporate executives and politicians connect and how those connections impact economic outcomes. In my specific case, I was looking at income distribution and inequality.

This led to my third paper at Oxford. I analyzed a massive dataset of about a million corporate executives in the United States and the United Kingdom, linking them to politicians and observing that those better connected had much higher salaries. Specifically, the impact was about $150,000 more in annual salary in the United States. To clarify, these were corporate executives—CEOs, the C-suite, or board members—being compared within the same company, with the politically connected ones earning a premium of approximately $150,000. Political connections were measured by whether the executive had previously worked with someone at a senior government level or belonged to the same organization, such as a country club, charity, or other networking group. These affiliations might not necessarily make you friends, but they provide a way to connect with critical individuals when needed.

This academic work culminated in the book I published this year, Elite Networks: The Political Economy of Inequality. It is trending well at Amazon, Barnes & Noble, and other retailers.

I remember this a couple of years ago: Amazon’s Jeff Bezos and Jerome Powell appeared at the same party or dinner. Jerome Powell was grilled over what was potentially discussed, and your response reminded me of that.

I was looking into that precisely during the Global Financial Crisis when Timothy Franz Geithner and Henry M. Paulson, Jr. held regularly scheduled meetings with the CEOs of the top eight banks. This was documented in The New Yorker and The New York Times. I was reading those transcripts, and it was clear that these people were friends. There’s also an excellent paper on social connections in a crisis, highlighting the importance of being connected—especially when you need to reach the right person to secure a bailout for your bank in times of crisis.

Graphic: Retrieved from CNBC.

Did your findings in Croatia ever have an impact on policy?

Surprisingly, yes, though not as much as I had hoped.

My main finding was that there are very suspicious levels of public procurement where companies with, for example, zero employees can bid and secure huge deals from local governments. I focused solely on the local level. One potential solution to combat this issue is to introduce complete budget transparency so that the public can see every single expenditure made by the government. This would include everything from large procurement deals down to receipts for lunches, dinners, and similar expenses. You could even see who’s dining with whom and the salaries of public sector employees.

We started implementing this project in a few cities in Croatia, including Bjelovar—about five or six cities. These cities adopted the project with a message of having nothing to hide and being open and completely transparent. Incidentally, all the mayors who implemented our project significantly outperformed their opponents in subsequent elections. So, while corruption may help you get reelected, being fully transparent helps even more.

We wanted to extend this project to a broader audience of mayors, but unfortunately, the interest wasn’t there. What did happen, however, was that we were able to make this a formal part of the budget law. But now, the problem is that the bureaucracy watered it down. The law explicitly requires every local government to have full transparency, but as they say, the devil is in the details. Bureaucrats added a second layer of interpretation, defining what it means to be fully transparent, and the law’s impact has been diluted. So, I’m done fighting those battles. That’s behind me, and I’m doing something completely different now.

How did you develop the methodology used to predict elections, and how did you monetize it?

I didn’t initially think about starting a hedge fund, but I knew there was some applicability in markets.

So, my two colleagues, Dejan Vinković, a physicist, and Mile Šikić, a computer scientist, and I were in the academic sector. They were professors, and I was a lecturer at my university. We wanted to find a new way to create better, more predictive surveys. We were looking at what Nate Silver was doing in the United States, and since the three of us were all political junkies, elections were the first thing we wanted to apply these methods to. So, we started with the British elections in 2015, and it worked well. Our correct prediction of the Brexit referendum and Trump’s 2016 election further propelled us; we initially wanted to write a paper on our new prediction method, but we opted to try to build a company and monetize it instead.

Now, what’s the logic behind that? There are two components. 

The first is the wisdom of crowds. You ask people what they think will happen and what everyone around them thinks will happen. Let’s say it’s an election. So, who is going to win, Trump or Harris? That’s the first question. Second, what do you think other people around you think will happen? When you get to that second question, you put people in other people’s shoes, forcing them to switch between System 1 and 2 thinking, as Daniel Kahneman and Amos Tversky describe.

The second part involves the networking aspect, the crux of our approach. We aimed to figure out who was friends with whom. For example, if you’re in a liberal or conservative bubble, you have a low ability to predict what’s going to happen outside of your bubble. So, we focused on people in more heterogeneous groups, where some friends are left-leaning, some are right-leaning, and some are centrist. This diversity increases the probability of making accurate predictions. The methodology involves playing with probabilities assigned to different individuals, and these probabilities have weights, which is how we determine the accuracy. So, not every person’s opinion matters in the same way. That’s the general idea.

Where would these surveys be accessible?

The crucial part is social media. Previously, during the elections, we did everything on Facebook. But this was before Cambridge Analytica when Facebook was very open to giving us the data we needed. We didn’t take any personal information besides what we asked for in the survey, like gender and age; we only gathered network data from Facebook. If your friends joined the survey with you, we could connect you. Now, we’re doing everything on Twitter and LinkedIn. We’re sourcing from those networks because Facebook no longer allows it following the Cambridge Analytica scandal. This is not a problem because people are typically on the same platforms. Again, we don’t need to know who these people are. All we know is who they’re connected with.

Would you have achieved the same results if you could go back and use Twitter and LinkedIn?

The data on Facebook was more versatile, and there was more of it. You could do more with a bigger pool. It wasn’t just the data itself but also the critical relationships between the data. Much of this was based on network theory in physics, akin to network science in general. My two partners, and later I, became remarkably proficient in this area. So, all we needed was good data to fit the theory and see if these things worked, and they did. With the Twitter data, I don’t think it would have been as helpful as the Facebook data, but once you learn what you need, you can apply it to any other platform that has a network.

How did you come up with the name Oraclum?

It’s a Latin word for prediction.

So, before starting the hedge fund, did you have any investing experience, and how did you learn about markets? What books did you read?

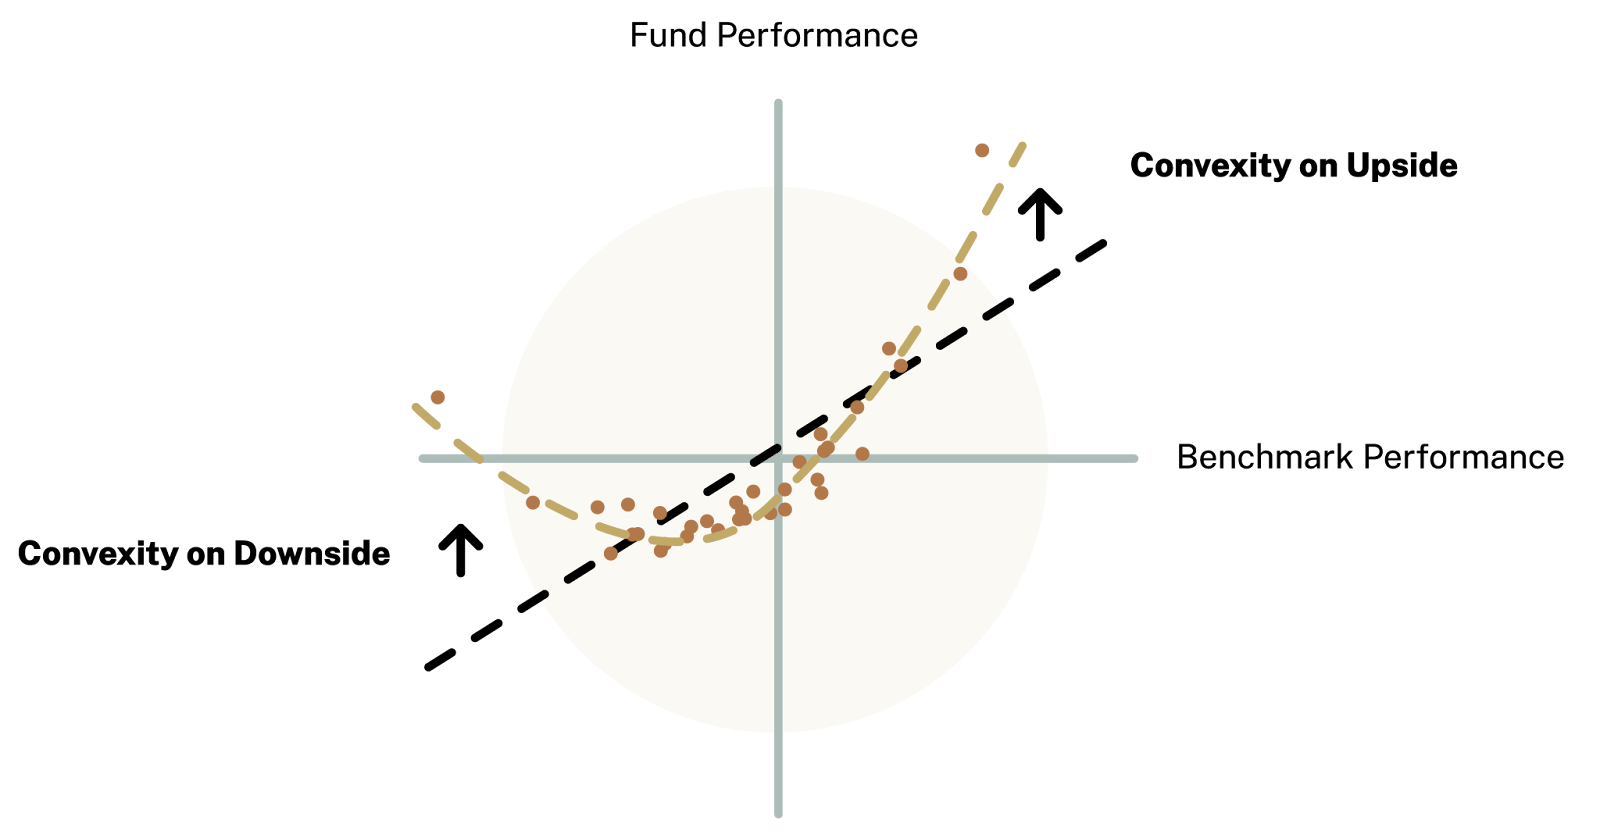
I’ve been investing on and off since 2011-2012. I began trading options in a retail capacity in 2018. Back then, trading options on Tesla was the name of the game, and I went through the whole trader experience. I love the Market Wizards book by Schwager because I went through the same processes as many of the people featured in it. You initially make a lot of money on something and think, “Oh my, this is easy, and I am so smart.” Then, you lose a lot of money on something else, and that’s when you start learning. So, I did have some experience with options. Since 2021, when I began testing Oraclum’s methodology, my options trading knowledge has improved significantly. We needed options because they provide convexity (i.e., non-linear payoffs), which is crucial when predicting with 60%-70% accuracy, which is what we achieved. So, while I did have some experience, it has grown exponentially over the past few years since I started the fund.

Graphic: Retrieved from Simplify Asset Management. “An investment strategy is convex if its payoff relative to its benchmark is curved upward.”

What did the fund structuring process look like, and what guided your decision to create a hedge fund versus an ETF, which would allow more people access?

The hedge fund versus the ETF is a matter of cost. Launching an ETF requires about $250,000 upfront, which is beyond our reach at the time. However, we aim to establish an ETF within the next few years to offer it to a broader audience. Many people who participate in our surveys are eager to invest, but with our current $100,000 cap, they can’t. The ETF would allow them to be investors, providing an even stronger incentive to participate and perform well in the surveys.

To answer your question further, we need to go back to 2016, around the time of Brexit and Trump’s election. That’s when we decided to start a company. We set up shop in the United Kingdom, specifically in Cambridge—no connection to Cambridge Analytica; we’re the good guys and don’t misuse data. Initially, we focused on market research projects on elections, market trends, and public sentiment. However, after correctly predicting the 2020 election outcome between Biden and Trump, we started attracting clients from the finance industry who were buying our election predictions. I thought, “Why not test this on the markets?”

We had some funds and could hire people to help us, so we began the project with the mindset of trying it out for a year or two. If it didn’t work, we could always return to market research. But the project quickly gained momentum. I invested about $20,000 of my own money, and over a year and a half, I grew it to $54,000. I did this transparently, posting screenshots of my trades in my newsletter. People could see my profits and losses weekly. I would even send survey participants the trades I planned to make, and this transparency resonated with them—some became investors.

Like many others, our biggest investor initially followed us on Twitter and subscribed to the newsletter. After nearly a year of testing, the final decision to start the hedge fund came around the summer of 2022. People following us said they wanted to invest more seriously, so we started the process. I remember discussing it with my wife and telling her, “You need the confidence of someone who knows nothing about something but does it anyway.” We launched the hedge fund in 2023 and learned as we went.

Before we started, I spoke with a lawyer and met with potential investors. I also surveyed newsletter subscribers to gauge interest and ask if they’d like to invest. We received around $10 million in commitments. Of course, there’s a difference between pledging money and investing it, so we only started with about $2 million when we launched the fund in February 2023.

Our hedge fund story differs from most. While others often launch with $100 million, $200 million, or even $1 billion, we’re bootstrapping our way up, starting small but with solid performance and growing trust from our investors. It’s an unconventional story, but we don’t need the typical team of analysts or a Bloomberg terminal. We have our method and trade in a very straightforward way.

What does it cost to run your type of operation?

In the first year, last year, the budget was about $100,000. It is more significant this year because I’m expanding the entire marketing scope. It’s projected to be around $400,000. However, with our profit, we’re comfortably funding the entire operation.

Was creating the fund structure cost-intensive as well? 

Surprisingly, no. It was about $30,000 altogether and set up in Delaware. I found good lawyers and used all the money I earned investing myself to fund it.

What does your investment process look like from pre- to post-trade?

It is straightforward. We get a signal every Wednesday before the market opens. Once we get the signal, we want to determine its strength. Then, we typically open positions about an hour after the opening, at about 10:30 Eastern on Wednesdays. We will keep the position until the end of trading on Fridays. This is the optimal timing for our prediction if we were right. We only allocate about 2% of our portfolio to each trade. If we’re wrong, the options expire worthless, and we lose 2% of the premium. If we’re right, then we make multiples of that. That is in a nutshell. Now, there are things that we can do. For example, we have this trailing stop strategy; if we make 1.5%, we will increase stops and keep raising them gradually. We have been testing and have considered using 0 DTE options in the other direction to hedge our profits.

Are these options spreads that you are buying? 

A vertical. We always buy spreads.

You would never try any complex or ratio-type structures, right?

No, we keep it simple. We used to, and the following is a great story about that.

The fund is performing well currently. However, right out of the gate in March of last year, we were down 15% on our first $2 million. At the start, we told our investors they would be out if we lost 20%, so it was a tricky situation.

What went wrong? Several things contributed. 

For background, I only risked 10% each week when trading alone. With about $20,000, this meant risking $2,000. A part of my strategy involved using iron condors, as our methodology works well in both direction and precision; our predictions are within 2% of the market’s actual ending about 80-85% of the time, which is quite significant. Thus, the iron condor structure worked well when trading on my own in 2021 and early 2022.

However, since the introduction of 0 DTE options, the price of the Friday options has changed dramatically, and the risk-reward ratio has shifted from 2:1 to 8:1; now, I would risk $800 to make the same $100. If I lost $800, I would need eight good weeks to compensate for one bad week. Consequently, iron condors are no longer viable. This structure, we know, significantly hurt us in the first quarter of 2023, which is why we abandoned it, along with others, focusing solely on directional options and spreads.

Graphic: Retrieved from Oraclum Capital.

My first thought was how much of that was the volatility environment. So you dropped the condors, and then, did you change how you traded the verticals?

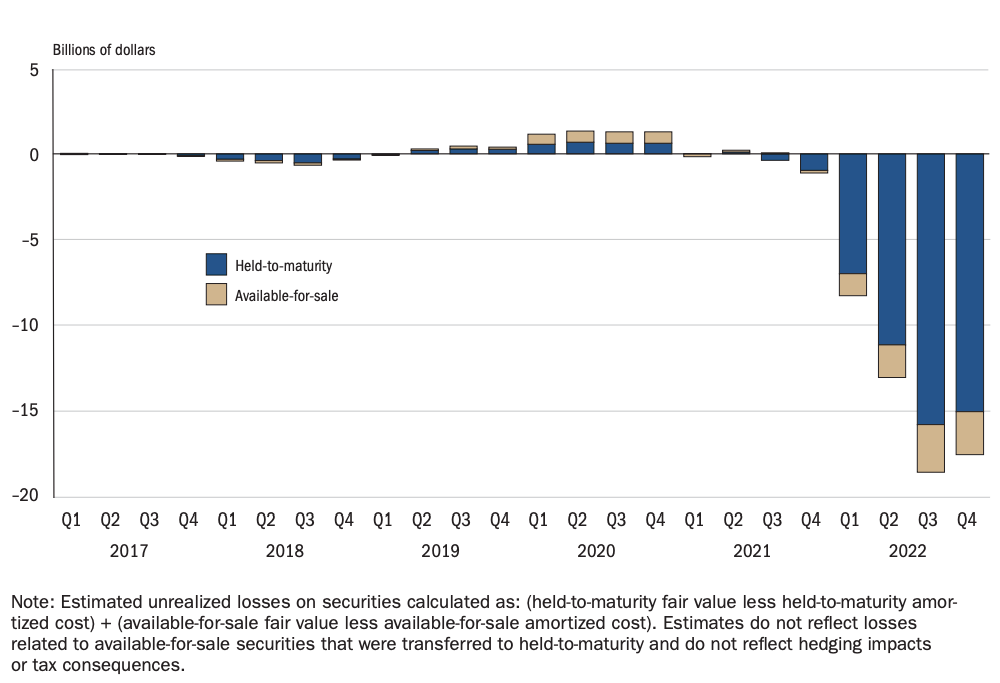
When we started the fund, we risked about 5%. When things quickly got out of hand, we lowered it; when we were down 15%, we reduced it to 1%, and it took us about five months to break even, gradually increasing our exposure. Now, we’ve found that 2% to 3%, depending on the strength of the signal, is our optimal point. So yes, it affected our position sizing. Regarding volatility in March of last year, the collapse of Silicon Valley Bank also impacted us.

Graphic: Retrieved from Federal Reserve. Due to the rapid pace of interest rate increases, Silicon Valley Bank’s unhedged bond portfolio significantly lost value, contributing to difficulties meeting withdrawal demands.

Would you consider trades like the iron condor again if the volatility environment changed?

It works for us over 80% of the time, but the risk-reward ratio is no longer suitable. That’s why we don’t want to engage again. The current data shows flat or slightly above-flat results, so there’s no point in doing it.

Do changes in volatility and positioning affect how you trade the underlying market? So, at the beginning of August, we had a bunch of volatility. You probably weren’t in positions at the start of the week because it was a Monday, and you avoided that. But do those significant changes in volatility impact how you structure trades?

Not the structure. 

Let’s go back to that week. On Monday, markets were down. We were mostly in bonds and cash. We ended the week up 1%, with the compression of volatility benefitting us; as volatility went down and markets went up, it was an easy trade for us in retrospect.

It would have been fantastic if we had held puts on that Monday. If we had held calls, we would have only lost the premiums. That’s why volatility doesn’t impact us negatively, no matter how big. This is because we’re not sellers of options. If we were sellers, that would be a different problem. However, since we buy options, the most we can lose is the premium. We know our risk—if we’re wrong in a week like that, we lose 2% and move on to the following week.

Also, I noticed a mismatch between bid and ask prices on that particular day. That is something to consider as well. But if I had put options and there was a huge mismatch, we would have worked them at the mid-price.

Graphic: Retrieved from Reuters.

How are you executing these orders? Are these just market orders, or are you setting a limit?

Always limit orders.

Are you using one of the ETFs, or do you use cash-settled indexes like the SPX?

ETF. Not the cash.

Would going into something like the SPX be more cost-efficient if you grow large enough?

Yes, absolutely. Right now, one of our institutional investors is coming in, and they want us to employ the same strategy using options on futures like the E-mini S&P 500 (FUTURE: /ES). Looking at the data, the approach also works there.

Are you testing trades in real time or backtesting?

Backtest.

If you were to go live with either the /ES or SPX, would you do that with a smaller size initially, test it out, and see how it works on that scale? 

Yes. Initially, use a smaller size and then push it up as we go along.

Right now, we’re small—a $17 million fund—so I trade a couple hundred thousand dollars worth of premium every week, which is not a lot. Once bigger, we can look to the SPX and /ES, where the liquidity pools keep increasing. 

As we grow in size, it’s straightforward for us to scale.

You said you risked 2%. Is the other 98% still in Treasury Bills?

90% in T-Bills, and 8% is a cash buffer.

Graphic: Retrieved from Exotic Options and Hybrids.

Because you’re always out of these spreads at the end of the week, I assume you’re pretty liquid and can quickly meet redemptions. 

Yes, that’s not a problem for us.

If interest rates fell or you had a significant lull, would that change how you invest that capital?

It probably would. Right now, we’re taking advantage of the carry. There’s a straightforward carry trade—you leave cash in bonds for a year and get ~4%. It will probably be a different instrument if we return to the pre-COVID interest rate environment or even post-COVID 2021. However, I would still want to keep most of it in bonds because of the safety. Think of it like Taleb’s “Barbell Strategy.” You have 90% in something very safe and 10% in something very volatile—in our case, 2%.

You’re not using box spreads, right? You’re actually in T-Bills, right?

We have T-Bills but will switch to box spreads because of the tax implications.

Graphic: Retrieved from the OCC.

How do you monitor the strength of the signals, and do you scale back if that signal weakens?

This is an ongoing process, and there are several things we’re looking at. Regarding the signal strength, we have KPIs. We’re monitoring whether the signal is improving or worsening over the past 4 or 5 weeks. If it falls below our crucial indicator, we say, “Okay, let’s see what the problem is, what’s happening, and how we can fix it?” Signal weakening can be due to several reasons, such as a drop in our survey response rates during slower periods of the year. If we can detect issues, we can prevent them from escalating. We allow ourselves a maximum of one lousy month.

Can you explain your fee structure?

We have a 1.5% management fee and a 25% performance fee subject to an 8% hurdle, accounted for quarterly. We must clear 2% each quarter before applying the 25% performance fee. There’s also a high-water mark in place. Performance fees can only be charged if the fund consistently makes money. So, if the fund makes money in one quarter but loses money in the next, it can only charge a performance fee once it has recovered the losses in the subsequent quarter and exceeded the previous high-water mark; the performance fee can only be applied to any additional profits after surpassing the previous peak value.

Despite being systematic, you’re still executing these by hand, inputting orders, setting limits, and so on, right? How do you manage any biases and emotions and just execute?

I have a psychology coach guiding me through this process, which is necessary. I’ve experienced losses before starting the fund, but managing other people’s money is different—it comes with much higher responsibility. Plus, you must report to these people regularly and inform them about any losses. This was particularly challenging for us in March of 2023 when we had just started the fund and were down 15%. We thought, “What do we do now, and how do we face these people again?” I did a lot of exercises to help myself cope with the situation, and I realized that the solution lies in sticking to the process. The less I meddle, the better our investment returns are; we achieve better outcomes by completely removing our biases and following the process, one of our key performance indicators. Ultimately, I aim to expand the team, hire traders, and stop trading myself. Although I could automate the entire process, it doesn’t always work as intended; sometimes, the machine won’t perform exactly as you want. That’s why I believe human traders still have value. We’re not high-frequency traders, so we don’t need machines to execute nanosecond trades. Instead, we rely on humans following a system to execute the orders.

Do you ever have a signal and you’re putting on a trade but think, “This isn’t going to work,” but you still go through with it because you are following a system?

Yes, but I’ve taught myself not to deviate. Sure, maybe this week I’m going to help it, but the next week I’m probably going to destroy it. Again, it is the whole psychological mindset thing. I still get the urge, but you’re pushing yourself to make this emotionless. It is a process, so it’s going to take a while.

So, the hedge fund feels like your second act to me. Do you have a third in mind, and may that involve you working in the government, especially given the research you’ve done?

I’m so removed from governments that it’s liberating. 

The three of us at Oraclum—Vinković, Šikić, and myself—are political junkies. Since starting the fund, I’ve asked myself why I even cared. At this point, it’s tough for me to think about a third act, especially now that we’re in the middle of building this. 

It depends on how much money I earn—maybe philanthropy or something else. We’ll see.

Have you done any work for the next set of U.S. elections? If so, can you share any results?

This is the big argument that my two co-founders and I have. One of them is against us doing this because of the focus of the fund, our investors, and everything else. And that makes sense. We won’t do it, even though I see it as a great marketing tool.

If you were to predict the next set of elections, what would you do differently?

I streamline much more toward the key swing states. 

Pennsylvania was the key state in the last two U.S. elections, 2020 and 2016. As soon as we saw in our survey that Trump was winning Pennsylvania in 2016, that was it; Trump was taking the election. The same happened in 2020. At no point did Biden ever lose Pennsylvania in our surveys. So that was the turning point for us. Ohio and Florida were going for Trump. Before this election, whoever won Ohio and Florida would become the U.S. president. Not this time because you had Pennsylvania and Michigan going in the other direction. So, if I were doing it this year, I would focus on a handful of swing states. You can follow the surveys for the rest, focusing on Pennsylvania and Michigan. Ohio and Florida will most likely go to Trump. But then, I would also look at Arizona, North Carolina, Georgia, Pennsylvania, Michigan, and Wisconsin.

I recently watched a podcast featuring Citadel’s Ken Griffin. In it, he emphasized the importance of studying your winners rather than getting too hung up on the losers. Does your experience validate this thinking?

That’s a good point. I get more excited about the winners and learn that the losers don’t matter—move on. 

There’s this great quote by Roger Federer: “In tennis, perfection is impossible. In the 1526 matches I played, I won almost 80% of them. But I only won 54% of the points in those matches.” For him, it’s not about the points. When they’re gone, they’re gone. You move on to the next one. It’s the same thing here. For every week we lose 2%, we move on. But when we get a big win, we’re delighted. It’s a psychological thing as well. You can get much more if you don’t cut the profits too soon and keep a trailing loss. That’s why we have weeks where we’ve made 5% or 6% in a week, which is good. So there is something to it. 

We study the winners because it can all come down to 5 or 6 weeks a year when we make the bulk of the return on the fund. Everything else cancels out; the small winners and losers cancel each other out.

Graphic: YouTube interview with Citadel’s Kenneth Griffin.

Do you have any mentors or people you look up to? 

I love that Market Wizards book by Schwager. Every interview in it is very revealing and comforting. When I was younger, I idolized George Soros. What we do has nothing to do with how Soros trades; he’s a big ideas guy, and I could never compete. It’s the same thing with people like Ray Dalio. It’s a different way of competing. 

I want to emulate someone like Paul Tudor Jones.

Do you have a favorite book recommendation?

Nassim Nicholas Taleb opened my eyes to options trading. After I read his third book, Antifragile: Things That Gain from Disorder, I thought, “Options are interesting; let’s see how this works.” I also think psychology books are great. So, Trading in the Zone: Master the Market with Confidence, Discipline, and a Winning Attitude and Schwager’s Market Wizards are fantastic because traders often make the same stupid mistakes; everyone goes through the same process.


Disclaimer

By viewing our content, you agree to be bound by the terms and conditions outlined in this disclaimer. Consume our content only if you agree to the terms and conditions below.

Physik Invest is not registered with the US Securities and Exchange Commission or any other securities regulatory authority. Our content is for informational purposes only and should not be considered investment advice or a recommendation to buy or sell any security or other investment. The information provided is not tailored to your financial situation or investment objectives.

We do not guarantee any information’s accuracy, completeness, or timeliness. Please do not rely solely on our content to make investment decisions or undertake any investment strategy. Trading is risky, and investors can lose all or more than their initial investment. Hypothetical performance results have limitations and may not reflect actual trading results. Other factors related to the markets and specific trading programs can adversely affect actual trading results. We recommend seeking independent financial advice from a licensed professional before making investment decisions.

We don’t make any claims, representations, or warranties about the accuracy, completeness, timeliness, or reliability of any information we provide. We are not liable for any loss or damage caused by reliance on any information we provide. We are not liable for direct, indirect, incidental, consequential, or damages from the information provided. We do not have a professional relationship with you and are not your financial advisor. We do not provide personalized investment advice.

Our content is provided without warranties, is the property of our company, and is protected by copyright and other intellectual property laws. You may not be able to reproduce, distribute, or use any content provided through our services without our prior written consent. Please email renato@physikinvest for consent. 

We reserve the right to modify these terms and conditions at any time. Following any such modification, your continued consumption of our content means you accept the modified terms. This disclaimer is governed by the laws of the jurisdiction in which our company is located.
Categories
Commentary

BOXXing For Beginners

Good Morning! I hope you had a great weekend and enjoy today’s letter. I would be so honored if you could comment and/or share this post. Cheers!

Nvidia Corporation (NASDAQ: NVDA) beat on earnings last week, lifting the entire stock market.

Graphic: Retrieved from Bloomberg via Christian Fromhertz.

The chipmaker confirms it can meet lofty expectations fueled by the artificial intelligence boom, with demand for Nvidia’s newest products likely to outpace supply throughout the year. Despite mounting competition and regulatory challenges in markets like China, Nvidia pursues strategic partnerships to expand its distribution channels.

Graphic: Retrieved from Bloomberg via @Marlin_Capital. NVDA eclipses $2T market capitalization, with its 12-month forward PE now at 33.

Before the earnings announcement, heightened implied volatility derived from options prices on the chipmaker’s stock indicated anticipation of significant fluctuations. The at-the-money straddles, composed of call and put options, suggested movement expectations of as much as +/-10% after earnings.

Various methods exist to estimate the expected move. One approach involves taking the value of the at-the-money straddle for the front month and multiplying it by 85%. Another entails using a narrow range of options.

The volatility skew, which will be defined later, implied that the perceived risk of movement was tilted toward the upside. In any case, staying within the anticipated movement would not favor options buyers, as we show later.

Graphic: Retrieved from Bloomberg.

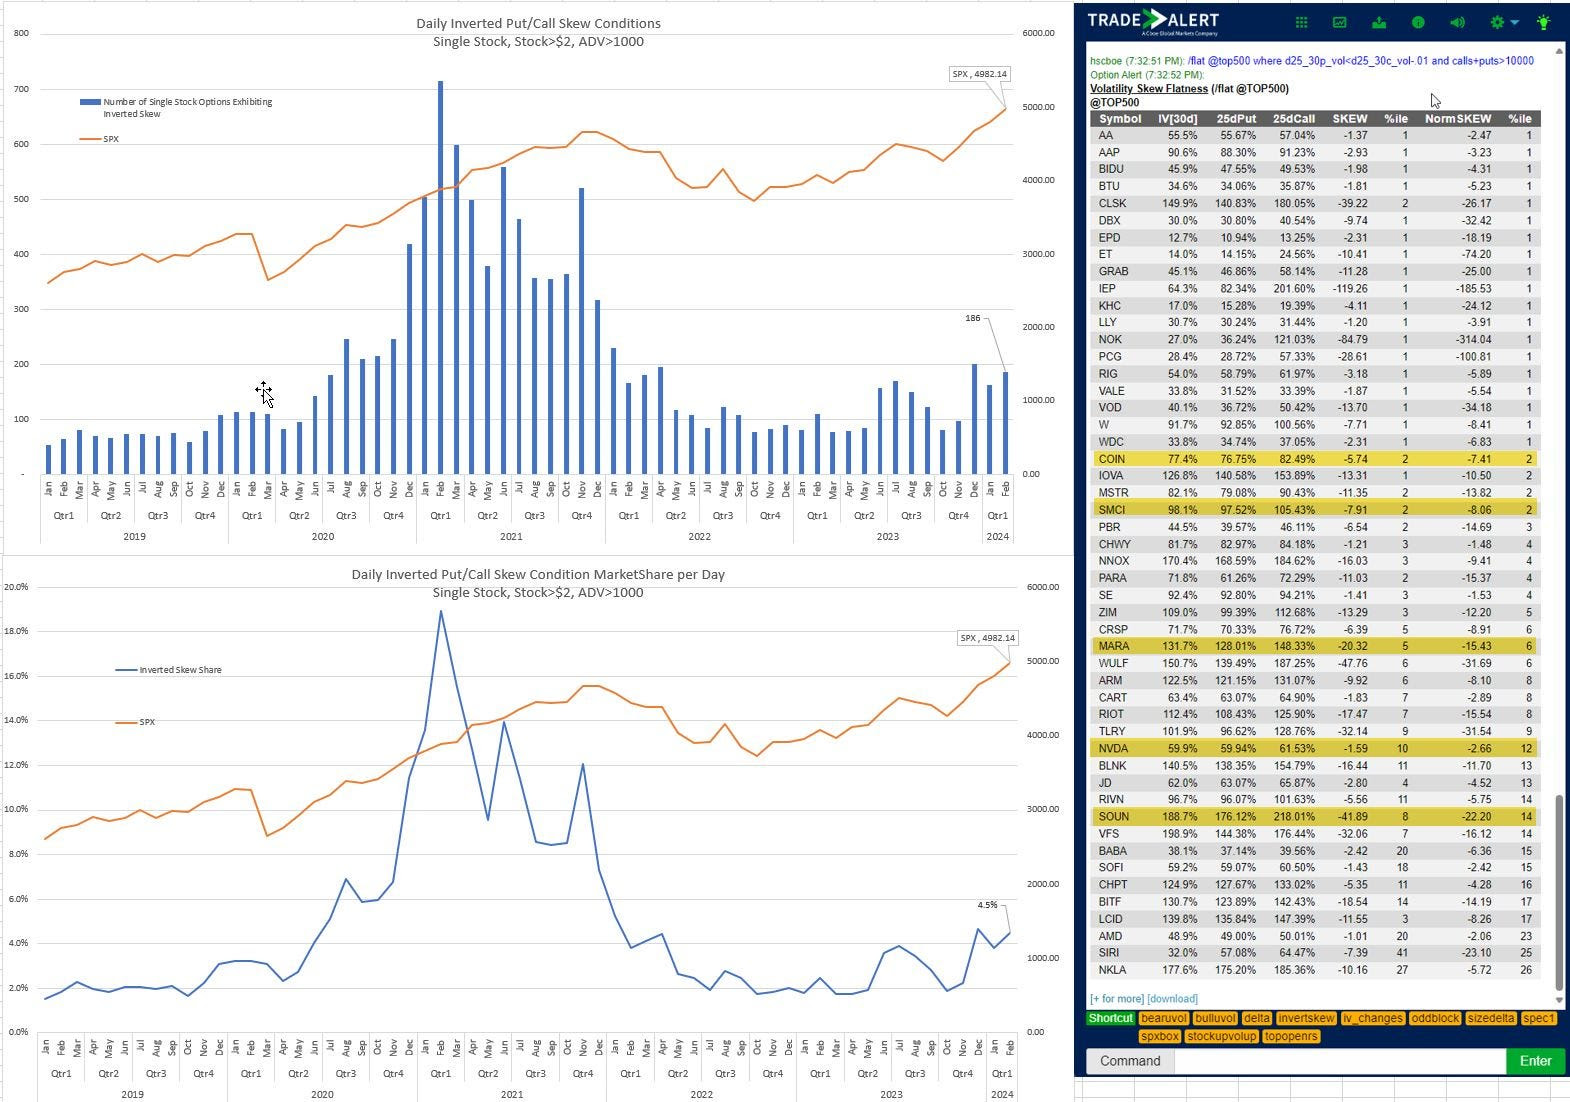
Since late 2023, traders have increasingly been hedging against or speculating on market upswings. This is evident in the higher call option implied volatility. Expectations for significant upward movement are particularly notable in the growing number of stocks where the 25 delta call implied volatility exceeds the 25 delta put implied volatility, shares Henry Schwartz of Cboe Global Markets.

To elaborate, options delta (∆) measures the change in an option’s price relative to changes in the underlying asset’s price. It indicates the option’s sensitivity to the underlying asset’s price movements. A delta of 0.50 means that for every $1 change in the underlying asset’s price, the option’s price would change by $0.50 in the same direction. The skew reflects the difference in implied volatility between out-of-the-money call and put options with the same delta. 

When the 25 delta call implied volatility surpasses that of the 25 delta put implied volatility, a more pronounced positive skew suggests traders are willing to pay a premium for calls. Conversely, if the 25 delta put implied volatility exceeds that of the 25 delta call implied volatility, often observed in products like the S&P 500 (due to concerns about protecting equity downside), there is a negative skew or stronger inclination to pay a higher price for put options.

Graphic: Retrieved from Henry Schwartz.

This persistent fear of missing out on sudden upward movements manifests a cascading effect when markets move higher, says Nomura Americas Cross-Asset Macro Strategist Charlie McElligott.

“The key to equities seemingly being able to keep shaking off nascent pullbacks? Well outside of the ongoing ‘AI  euphoria’ theme and de-grossing of shorts, … it’s been all about the Pavlovian ‘options selling’ flows, which continue to suppress [implied volatility].”

Graphic: Retrieved from Nomura.

As explained by McElligott, these “options selling flows” have the potential to amplify momentum. For instance, when traders or customers purchase call spreads, as they are large, the counterparties or dealers are left with a short skew, negative delta position that loses money if implied volatility rises or markets rise. In response to a rising market, dealers may manage their delta by selling put options or buying call options, stocks, or futures. Adding these positive delta hedges helps propel the market into uncharted territory during swift movements.

Graphic: Retrieved from Nomura.

As validation, after Nvidia Corporation’s stock surged about 10% post-earnings, Bloomberg reported that “to fully re-hedge all open option positions coming into the day, 51 million shares, or 91% of the daily average,” would need to be traded. Bloomberg added that the March 15 $680 call, February 23 $700, and $750 calls experienced the most significant changes in the delta before the market opening.

Graphic: Retrieved from Bloomberg via Global_Macro or @Marcomadness2.

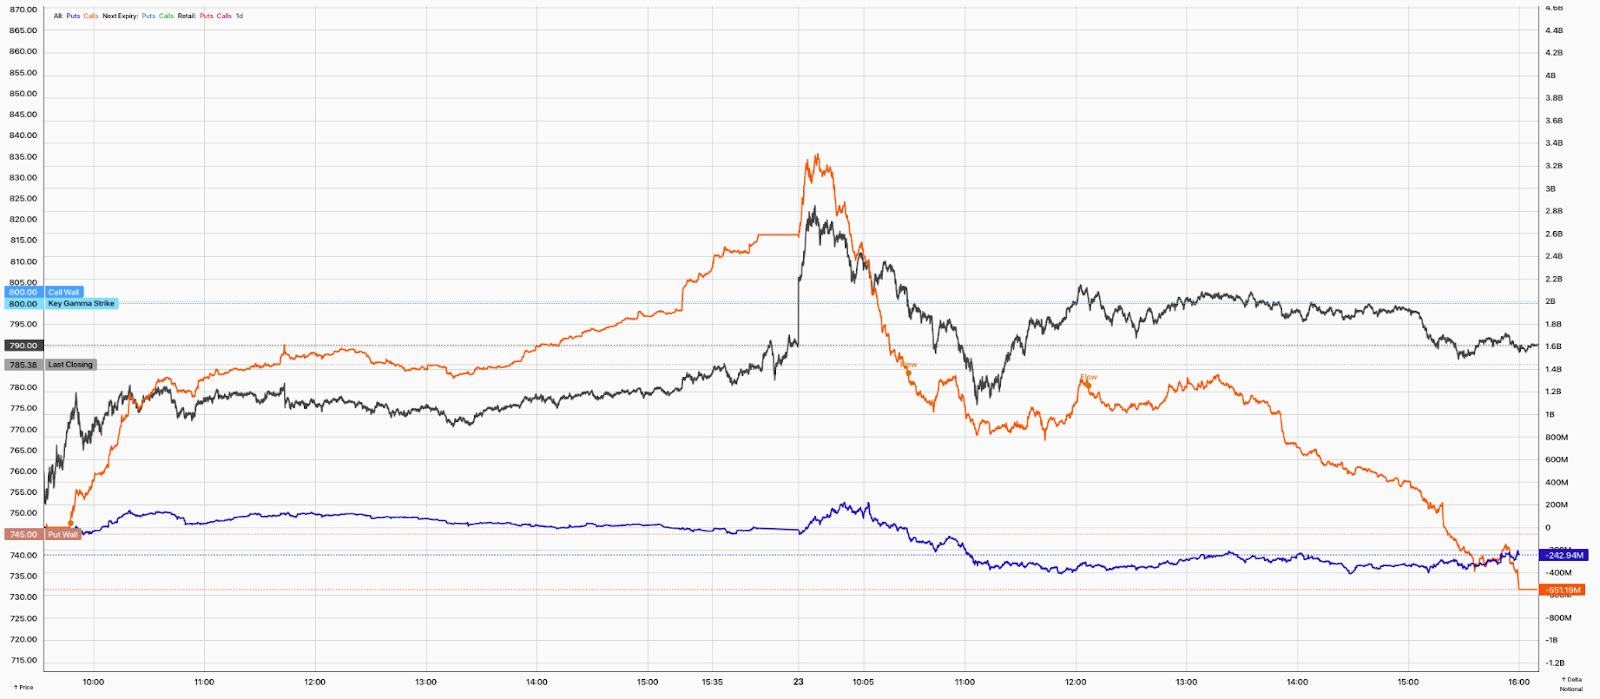
Observing SpotGamma’s real-time options hedging impact measure HIRO, the chipmaker was boosted partly on positive flows from the hedging of call options, as shown by the orange line below, while put options trading had a limited effect, as indicated by the blue line. The re-hedging activity positively affected the stock on Thursday post-earnings and had a pressuring effect on Friday, owing to the short-datedness of some of the options exposure traders initiated.

Graphic: Retrieved from SpotGamma. 

While mentioning pressures, see below the volatility skew before (green) and after (grey) earnings. 

Graphic: Retrieved from SpotGamma.

Short-dated options with very high strikes (e.g., 900+) and close expiration dates (e.g., ten days) struggled to hold their value. SpotGamma shared that the pricing of near-the-money $785 calls expiring on March 15 returned to their previous levels just a week before earnings. Since the actual movement closely matched the expected movement, there was little justification for options well above the market (i.e., +30%) to retain their value.

Graphic: Retrieved from Bloomberg via SpotGamma.

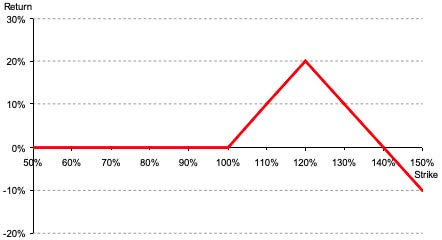
At Physik Invest, we foresaw such a situation and executed 100-point wide 1×2 call ratio spreads between the 900s and 1000s for a credit of approximately 0.90. We closed these positions the next day for an additional credit of 0.50 when the 1000 strike options failed to keep their value as good as the closer 900 strike options. The resulting profit was a 1.40 credit per spread.

Graphic: Via Banco Santander SA (NYSE: SAN) research. The return profile, at expiry, of a 1×2 (buy 1 and sell 2 further away) ratio spread.

Please be aware that similar trades are present in other high-flying products, albeit less widespread than in 2021 during the meme-stock trend. A simple way to determine whether such trades are safe is to check the pricing of fully in-the-money spreads. If the spreads trade at substantial credits to close, they are worth considering. However, if the spreads require a debit to close, it’s best to avoid them. In the case of Nvidia, the 100-point spread was priced at 25.00 in credit to close the day of earnings.

Graphic: Retrieved from TD Ameritrade’s thinkorswim platform.

Generally speaking, this trend in implied volatility is something that may continue. Kris Sidial from The Ambrus Group says the trend, which masks the risks of short volatility under the hood, such as those tied to risk-management practices, is driven by several factors not limited to the following:

(1) Increased demand for call options.

(2) Larger institutions seeking volatility as a hedge against rising risk exposure as the S&P 500 climbs. 

(3) Significant market movements make it difficult for implied volatility to decrease significantly.

Must Read: Two Major Risks Investors Should Watch Out For

Graphic: Retrieved from The Ambrus Group.

As such, Sidial suggests that “there is significant value in embracing volatility in both directions,” hedging against geopolitical and economic uncertainties while also capitalizing on the market upside. As discussed last week, we focus on leveraging elevated skew to reduce the cost of bullish trades (e.g., metals). Additionally, we plan to replenish our long put skew by acquiring put spreads in equities as a precaution against potential risks ahead, mainly local market peaks this time of year.

Graphic: Retrieved from Bloomberg via Tavi Costa.

With recent data dissuading anticipated cuts, there’s room to safeguard cash at higher rates for longer. 

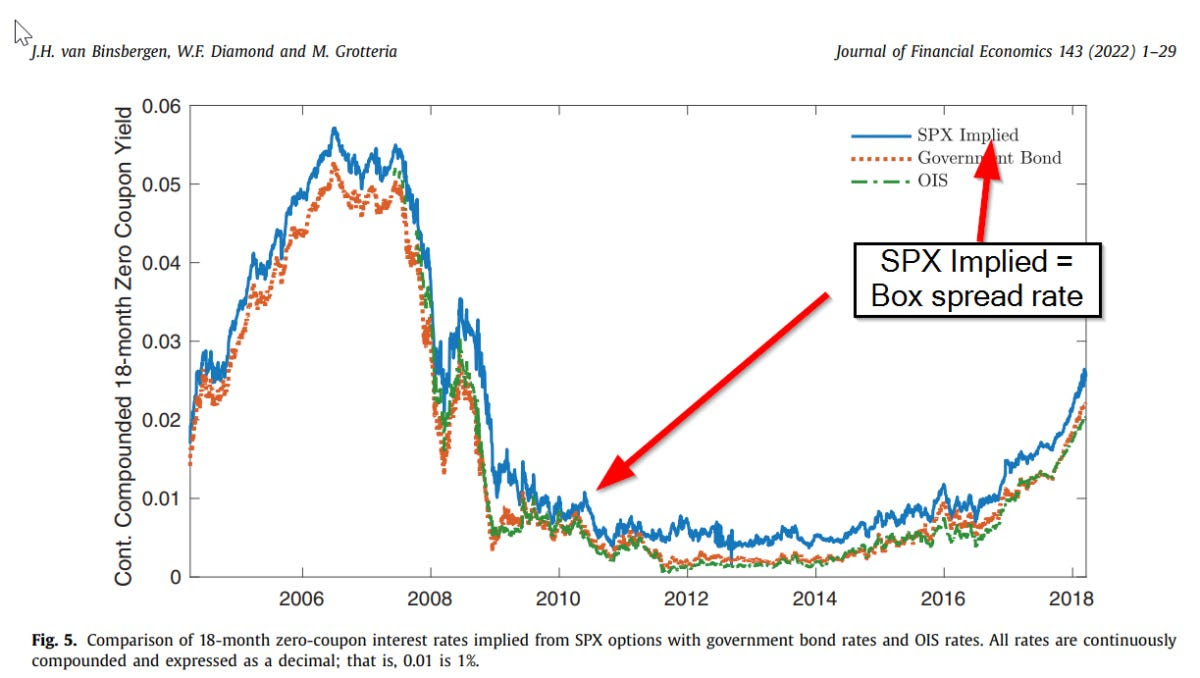
One trade structure to help us do so is the box spread, which includes benefits such as a convenience yield, capital efficiencies achieved through portfolio margining, easy entry/exit on an exchange through most retail brokers, and potential 60% long-term and 40% short-term tax treatment.

Graphic: Retrieved via Alpha Architect. 

Like a Treasury bill, the loan structure combines a bull call spread and a bear put spread. In a bull call spread, an investor purchases a call option and sells another at a higher strike price. A bear put spread involves buying a put option and selling another at a lower strike price. The lower (X1) and higher strikes (X2) match for a box spread, with all legs sharing the same expiration date.

Graphic: Retrieved from OCC.

In calculating the loan rate, we take, for example, a recent box spread trade of Physik Invest’s: BOT +1 IRON CONDOR SPX 100 (Quarterlys) 31 DEC 24 3000/6000/6000/3000 CALL/PUT @2867.90 CBOE.

[(WIDTH−PRICE)/Price](365/DTE) = Implied Interest Rate

Where:

WIDTH: Distance between higher and lower strikes

PRICE: The price of the box spread

DTE: Days until the trade matures

[(3000-2867.90)/2867.90](365/319) = 0.0527036866 = 5.27%

We lend $286,790.00, at a risk-free rate of 5.27%, in exchange for $13,210.00 of interest at maturity. You can track box spread yields more quickly using tools like boxtrades.com. Such insights open up several strategic avenues for traders.

One approach is investing about 95% of your cash into box spreads to return the principal at maturity, risking the 5% interest you make on trades with a limited downside (e.g., SPX bull call spread). 

A more preferable option exists for portfolio margin traders. Portfolio margining is a risk-based approach to determining margin requirements in a customer’s account, aligning collateral with the overall portfolio risk. Portfolio margining considers offsets between correlated products, calculating margin requirements based on projected losses. This approach may lower margin requirements, allowing for more efficient capital utilization.

As portfolio margin traders, we retain our buying power due to the minimal directional risk associated with box spreads, allocating it to other margin-intensive trades. To illustrate, if such a trader initially invests $100,000 in box spreads, they are left with $0 in cash and $100,000 in buying power available for margin-intensive trades (e.g., synthetic long stock or the purchase of an at-the-money call and simultaneous sale of an at-the-money put). You get your inflation protection while participating 100% in up-and-down market movements. Why not, right?

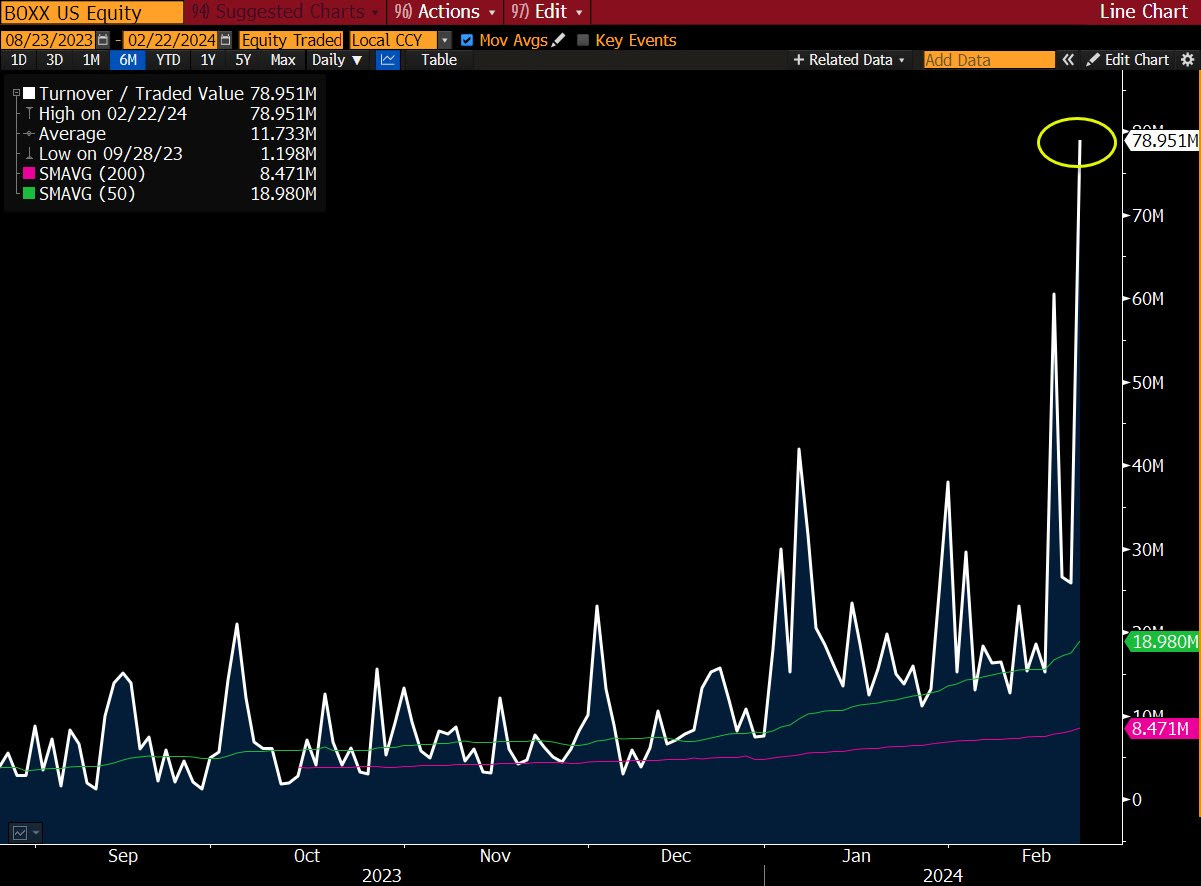
The point of the above passage is that much of what you see online can be done yourself in a tax, margin, and cost-efficient way. Alternatively, you can be hands-off, investing in money markets and CDs or complicated yet cool products like the popularized Alpha Architect 1-3 Month Box ETF (BATS: BOXX), which has grabbed attention for its tax arbitrage through complex strategies and loopholes.

Graphic: Retrieved from Bloomberg via Eric Balchunas.

With BOXX, you’re investing in something as safe as short-term Treasury bills, but you can get your money back anytime and enjoy better tax treatment than Treasury bills. Bloomberg’s Matt Levine has an excellent write-up on the mechanics of BOXX, which you can read here.

We digress. You can do more with your unused cash and buying power when following the methods outlined earlier and as we put well in our “Investing In A High Rate World” report published in April 2023. There, we discussed return stacking utilizing Nasdaq call ratio spreads and S&P 500 box spreads, two trades that continue to kill it this year.

Graphic: Retrieved from Bespoke Investment Group.

We choose these structures, which have limited losses in case of market downside, for the following reasons: There is considerable support for the market, but this support appears fragile. For one, we refer to record-level dispersion trading, which involves the sale of index options and buying options in individual stocks. 

It’s the same short volatility exposure Sidial has warned us about. With some stocks realizing substantial differences in movement from the index, this booming trade may have gone too far, setting the stage for a potential market reversal.

The situation resembles the period leading up to Volmageddon when short-volatility strategies backfired. Implied correlations are low, and if a market shock occurs, investors may be forced to close out their trades, which could feed volatility. As was in the case leading up to Volmageddon, however, volatility can cluster and mean-revert for longer.

Graphic: Retrieved from Bloomberg via Tallbacken Capital Advisors.

.

Categories
Commentary

Reversion To The Meme

Good Morning! I hope you had a great weekend and enjoy today’s letter. I would be so honored if you could comment and/or share this post. Cheers!

After a period of taking the stairs up, markets took the elevator down last week. Through Tuesday, the S&P 500 fell over 2.5% on a Consumer Price Index (CPI) print, which signaled higher-than-expected inflation. Internally, the selling was heavy.

Graphic: Retrieved from TradingView. Market Internals as taught by Shadowtrader’s Peter Reznicek.

Additionally, options were repriced in a big way.

Graphic: Retrieved from Bloomberg via Options Insight.

Let’s digress. 

Recall that options implied volatility is a measure of the market’s expectation of the future volatility of an underlying asset, as reflected by the supply and demand of options themselves. Higher implied volatility indicates more significant expected price fluctuations.

Options implied volatility skew refers to the unevenness in implied volatility levels across different strike prices. Steep, smile-looking, or v-shaped volatility skew reflects a scenario where increased market volatility disproportionately impacts farther away strike options due to (expected) losses from more frequent delta rebalancing in a moving market. Options traders assign higher implied volatility to those farther away strike options to compensate for increased risk/cost, often enabling savvy traders to exploit these variations to reduce their hedging costs.

Moreover, before last week’s drop, the S&P 500’s implied volatility skew was subdued, as indicated by the grey-shaded area below. Tuesday’s decline coincided with increased options trading activity and demand, leading to a notable upward shift in skew. Distant S&P 500 put options experienced significant increases in implied volatility (see the below grey line moving away from the shaded area).

Graphic: Retrieved from SpotGamma. Volatility skew for S&P 500 options expiring March 15, 2024.

Though skew remains elevated, broader implied volatility measures, such as the Cboe Volatility Index or VIX, declined as rapidly as markets rallied in the days following Tuesday’s downturn.

What’s happening?

Despite further negative economic indicators, such as hot producer prices or weaker retail sales and manufacturing output, markets surged strongly, closing the week almost unchanged. Beyond significant investor inflows into stocks, totaling approximately $16 billion on Wednesday, according to Bank of America Corporation, analysis of S&P options positioning revealed mechanical demand for the S&P 500, as highlighted by SqueezeMetrics. Higher implied volatility strengthened an automatic buying mechanism, supporting markets.

Graphic: Retrieved from SqueezeMetrics. Dealer S&P 500 Vanna Exposure or VEX.

This phenomenon is partially attributed to the significant options selling discussed in our recent newsletters, acknowledging the warnings issued by Cem Karsan of Kai Volatility and Kris Sidial of The Ambrus Group. Essentially, there’s been a rush among options sellers to enter into sizable positions, exemplified by the substantial options selling activity observed last week. UBS Group highlighted the persistence of this concerning toxic flow, noting aggressive trader actions, such as the sale of “70K of Thursday expiry 4120 puts at 0.05 on Wednesday.”

Graphic: Retrieved from Goldman Sachs Group Inc.

The estimated risk profile of this position is provided below (please allow for a margin of error of a day or two due to expiry). Essentially, it’s unfavorable, with the option seller at risk of losing much money if the market drops or implied volatility increases. Please be aware that we’re assessing this position independently, without knowledge of the option seller’s overall portfolio, including potential risk offsets from other positions they may hold.

Graphic: Retrieved from TD Ameritrade’s thinkorswim platform using the Analyze function.

Customers favoring such positive delta “short skew” positions prompt dealers on the other side to assume a negative delta (i.e., make money if the market is lower or implied volatility is higher) “long skew” or “long options” position, which they may manage through the sale of put options or the purchase of call options, underlying stock shares, or futures for hedging purposes. For a deeper understanding of these mechanisms, refer to SqueezeMetrics’ paper, “The Implied Order Book.”

Graphic: Retrieved from SqueezeMetrics.

This all happened during a seasonally weak period. We’ll go past the positioning side of things in a moment, so bear with me, but you can see the drop-off in options deltas following mid-February below.

Graphic: Retrieved from ConvexValue.

In essence, despite the anticipated reduction in options-based support, which Cem Karsan describes as a “window of non-strength” or a scenario conducive to increased volatility, the market’s reaction to Tuesday’s drop stemmed volatility. Observing these dynamics in real-time, here’s how we responded.

Graphic: Retrieved from Goldman Sachs Group Inc.

We had proactively positioned ourselves for a potentially weaker February, capitalizing on overlooked hedge opportunities outlined in recent newsletters—specifically, put spreads like butterflies. Others did similar, with Nomura Americas Cross-Asset Macro Strategist Charlie McElligott noting increased buying of put butterfly spreads in recent weeks (please see our late January and early February letters).

Depending on their setup (including the distance between strikes, the distance from the spot price, and the expiration timeframe), these spreads were positioned to profit from market declines. When the drop occurred, the unbalanced, very far out-of-the-money structures were priced to be closed at a small debit loss when the skew elevated substantially. Utilizing real-time analysis, we concluded it was opportune to increase our exposure to these far out-of-the-money units, capitalizing on the surge in implied volatility while cashing in on the closer spreads priced for a credit profit.

Graphic: Retrieved from Goldman Sachs Group Inc.

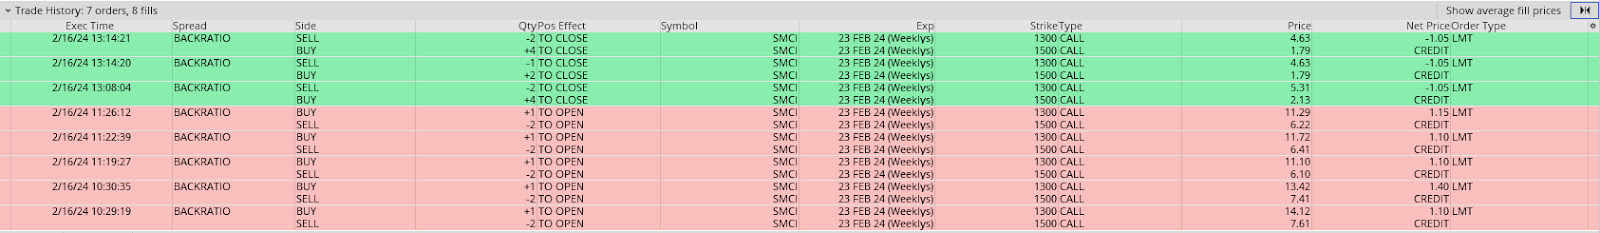
As markets recovered, we closed the recently initiated riskier spreads, freeing up buying power for opportunities elsewhere, such as in NVIDIA Corporation (NASDAQ: NVDA) and Super Micro Computer Inc (NASDAQ: SMCI), where a significant volatility skew, driven by heightened call options trading, enabled us to generate credit from short-dated spread trades.

By Friday’s end, we achieved one of our most successful weeks of the year, boosting our confidence and reinforcing our patience with underperforming trades, like the put butterfly hedges. PAY-tience!

Graphic: Retrieved from TD Ameritrade’s thinkorswim platform.

What motivated our actions? Let’s elaborate.

Tactically, we favor owning options to express our opinions efficiently selling options further out to reduce costs. Occasionally, we will utilize a ratio, such as selling two options for every one purchased. For those less experienced, simplicity often proves effective. Consider straightforward approaches like purchasing a wide put vertical, entailing buying a put, and selling a put at some greater distance. Depending on your position, the returns may come in at multiples of each unit of risk undertaken.

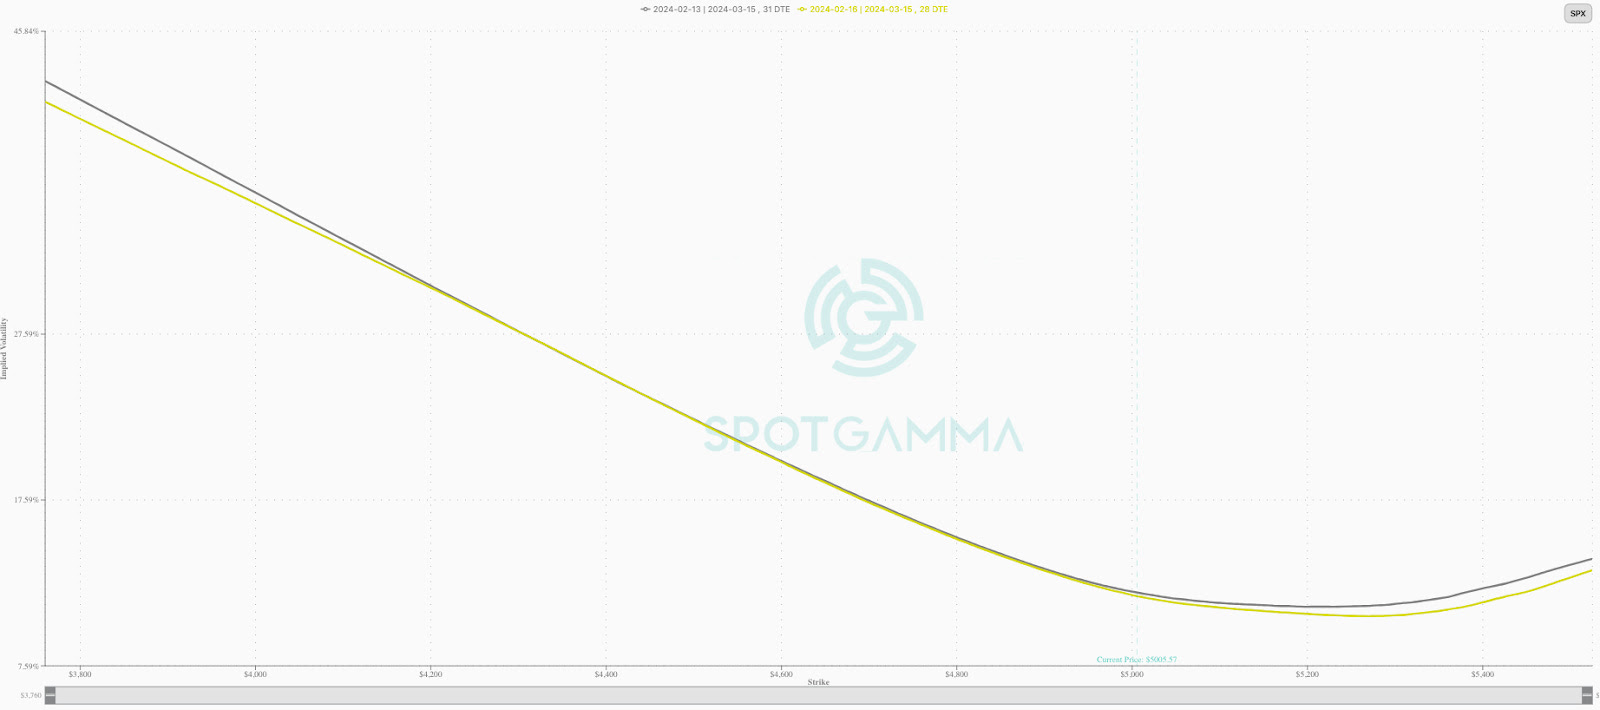
Furthermore, the speculative trading and crowded positions in equities (as previously discussed in this and prior newsletters), along with the persistent volatility skew (as indicated by the yellow line compared to the grey line below), imply that hedging strategies (such as owning longer-dated calls and selling stock/futures as a combination, or using put option spread strategies to hedge shares) may continue to be appealing.

Graphic: Retrieved from SpotGamma. Volatility skew for S&P 500 options expiring March 15, 2024.

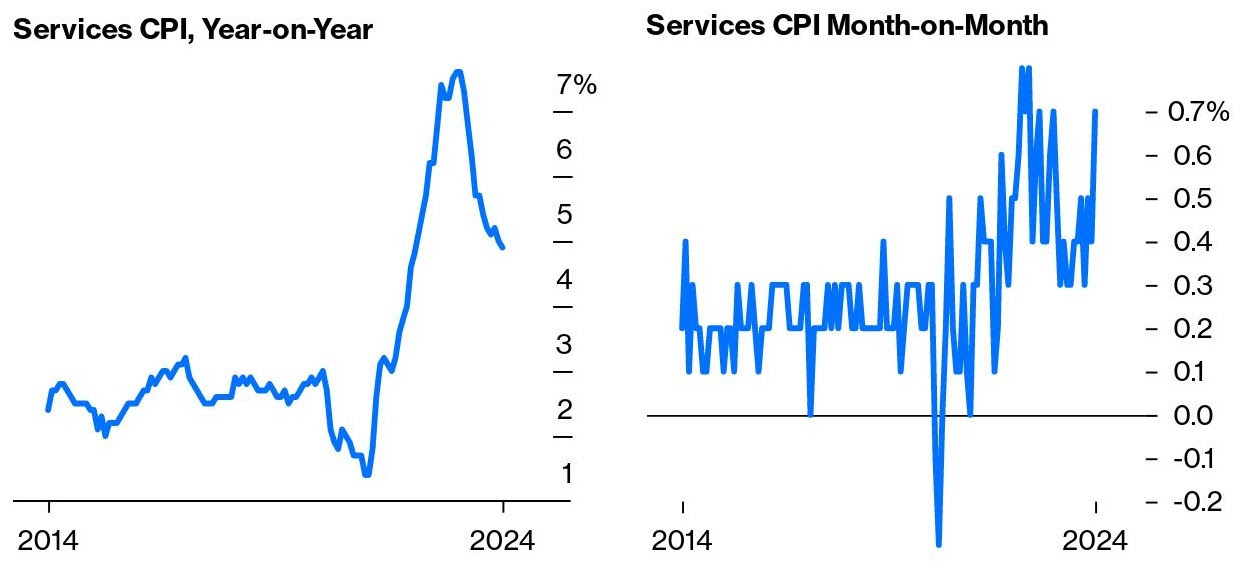
In terms of what to hedge, as highlighted by Fallacy Alarm, mid-February traditionally signals local market peaks due to significant cash injections followed by selling pressure to cover tax obligations. Additionally, a dilemma presents itself: should the focus be on combating inflation or stimulating growth? Presently, the data would dissuade anticipated rate cuts, though such actions might be contemplated if the Personal Consumption Expenditure, a key metric, points to lower price increases, particularly in services. Current interest rate projections suggest a bimodal scenario with a low probability of sudden rate declines.

Graphic: Retrieved from Bloomberg.

As further context, John Authers of Bloomberg says there remains a risk of overheating or a scenario where the economy remains robust, eventually forcing the Federal Reserve (Fed) to tighten policies until it precipitates a recession. This is in disagreement with TS Lombard. They question whether the Fed’s current stance is overly restrictive, while Bob Elliott of Unlimited Funds suggests that rates may decrease in response to slowing growth. Eventually, the persistent inflation stemming from structural factors could prompt subsequent rate hikes driven by increased funding needs.

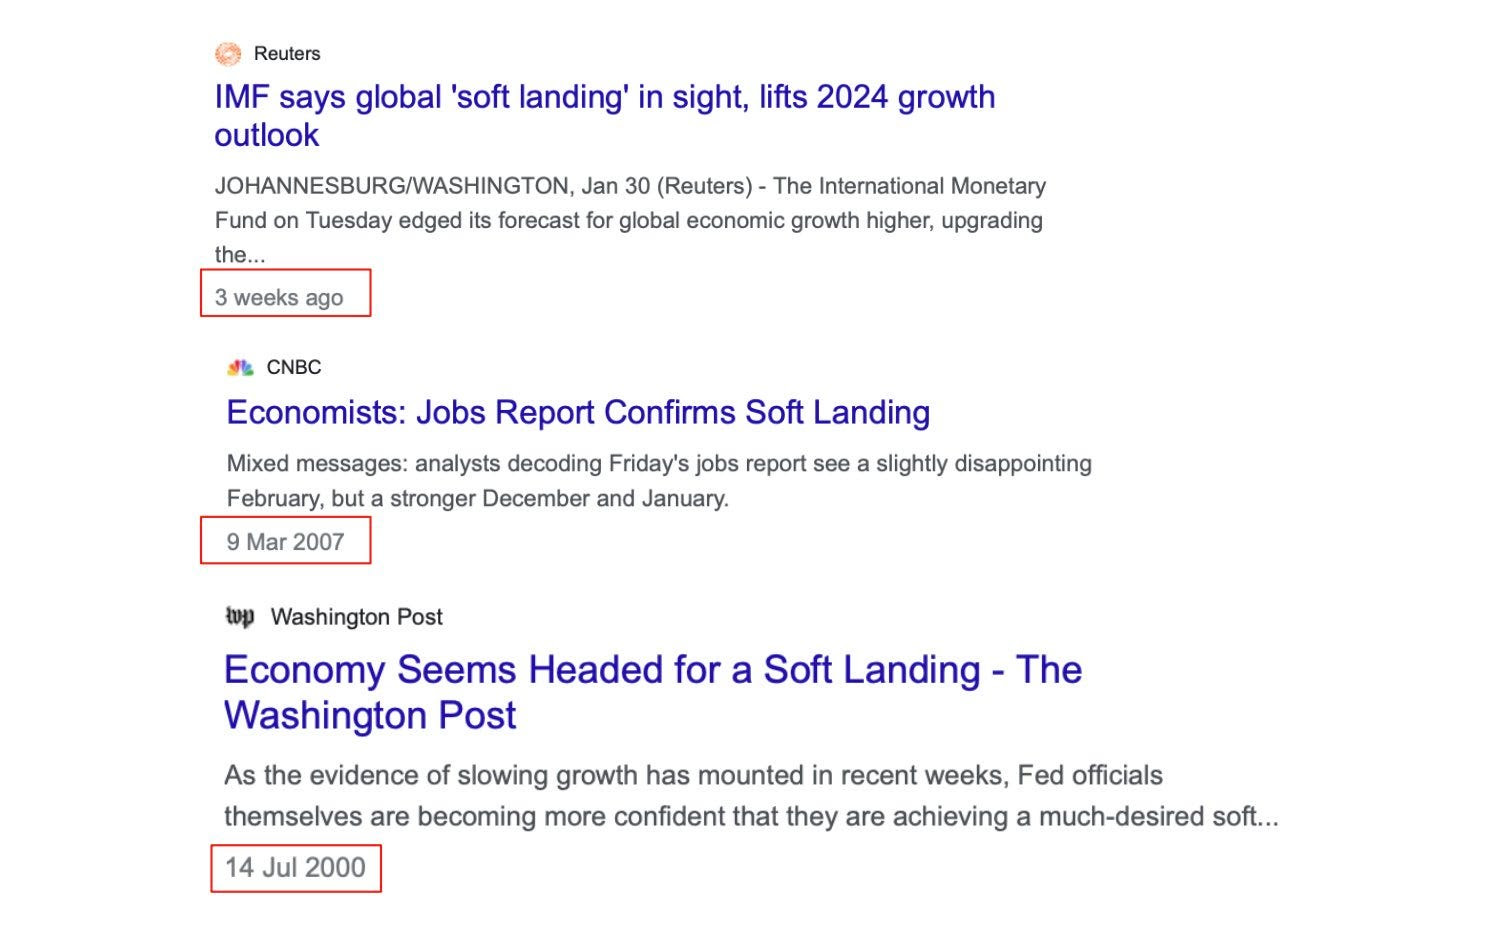
Graphic: Retrieved from Sven Henrich.

Traders must remain vigilant, adopting strategic approaches to hedge exuberance and so-called windows of non-strength. Should there be “a stronger catalyst than a telegraphed CPI print,” says Kris Sidial, then “both tails and skew are likely to perform well,” with any rally, given the short-volatility, likely to unsettle positioning, leading dealers to boost momentum and whipsaw. In other words, much lower or higher markets, coupled with more demand for puts or calls respectively, means dealers take on more short volatility risk, which they adjust for by repricing options higher and hedging with underlying asset sales (in the case of puts) or purchases (in the case of calls).

Graphic: Retrieved from Bank of America Corporation.

In conclusion, we remain mindful that it’s an election year, which could lead to heightened monetary and fiscal support in response to any weaknesses. While we maintain a positive outlook over the long term, we’re less optimistic in the short term.

This week, our attention is directed toward protecting our cash by rolling our remaining S&P 500 box spreads (acting as synthetic T-bills without impacting our buying power). We aim to secure these interest rates, keep a close watch on high-performing assets like silver, and replenish our long put skew (i.e., purchasing put spreads) in equities to hedge against potential vulnerabilities ahead. Following earnings announcements, we may resume engagement with companies such as Nvidia.

Graphic: Example of trade structuring. Retrieved from Physik Invest. This does not accurately represent this newsletter writer’s position. However, it is close. Note that one may own stock on top of this and view positions in aggregate.

If you’re wondering what’s up with the newsletter formatting over the past weeks, we are trying stuff. Let us know what you like and don’t like. Cheers, and have a good week! And, finally, if you can, share!

The cover photo was retrieved from a RidgeHaven Capital post on Seeking Alpha.

Categories
Commentary

Daily Brief For April 24, 2023

LOAD LEVELS ON TRADINGVIEW BY CLICKING HERE.

Short letter today. Got to catch a flight!

Last week, we discussed the recent response to the bank issues cutting risks for the S&P 500 (INDEX: SPX). Volatility and correlations fell as time passed, and this helped contain the market. Though last week’s options expiration (OpEx) may free markets up, we maintain that the SPX may stay contained longer before it weakens.

Graphic: Retrieved from SqueezeMetrics. “Monthly OpEx just shaved off nearly $300mm per point in SPX dealer gamma exposure. That means index liquidity has lost quite a bit of depth going into next week.”

Catalysts for weakness include falling earnings growth and a debt-ceiling crisis that’s driven T-bill yields lower from surging demand; a failure by Congress to raise the limit on how much the government can borrow may disrupt funding markets, WSJ reports.

Graphic: Retrieved from Bloomberg.

Let’s limit our expectations and focus on low- or zero-cost call structures (e.g., bull call ratio) monetized to finance longer-dated put structures (e.g., bear put vertical) while allocating a chunk of our portfolio to near-risk-free yield-harvesting structures (e.g., box spread), mainly if you are a portfolio margin trader.

As I explained to a subscriber over the weekend, for boxes, the greatest possible loss across a range of prices is negligible. Hence, buying power is unaffected in trading a box. Consequently, using portfolio margin and trading boxes, you have more buying power to allocate to other trades that are margin (and not debit) intensive, such as synthetic long stock (i.e., purchase ATM call and sell ATM put). Using options, among other derivatives, enables us to stack returns on each other.

Here’s one example.

We can trade box spreads expiring at the end of June. We buy the $4,000/$5,000 call spread for $22,365.00 and simultaneously buy the $5,000/$4,000 put spread for $76,620. This trade costs $98,985.00, and by lending this amount (on April 21, 2023), you will receive $1,015.00 upon maturity. Yes, you will have $99,000.00 cash tied up, but you should be able to use $99,000.00 in buying power in other trades if you have that portfolio margin component which is so important.

If this action-oriented letter is valuable to you, consider sharing it with others.

See you later!


About

Welcome to the Daily Brief by Physik Invest, a soon-to-launch research, consulting, trading, and asset management solutions provider. Learn about our origin story here, and consider subscribing for daily updates on the critical contexts that could lend to future market movement.

Separately, please don’t use this free letter as advice; all content is for informational purposes, and derivatives carry a substantial risk of loss. At this time, Capelj and Physik Invest, non-professional advisors, will never solicit others for capital or collect fees and disbursements. Separately, you may view this letter’s content calendar at this link.

Categories
Commentary

Daily Brief For April 18, 2023

LOAD LEVELS ON TRADINGVIEW BY CLICKING HERE.

Bank of America Corporation (NYSE: BAC) sees allocations to equities versus bonds falling. That’s amid recession fears. Per EPB, “the cyclical economy has just started to shed jobs today, and leading indicators signal the recession is likely underway.”

“To get advanced warning of recessions, you must look at the construction and manufacturing sectors, even though these two sectors are only 13% of the labor market,” EPB adds, noting traditional indicators’ weakening predictability is not so great to ignore the insight. “It’s clear that the composition of traditional leading indicators remains appropriate, and thus, the current resounding recessionary signal should not be ignored.”

BAC strategist Michael Hartnett said, though, that this “consensus lust for recession” must soon be satisfied. Otherwise, the “pain trade” would be even higher yields and stocks; the S&P 500 (INDEX: SPX) is enjoying an accelerated rally which Jefferies Financial Group (NYSE: JEF) strategists think portends a period of flatness, now, over the coming weeks …

Graphic: Retrieved from Jefferies Financial Group (NYSE: JEF) via The Market Ear.

… and through options expiration (OpEx), typically a poor performance period for the SPX.

Displaying
Graphic: Retrieved from Tier1Alpha. 

Beyond the uninspiring fundamentals, the positioning contexts are supportive. Recall our letters published earlier this year. If the market consolidated and failed to break substantially, then falling implied volatility (IVOL) and time passing would bolster markets and, potentially, help build a platform for a rally into mid-year. A check of fixed-strike and top-line measures of IVOL like the Cboe Volatility Index or VIX confirms options activities are keeping markets intact.

Graphic: Retrieved from Danny Kirsch of Piper Sandler (NYSE: PIPR). “SPX May $4,150.00 call volatility, the lack of realized volatility weighing on the market. Volatility low, not cheap.”

Beyond the rotation into shorter-dated options, just one of the factors exacerbating the decimation of longer-dated volatility, traders’ consensus is that markets won’t move a lot and/or they don’t need to hedge over longer time horizons; traders want punchier exposure to realized volatility (RVOL), and that they can get through shorter-dated options that have more gamma (i.e., exposure to changes in movement), not vega (i.e., exposure to changes in implied volatility).

Graphic: Retrieved from Goldman Sachs Group Inc (NYSE: GS) via Bloomberg.

Consequently, counterparties may be less dangerous to accelerating movement in either direction; hence, the growing likelihood of a period of flatness.

Graphic: Retrieved from SpotGamma.

“Despite the collapse in the 1-month realized volatility, we suspect most vol control funds have scaled into using their longer-term realized vols, which by design, lead to less aggressive rebalancing flows,” Tier1Alpha says. “For example, the 3-month rVol, which is currently driving our model, was essentially unchanged yesterday, which means volatility targets were maintained, and very little additional rebalancing had to occur. So even with the decline in the 1-month vol, overall risk exposure remained the same.”

With IVOL at a lower bound, the bullish impacts yielded by its compressing have largely played out. There may be more to be gained by movements higher in IVOL, in addition to the expiry of many call options this OpEx. By owning protection, particularly far from current prices, you are positioned to monetize on the market downside and non-linear repricings of volatility, as this letter has discussed in recent history. The caveat is that volatility can cluster and revert for longer; hence, your structure matters.

“I am concerned that VIX is underpricing the series of events that we know to expect over the coming weeks,” says Interactive Brokers Group Inc’s (NASDAQ: IBKR) Steve Sosnick. “While there is now an 88% implied likelihood of a 25 basis point hike, the likely path of any potential future hikes and assumed cuts should be more clarified at the meeting and in its aftermath.  And oh, has anyone ever heard the expression “sell in May and go away?”

Graphic: Retrieved from Interactive Brokers Group Inc (NASDAQ: IBKR).

With call skews far up meaningfully steep in some products, still-present low- and zero-cost call structures this letter has talked about in the past remain attractive. If the market falls apart, your costs are low, and losses are minimal. If markets move higher into a “more combustible” position, wherein “volatility is sticky into a rally,” you may monetize your call structures and roll some of those profits into bear put spreads (i.e., buy put and sell another at a lower strike). An alternative option is neutral. Own something such as a T-bill or box spread (i.e., buy call and sell put at one strike and sell call and buy put at another higher strike). Some boxes are yielding upwards of 5.4% as of yesterday’s close.

To end, though the short-dated options activity may prompt cascading events in market downturns, the main issue is the reduced use of longer-dated options; a supply and demand imbalance likely resolves itself with an implied volatility repricing of a great size where longer-dated options outperform those that are shorter-dated.
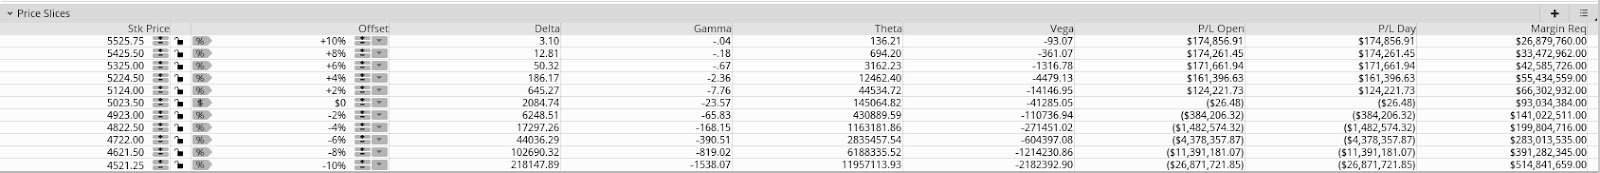
Our locking in of rates or using the profits of call structures to position for a potential IVOL repricing, particularly in the back half of the year when dealer positioning is less clear, buybacks are to fall off of a cliff, rates may fall, and the boost from short-covering has played its course, is an attractive proposition given the context.

Graphic: Retrieved from Bloomberg. “The S&P 500 (white line) is well above its levels from early March, while the yield on the 3m-2y spread remains in a deep inversion, signifying meaningful expectations of cuts in the months ahead.”

About

Welcome to the Daily Brief by Physik Invest, a soon-to-launch research, consulting, trading, and asset management solutions provider. Learn about our origin story here, and consider subscribing for daily updates on the critical contexts that could lend to future market movement.

Separately, please don’t use this free letter as advice; all content is for informational purposes, and derivatives carry a substantial risk of loss. At this time, Capelj and Physik Invest, non-professional advisors, will never solicit others for capital or collect fees and disbursements. Separately, you may view this letter’s content calendar at this link.

Categories
Commentary

Daily Brief For April 17, 2023

LOAD LEVELS ON TRADINGVIEW BY CLICKING HERE.

Inflation and employment rates remain high. Additionally, consumers show resilience, and earnings are strong. As a consequence, markets are back to pricing higher rates for longer. This is a pressure on bonds and stocks which appear “overvalued relative to coming bad news on both economic growth and corporate earnings.”

Graphic: Retrieved from Bloomberg via @Marcomadness2. Hedge funds are net short 2Y and SOFR futures.

Morgan Stanley (NYSE: MS) says stocks are at risk of a pullback, accordingly.

Graphic: Retrieved from Goldman Sachs Group Inc (NYSE: GS) via The Market Ear. The indexes have front-run the pause and pivot; Goldman Sachs Group Inc (NYSE: GS) data suggests a statistically significant disconnect between the Nasdaq 100 (INDEX: NDX) and yield.

With the percentage of stocks outperforming the S&P 500 the lowest on record, MS added, a slump in technology is the big risk if yields continue to rise; the bear market is not yet over. “If there is one thing that can throw cold water on the large mega-cap rally, it’s higher yields due to a Fed that can’t stop hiking.”

Graphic: Retrieved from Morgan Stanley (NYSE: MS) via Bloomberg.

Moody’s Corporation (NYSE: MCO) expects a “0.25-percentage point increase to the fed funds rate when the FOMC reconvenes in early May.” Following this hike, there is likely to be a pause at a 5.00-5.25% terminal rate for a few months.

Graphic: Retrieved from CME Group Inc’s (NASDAQ: CME) FedWatch Tool.

From a positioning perspective, Kai Volatility’s Cem Karsan stated that in the past 6-9 months, there has been a significant increase in the volume of options with zero days to expiration (0 DTE), which now accounts for 44% of the total volume. This increase in short-dated options volume has been accompanied by a similarly sized decrease in longer-dated options volume.

Further, the majority of trading activity in these short-dated options is split between hedging and directional trading, as well as yield harvesting via out-of-the-money (OTM) options sales. Though the short-dated activity may prompt cascading events in market downturns, the main issue is the reduced use of longer-dated options; a supply and demand imbalance likely resolves itself with an implied volatility repricing of great size where longer-dated options outperform those that are shorter-dated.

Traders can look to position for a potential IVOL repricing, particularly in the back half of the year when dealer positioning is less clear, buybacks are to fall off of a cliff, and the boost from short-covering has played its course.

Traders can continue to play near-term strength via call spread structures and use those profits to reduce the costs of owning longer-dated bets on markets or rates falling and IVOL increasing. If not interested in directional exposure, traders may allocate funds to T-bills and SPX box spreads which allow traders to create a loan structure similar to a T-bill. If savvy, one could find some structures yielding ~5.5%. Traders can also consider blending T-bills and boxes with directional exposure. This way, they can cut portfolio volatility but still have a bit of leverage potential. Please check out our past letters for trade structure specifics. Have a great day!

About

Welcome to the Daily Brief by Physik Invest, a soon-to-launch research, consulting, trading, and asset management solutions provider. Learn about our origin story here, and consider subscribing for daily updates on the critical contexts that could lend to future market movement.

Separately, please don’t use this free letter as advice; all content is for informational purposes, and derivatives carry a substantial risk of loss. At this time, Capelj and Physik Invest, non-professional advisors, will never solicit others for capital or collect fees and disbursements. Separately, you may view this letter’s content calendar at this link.

Categories
Commentary

Daily Brief For March 21, 2023

Physik Invest’s Daily Brief is read free by thousands of subscribers. Join this community to learn about the fundamental and technical drivers of markets.

Graphic updated 7:00 AM ET. Sentiment Risk-On if expected /MES open is above the prior day’s range. /MES levels are derived from the profile graphic at the bottom of this letter. Click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) with the latter calculated based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. The lower the GEX, the more (expected) volatility. Click to learn the implications of volatility, direction, and moneyness. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. The CBOE VIX Volatility Index (INDEX: VVIX) reflects the attractiveness of owning volatility. UMBS prices via MNDClick here for the economic calendar.

Administrative

Not all doom and gloom. Make sure to read to the end!

Fundamental

In the Daily Brief for 3/20, we summarized the financial industry and policymaker responses that would turn asset fire sales into managed, orderly asset sales. 

Graphic: Retrieved from Sergei Perfiliev.

The net result of the intervention would be a reduction in credit creation, a tightening of financial conditions, as well as a slowing of the economy and inflation while, potentially, setting “a dangerous precedent that simply encourage[s] future irresponsible behavior” (e.g., risky lending/borrowing), the House Freedom Caucus put eloquently. Basically, the fear is in policymakers underwriting the losses of prevailing carry-type strategies and setting the stage for an even bigger unwind or so-called “Minsky moment,” the “sudden crash of markets and economies that are hooked on debt,” Bloomberg reports

The likes of Elon Musk express fear, too!

A systemic credit event is among strategists’ biggest fear, indeed. A Bank of America Corporation (NYSE: BAC) survey shows a credit event happening on the heels of a US shadow banking, corporate debt, and developed-market real-estate collapse. Recall this letter writer’s conversation with Simplify Asset Management’s Michael Green who said he sees “cracks in bubbles like commercial real estate” already appearing, too.
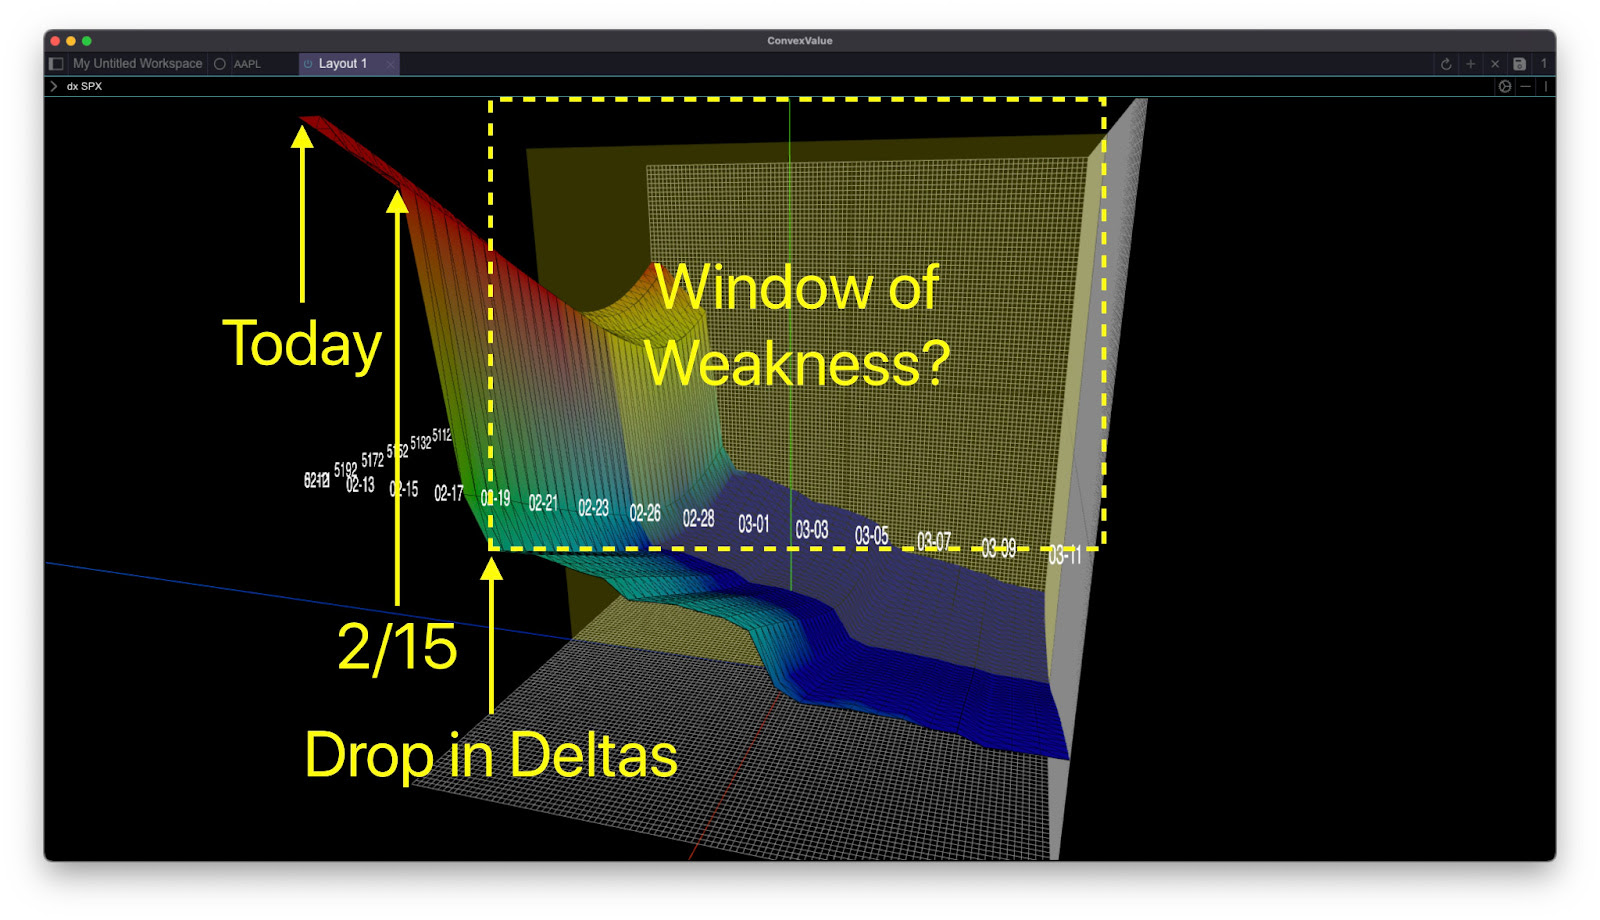
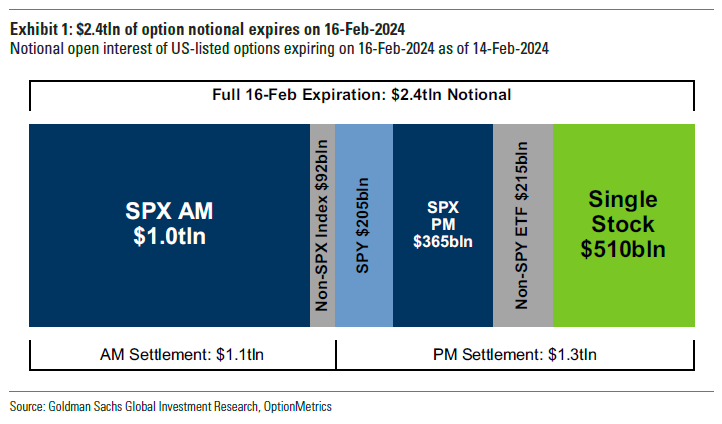
Bloomberg adds that JPMorgan Chase & Co (NYSE: JPM) strategists think the inverted yield curve signals recession and the stocks are likely nearing their high point.

Graphic: Retrieved from Callum Thomas’ Weekly S&P 500 ChartStorm.

JPM adds that market lows won’t occur until interest rate cuts ensue.

Graphic: Retrieved from BNP Paribas ADR (OTC: BNPQY).

Recall 3/20’s letter citing BAC research that finds selling markets on the last Fed rate hike is a good strategy. The “Minsky moment” comment/fear has others at JPM adding that investors should sell into relief bounces.

Graphic: Retrieved from Bank of American Corporation (NYSE: BAC) via The Market Ear.

Most participants foresee rates continuing to rise by at least 25 basis points, per the CME Group Inc’s (NASDAQ: CME) FedWatch Tool. Following Wednesday’s (expected) hike, the path forward appears uncertain. Yesterday, the terminal/peak rate was at 4.75-5.00%. Today, the peak has shifted higher to 5.00-5.25%.

Graphic: Retrieved from CME Group Inc (NASDAQ: CME).

Financials look ready to fall off a cliff, to add. If they do, the whole market likely goes.

Graphic: Retrieved from Callum Thomas’ Weekly S&P 500 ChartStorm.

Positioning

We keep referring back to our Daily Briefs published last week (e.g., 3/13 and 3/14). In those letters, we talked about the growing concern about markets enduring some exogenous shocks. 

We opted to take the less extreme side since policymakers’ response was likely to stem (or push into the future) turmoil. Additionally, with participants easing up on their long-equity exposure, equity markets were likely to stay contained, relative to bond markets where the lack of liquidity is an issue, some believe. Anyways, following important events including inflation updates (i.e., CPI) and derivatives expiries, short bursts of strength (particularly in some of the previously depressed products such as the Nasdaq 100 or NDX, as explained 3/17) were likely to ensue heading into the end of this month and next month. Additionally, certain rates trades via options we set forth on 3/14 were ripe for monetization, too.

Rotating into a money market or T-bill fund or box spreads, while allocating some remaining cash to leverage potential by way of some call options structures, appeared attractive. While the T-bill or box spread exposures did not budge much, call options structures as proposed on 3/14 worked (and are likely to continue to work) rather well. The monetization of the rate structures discussed on 3/14 was timely, also.

The potential for coming events including the Federal Reserve’s (Fed) interest rate decision on Wednesday 3/22 to assuage participants’ fears of slowing may, accordingly, prompt fears of missing out on the upside, Bloomberg reports. A response may be FOMO-type demand for call options exposures, coupled with CTAs further “raising their equity exposure” on trend signals and lower volatility, boosting markets into a “more combustible” state as explained on 2/17. This fear of missing out is visible in options volatility skew; traders are hedging those tail outcomes.

Technical

As of 7:00 AM ET, Tuesday’s regular session (9:30 AM – 4:00 PM ET), in the S&P 500, is likely to open in the upper part of a positively skewed overnight inventory, outside of the prior day’s range, suggesting a potential for immediate directional opportunity.

The S&P 500 pivot for today is $4,004.75. 

Key levels to the upside include $4,026.75, $4,037.00, and $4,045.25.

Key levels to the downside include $3,994.25, $3,977.00, and $3,959.25.

Disclaimer: Click here to load the updated key levels via the web-based TradingView platform. New links are produced daily. Quoted levels likely hold barring an exogenous development.

Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures.

Definitions

Volume Areas: Markets will build on areas of high-volume (HVNodes). Should the market trend for a period of time, this will be identified by a low-volume area (LVNodes). The LVNodes denote directional conviction and ought to offer support on any test.

If participants auction and find acceptance in an area of a prior LVNode, then future discovery ought to be volatile and quick as participants look to the nearest HVNodes for more favorable entry or exit.

POCs: Areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

Options Expiration (OPEX): Reduction in dealer Gamma exposure. There may be an increase in volatility after the removal of large options positions and associated hedging.

Volume-Weighted Average Prices (VWAPs): A metric highly regarded by chief investment officers, among other participants, for quality of trade. Additionally, liquidity algorithms are benchmarked and programmed to buy and sell around VWAPs.


About

The author, Renato Leonard Capelj, spends the bulk of his time at Physik Invest, an entity through which he invests and publishes free daily analyses to thousands of subscribers. The analyses offer him and his subscribers a way to stay on the right side of the market. 

Separately, Capelj is an accredited journalist with past works including interviews with investor Kevin O’Leary, ARK Invest’s Catherine Wood, FTX’s Sam Bankman-Fried, North Dakota Governor Doug Burgum, Lithuania’s Minister of Economy and Innovation Aušrinė Armonaitė, former Cisco chairman and CEO John Chambers, and persons at the Clinton Global Initiative.

Connect

Direct queries to renato@physikinvest.com. Find Physik Invest on TwitterLinkedInFacebook, and Instagram. Find Capelj on TwitterLinkedIn, and Instagram. Only follow the verified profiles.

Calendar

You may view this letter’s content calendar at this link.

Disclaimer

Do not construe this newsletter as advice. All content is for informational purposes. Capelj and Physik Invest manage their own capital and will not solicit others for it.

Categories
Commentary

Daily Brief For March 14, 2023

Physik Invest’s Daily Brief is read free by thousands of subscribers. Join this community to learn about the fundamental and technical drivers of markets.

Graphic updated 6:30 AM ET. Sentiment Neutral if expected /MES open is inside of the prior day’s range. /MES levels are derived from the profile graphic at the bottom of this letter. Click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) with the latter calculated based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. The lower the GEX, the more (expected) volatility. Click to learn the implications of volatility, direction, and moneyness. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. The CBOE VIX Volatility Index (INDEX: VVIX) reflects the attractiveness of owning volatility. UMBS prices via MNDClick here for the economic calendar.

Administrative

A long(er) letter, today. Through the end-of-this week, newsletters may be shorter due to the letter writer’s commitments. Take care!

Fundamental

Yesterday’s letter focused on the SVB Financial Group (NASDAQ: SIVB) failure, albeit with an optimistic tone. In short, the bank could not make good on fast accelerating withdrawals. Read more here.

According to one TechCrunch article, the likes of Founders Fund “reportedly advised their portfolio companies … to withdraw their money, … [and], if everybody is telling each other that SVB is in trouble, that will be a challenge,” as it was.

Graphic: Retrieved from @Citrini7. In the worst-case scenario, it was likely that uninsured depositors at SIVB would have received $0.80 on each dollar barring a bailout.

Authorities later put forth emergency measures guaranteeing all deposits. The effort shored up confidence in the banking system and markets strengthened, though some regional names such as First Republic Bank (NYSE: FRC) continued trading weak. In FRC’s case, the Federal Reserve’s (Fed) new bailout facility does not help. As former Fed trader Joseph Wang explains, “you need Treasuries and Agency MBS to tap the facility, and [FRC] barely owns any.”

Graphic: Retrieved via Joseph Wang.

Anyways, as yesterday’s letter briefly mentioned, expectations on the path of Fed Funds shifted. Traders put the terminal/peak rate at 5.00-5.25%, down from 5.50-5.75%, while pricing cuts after spring. Previously, no cuts were expected in 2023.

Graphic: Retrieved from CME Group Inc’s (NASDAQ: CME) FedWatch Tool.

Some Treasury yields fell spectacularly, too, …

Graphic: Retrieved from Bloomberg.

… on par with those declines experienced amidst major crises, at least in the case of the 2-year.

Graphic: Retrieved from Bloomberg.

Measures of US Treasury yield volatility implied by options (i.e., bets or hedges on or against market movement) adjusted higher, accordingly. This is often a harbinger of equity market volatility.

Graphic: Merrill Lynch Option Volatility Estimate retrieved from TradingView

Call options on the three-month Secured Overnight Financing Rate (FUTURE: SOFR) future (i.e., bets on interest rates falling in the future) paid handsomely.

For instance, bull call spreads that expire in December 2023 (e.g., BUY +1 VERTICAL /SR3Z23:XCME 1/2500 DEC 23 /SR3Z23:XCME 96/97 CALL @.0375) increased in value by about 650.00% to $0.33 (i.e., $750.00 per contract).

Graphic: Retrieved via TradingView. Three-month SOFR Future (December 2023). When SOFR is at a lower (higher) number, the market is pricing an increase (decrease) in interest rates. Participants put the December 2023 SOFR rate at 100-96.145 = 3.855%.

In the equity space, some readers may have caught some commentary on spot-vol beta in the VIX complex strengthening like we have not seen in a while, a nod to the harbinger of equity market volatility remark a few paragraphs higher.

Recommended Readings:

  • Read: The Ambrus Group’s Kris Sidial on two major risks investors should watch out for in 2023. In short, volatility’s sensitivity to underlying prices (spot-vol beta) was low, and Sidial cast blame, in part, on commodity trading advisors and strong volatility supply.
  • Read: Simplify Asset Management’s Michael Green on using option and bond overlays to hedge big uncertainties facing markets. Following 2022, investors swapped poor-performing long-dated volatility exposures for ones with bounded risk and less time to expiry, hence the increase in 0 DTE trading.
Graphic: Retrieved from Piper Sandler’s (NYSE: PIPR) Danny Kirsch.

This spot-vol beta remark suggests that (at least some of) the volatility in rates, as well as certain small pockets of the equity and crypto market, manifested demand for crash protection in the S&P 500, “which feeds back into VIX,” one explanation put well.

Graphic: Retrieved from Piper Sandler’s (NYSE: PIPR) Danny Kirsch. “[Last] week finally got a bit of explosiveness in VIX as fixed strike volatility got bid. This is VIX generic front month future and move in SPX. Last time it really “paid” to have VIX upside was Jan of 2022 (point in upper left corner).”

Notwithstanding, for these options to keep their value and continue to perform well, realized volatility (RVOL) must pick up substantially, which is not likely.

Unlimited’s Bob Elliott comments: “the bond market is pricing a broad-based credit crunch, … [and though] it’s not crazy for the Fed to slow down here given the current uncertainty,” odds are financial problems are contained and the Fed moves forward with its mission to get (and keep) inflation down.

Graphic: Retrieved from Fabian Wintersberger. Just as the “monetary expansion supported the rise in equity and bond prices in January.”

Consequently, “the pricing of Dec23s and 5yr BEIs makes no sense,” Elliott adds. This means the example SOFR trade above is/was ripe for some monetization, and equity volatility must be dealt with carefully (i.e., price movements must be higher than they are now which would be difficult given that authorities/Fed do not want liquidations).

In support of siding with the less extreme take, we paraphrase Kai Volatility’s Cem Karsan who says that for years prior to the 2007-2008 turmoil, macro tourists were calling for a crash.

For markets to crumble, there would have to be an exogenous event far greater in implications than what just transpired with SIVB over the weekend. With odds that such turmoil doesn’t happen soon, coupled with participants easing up on their long-equity exposure (i.e., selling stock and not needing to hedge, hence the statement that owning equity volatility must be dealt with carefully), RVOL is likely to stay contained. That’s not to say that this volatility observed in the rates market can’t persist. It’s also not to say that markets can’t continue to trade lower (in fact, with interest rates rising and processes like quantitative tightening challenging bank liquidity, there is less incentive for investors to reside in lower-yielding equities). It just means that, barring some exogenous event, the market remains intact.
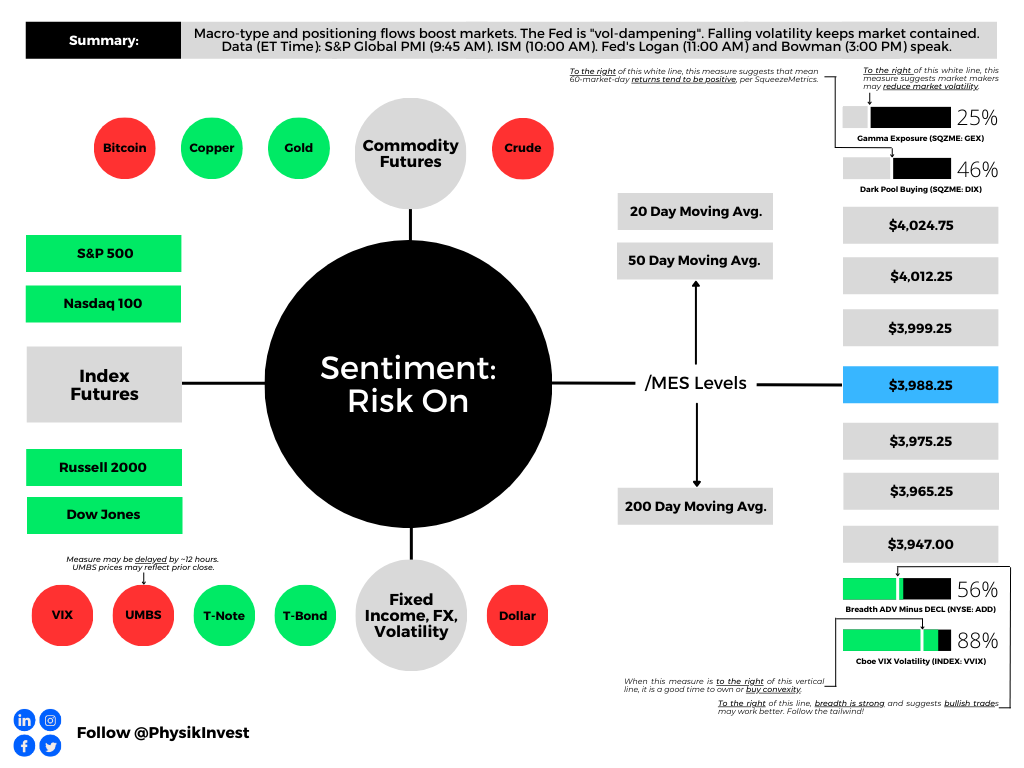
Graphic: Retrieved from Jack Farley. “Silicon Valley Bank owns >$80 Billion of Mortgage-Backed Securities (MBS), a market that is ‘more prone to bouts of volatility’ because ‘small investors & leveraged funds have become the main buyers’ as the Fed & banks step away from market, according to Dec 2022 BIS report.”

Positioning

Following important events like the release of the Consumer Price Index (CPI) today, the compression of implied volatility or IVOL, coupled with the nearing of big options expirations (OpEx), sets the market up for potential short bursts of strength heading into the end of the month and next month.

Graphic: Retrieved from Bloomberg. Inflation has been well within forecasts.

A quick comparison of the Russell 2000 (INDEX: RUT) and Nasdaq 100 (INDEX: NDX) suggests this options-induced strength may help keep the recent re-grossing theme intact. The compression of wound IVOL and passage of OpEx, coupled with the still-live re-grossing theme, may put a floor under equities.

Graphic: Retrieved from TradingView. Orange = RUT. Candles = NDX. Note the weakness in RUT. Note the strength of the Nasdaq relative to the Russell.

To play, one could place a portion of their cash in money market funds or T-bill ETFs or box spreads, for instance, while allocating another portion to leverage potential by way of some call options structures that use one or more short options to help bring down the cost of a long option that is closer to current market prices (e.g., a bull call spread or short ratio call spread). To note, based on options prices as of this writing, it may be too early to enter call structures (i.e., too expensive given the context).

 Technical

As of 6:30 AM ET, Tuesday’s regular session (9:30 AM – 4:00 PM ET), in the S&P 500, is likely to open in the middle part of a balanced overnight inventory, inside of the prior day’s range, suggesting a limited potential for immediate directional opportunity.

The S&P 500 pivot for today is $3,904.25. 

Key levels to the upside include $3,921.75, $3,945.00, and $3,970.75.

Key levels to the downside include $3,884.75, $3,868.25, and $3,847.25.

Disclaimer: Click here to load the updated key levels via the web-based TradingView platform. New links are produced daily. Quoted levels likely hold barring an exogenous development.

Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures.

Definitions

Volume Areas: Markets will build on areas of high-volume (HVNodes). Should the market trend for a period of time, this will be identified by a low-volume area (LVNodes). The LVNodes denote directional conviction and ought to offer support on any test.

If participants auction and find acceptance in an area of a prior LVNode, then future discovery ought to be volatile and quick as participants look to the nearest HVNodes for more favorable entry or exit.

POCs: Areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

Volume-Weighted Average Prices (VWAPs): A metric highly regarded by chief investment officers, among other participants, for quality of trade. Additionally, liquidity algorithms are benchmarked and programmed to buy and sell around VWAPs.


About

The author, Renato Leonard Capelj, spends the bulk of his time at Physik Invest, an entity through which he invests and publishes free daily analyses to thousands of subscribers. The analyses offer him and his subscribers a way to stay on the right side of the market. 

Separately, Capelj is an accredited journalist with past works including interviews with investor Kevin O’Leary, ARK Invest’s Catherine Wood, FTX’s Sam Bankman-Fried, North Dakota Governor Doug Burgum, Lithuania’s Minister of Economy and Innovation Aušrinė Armonaitė, former Cisco chairman and CEO John Chambers, and persons at the Clinton Global Initiative.

Connect

Direct queries to renato@physikinvest.com. Find Physik Invest on TwitterLinkedInFacebook, and Instagram. Find Capelj on TwitterLinkedIn, and Instagram. Only follow the verified profiles.

Calendar

You may view this letter’s content calendar at this link.

Disclaimer

Do not construe this newsletter as advice. All content is for informational purposes. Capelj and Physik Invest manage their own capital and will not solicit others for it.

Categories
Commentary

Daily Brief For March 3, 2023

Physik Invest’s Daily Brief is read free by thousands of subscribers. Join this community to learn about the fundamental and technical drivers of markets.

Graphic updated 7:00 AM ET. Sentiment Risk-On if expected /MES open is above the prior day’s range. /MES levels are derived from the profile graphic at the bottom of this letter. Click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) with the latter calculated based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. The lower the GEX, the more (expected) volatility. Click to learn the implications of volatility, direction, and moneyness. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. The CBOE VIX Volatility Index (INDEX: VVIX) reflects the attractiveness of owning volatility. UMBS prices via MNDClick here for the economic calendar.

Administrative

Lots of content today but a bit rushed at the desk. If anything is unclear, we will clarify it in the coming sessions. Have a great weekend! – Renato

Fundamental

Physik Invest’s Daily Brief for March 2 talked about balancing the implications of still-hot inflation and an economy on solid footing. Basically, the probability the economy is in a recession is lower than it was at the end of ‘22. For the probabilities to change markedly, there would have to be a big increase in unemployment, for one.

According to a blog by Unlimited’s Bruce McNevin, if the unemployment rate rises by about 1%, recession odds go up by 29%. If the non-farm payroll employment falls by about 2% or 3 million jobs, recession odds increase by about 74%. After a year or so of tightening, unemployment measures are finally beginning to pick up.

Policymakers, per recent remarks, maintain that more needs to be done, however. For instance, the Federal Reserve’s (Fed) Raphael Bostic, who generally carries an easier stance on monetary policy, mulled whether the Fed should raise interest rates beyond the 5.00-5.25% terminal rate consensus he previously endorsed. This commentary, coupled with newly released economic data, has sent yields surging at the front end. 
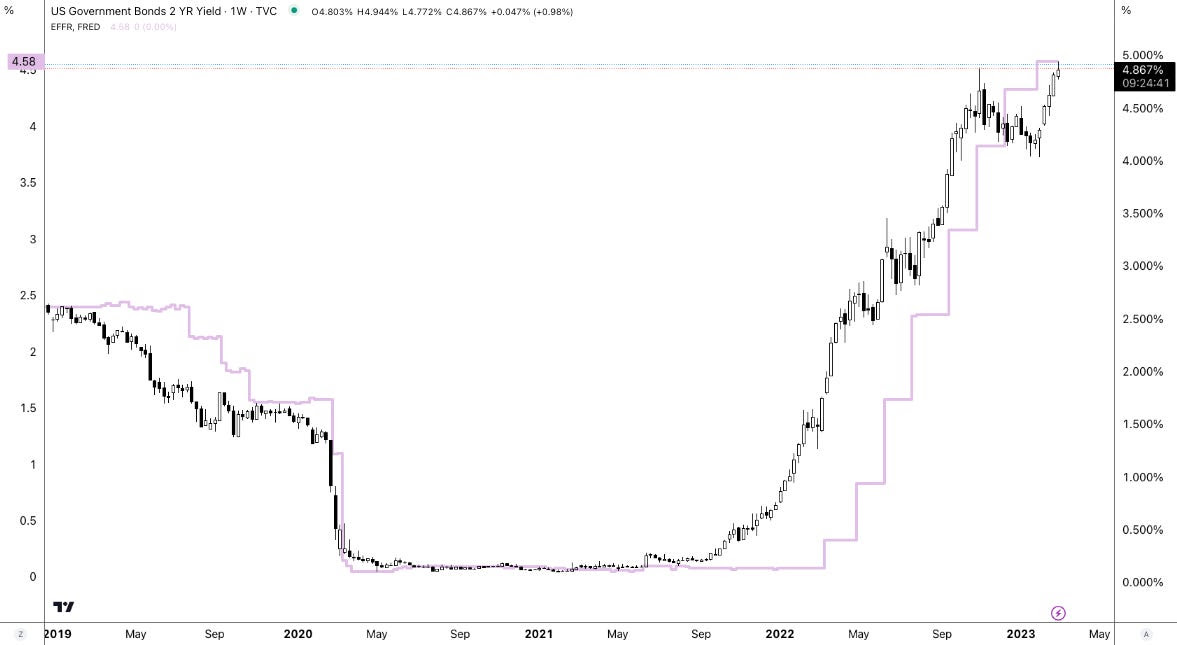
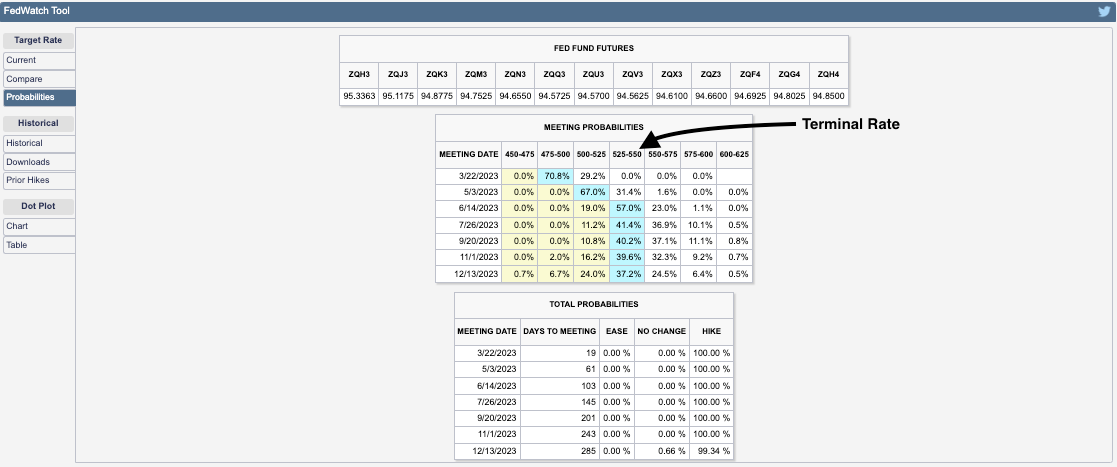
Graphic: Retrieved from TradingView.

Traders are wildly repricing their terminal rate expectations this week. The terminal rate over the past few days has gone up from 5.25-5.50% to 5.50-5.75%, and back down to 5.25-5.50%.

Graphic: Retrieved from CME Group Inc (NASDAQ: CME).

Positioning

Stocks and bonds performed poorly. Commodity hedges are uninspiring also in that they do not hedge against (rising odds of) recession, per the Daily Brief for March 1

In navigating this precarious environment, this letter has put forward a few trade ideas including the sale of call options structures to finance put options structures, after the mid-February monthly options expiration (OpEx). Though measures suggest “we can [still] get cheap exposure to convexity while a lot of people are worried,” the location for similar (short call, long put) trades is not optimal. Rather, trades including building your own structured note, now catching the attention of some traders online, appear attractive now with T-bill rates surging.

Graphic: Retrieved from Bloomberg.

Such trades reduce portfolio volatility and downside while providing upside exposure comparable to poorly performing traditional portfolio constructions like 60/40.

As an example, per IPS Strategic Capital’s Pat Hennessy, with $1,000,000 to invest and rates at ~5% (i.e., $50,000 is 5% of $1,000,000), one could buy 1000 USTs or S&P 500 (INDEX: SPX) Box Spreads which will have a value of $1 million at maturity for the price of $950,000.

With $50,000 left in cash, one can use options for leveraged exposure to an asset of their choosing, Hennessy explained. Should these options expire worthless, the $50,000 gain from USTs, at maturity, provides “a full return of principal.”

For traders who are focused on short(er)-term movements, one could allocate the cash remaining toward structures that buy and sell call options over very short time horizons (e.g., 0 DTE).

Knowing that the absence of range expansion to the downside, positioning flows may build a platform for the market to rally, one could lean into structures like fixed-width call option butterflies.

For instance, yesterday, Nasdaq 100 (INDEX: NDX) call option butterflies expanded in value ~10 times (i.e., $5 → $50). An example 0 DTE trade is the BUTTERFLY NDX 100 (Weeklys) 2 MAR 23 12000/12100/12200 CALL. Such trade could have been bought near ~$5.00 in debit and, later, sold for much bigger credits (e.g., ~$40.00).

Such trade fits and plays on the narrative described in Physik Invest’s Daily Brief for February 24. That particular letter detailed Bank of America Corporation’s (NYSE: BAC) finding that “volume is uniquely skewed towards the ask early in the day but towards the bid later in the day” for these highly traded ultra-short-dated options.

Graphic: Retrieved from Goldman Sachs Group Inc (NYSE: GS) via Bloomberg. 

Even options insight and data provider SqueezeMetrics agrees: “Buy 0 DTE call.” The typical “day doesn’t end above straddle b/e, but call makes money,” SqueezeMetrics explained. “Dealer and call-buyer both profit. Gap down, repeat.”

Anyways, back to the bigger trends impacted by liquidity coming off the table and increased competition between equities and fixed income.

Graphic: Via Physik Invest. Net Liquidity = Fed Balance Sheet – Treasury General Account – Reverse Repo.

As this letter put forth in the past, if the “market consolidates and doesn’t break,” as we see, the delta buy-back with respect to dropping implied volatility (IVOL) or vanna and buy-back with respect to the passage of time or charm could build a platform for a FOMO-driven call buying rally that ends in a blow-off. 

Graphic: Retrieved from Piper Sandler’s (NYSE: PIPR) Danny Kirsch. Short volatility and short stocks was attractive to trade. As your letter writer put in a recent SpotGamma note: “With IV at already low levels, the bullish impact of it falling further is weak, hence the SPX trending lower all the while IV measures (e.g., VIX term structure) have shifted markedly lower since last week. If IV was at a higher starting point, its falling would work to keep the market in a far more positive/bullish stance.”

Per data by SpotGamma, another options insight and data provider your letter writer used to write for and highly recommends checking out, call buying, particularly over short time horizons, was often tied to market rallies. 

Graphic: Retrieved from SpotGamma via Bloomberg.

“0DTE does not seem to be associated with betting on a large downside movement. Large downside market volatility appears to be driven by larger, longer-dated S&P volume,” SpotGamma founder Brent Kochuba said in the Bloomberg article. “Where 0DTE is currently most impactful is where it seems 0DTE calls are being used to ‘buy the dips’ after large declines. In a way this suppresses volatility.”

Anyways, the signs of a “more combustible situation” would likely show when “volatility is sticky into a rally,” explained Kai Volatiity’s Cem Karsan. To gauge combustibility, look to the Daily Brief for February 17.

Technical

As of 6:50 AM ET, Friday’s regular session (9:30 AM – 4:00 PM ET), in the S&P 500, is likely to open in the upper part of a positively skewed overnight inventory, outside of the prior day’s range, suggesting a potential for immediate directional opportunity.

The S&P 500 pivot for today is $3,988.25. 

Key levels to the upside include $3,999.25, $4,012.25, and $4,024.75.

Key levels to the downside include $3,975.25, $3,965.25, and $3,947.00.

Disclaimer: Click here to load the updated key levels via the web-based TradingView platform. New links are produced daily. Quoted levels likely hold barring an exogenous development.

Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures.

Definitions

Volume Areas: Markets will build on areas of high-volume (HVNodes). Should the market trend for a period of time, this will be identified by a low-volume area (LVNodes). The LVNodes denote directional conviction and ought to offer support on any test.

If participants auction and find acceptance in an area of a prior LVNode, then future discovery ought to be volatile and quick as participants look to the nearest HVNodes for more favorable entry or exit.

Vanna: The rate at which the Delta of an option changes with respect to implied volatility.

Charm: The rate at which the Delta of an option changes with respect to time.

POCs: Areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

MCPOCs: Denote areas where two-sided trade was most prevalent over numerous sessions. Participants will respond to future tests of value as they offer favorable entry and exit.

Options Expiration (OPEX): Reduction in dealer Gamma exposure. Often, there is an increase in volatility after the removal of large options positions and associated hedging.

Options: Options offer an efficient way to gain directional exposure.

If an option buyer was short (long) stock, he or she could buy a call (put) to hedge upside (downside) exposure. Additionally, one can spread, or buy (+) and sell (-) options together, strategically.

Commonly discussed spreads include credit, debit, ratio, back, and calendar.

  • Credit: Sell -1 option closer to the money. Buy +1 option farther out of the money.
  • Debit: Buy +1 option closer to the money. Sell -1 option farther out of the money.
  • Ratio: Buy +1 option closer to the money. Sell -2 options farther out of the money. 
  • Back: Sell -1 option closer to the money. Buy +2 options farther out of the money.
  • Calendar: Sell -1 option. Buy +1 option farther out in time, at the same strike.

Typically, if bullish (bearish), sell at-the-money put (call) credit spread and/or buy a call (put) debit/ratio spread structured around the target price. Alternatively, if the expected directional move is great (small), opt for a back spread (calendar spread). Also, if credit spread, capture 50-75% of the premium collected. If debit spread, capture 2-300% of the premium paid.

Be cognizant of risk exposure to the direction (Delta), movement (Gamma), time (Theta), and volatility (Vega). 

  • Negative (positive) Delta = synthetic short (long).
  • Negative (positive) Gamma = movement hurts (helps).
  • Negative (positive) Theta = time decay hurts (helps).
  • Negative (positive) Vega = volatility hurts (helps).

About

The author, Renato Leonard Capelj, spends the bulk of his time at Physik Invest, an entity through which he invests and publishes free daily analyses to thousands of subscribers. The analyses offer him and his subscribers a way to stay on the right side of the market. 

Separately, Capelj is an accredited journalist with past works including interviews with investor Kevin O’Leary, ARK Invest’s Catherine Wood, FTX’s Sam Bankman-Fried, North Dakota Governor Doug Burgum, Lithuania’s Minister of Economy and Innovation Aušrinė Armonaitė, former Cisco chairman and CEO John Chambers, and persons at the Clinton Global Initiative.

Connect

Direct queries to renato@physikinvest.com. Find Physik Invest on TwitterLinkedInFacebook, and Instagram. Find Capelj on TwitterLinkedIn, and Instagram. Only follow the verified profiles.

Calendar

You may view this letter’s content calendar at this link.

Disclaimer

Do not construe this newsletter as advice. All content is for informational purposes. Capelj and Physik Invest manage their own capital and will not solicit others for it.