Categories
Commentary

Daily Brief For November 10, 2021

What Happened

Equity index futures sideways, overnight, on powerful derivative market forces, alongside participants’ aims to base ahead of added clarity on the economic outlook.

Ahead is data on inflation and jobless claims (8:30 AM ET), wholesale inventories (10:00 AM ET), and the monthly budget statement (2:00 PM ET).
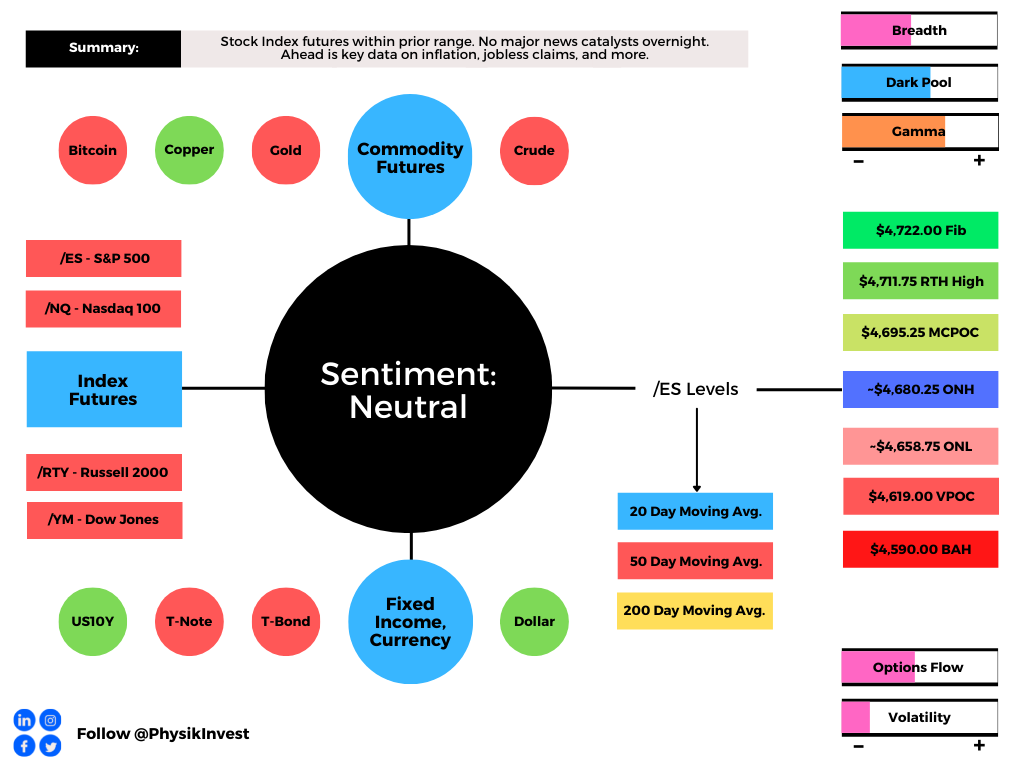
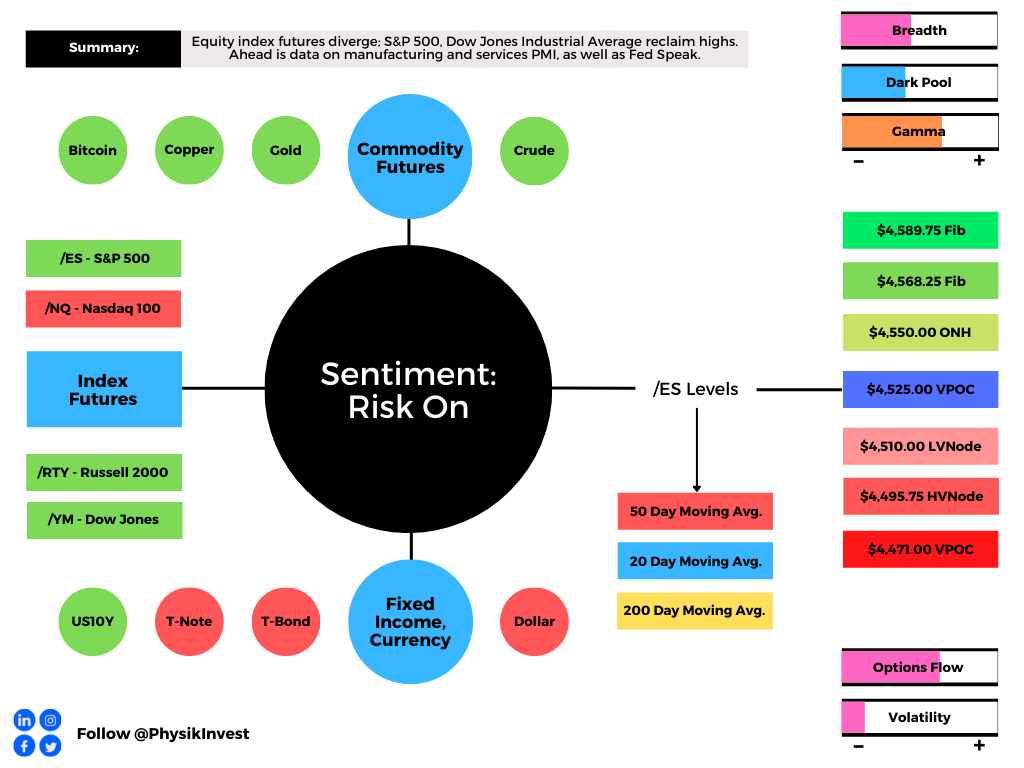
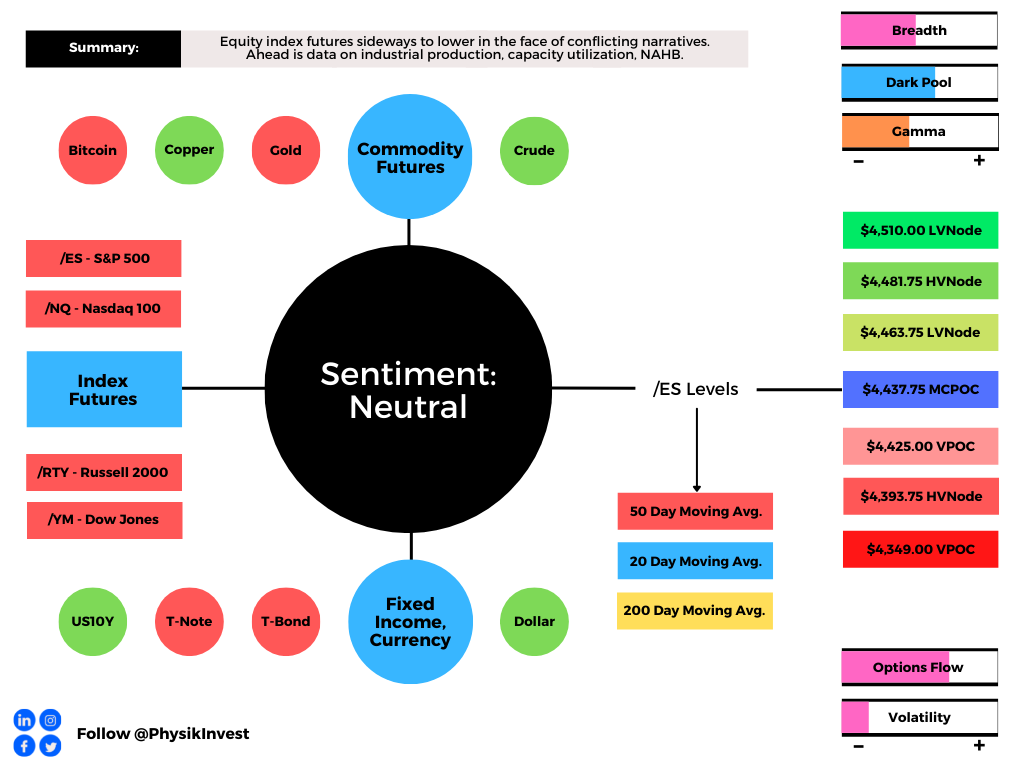
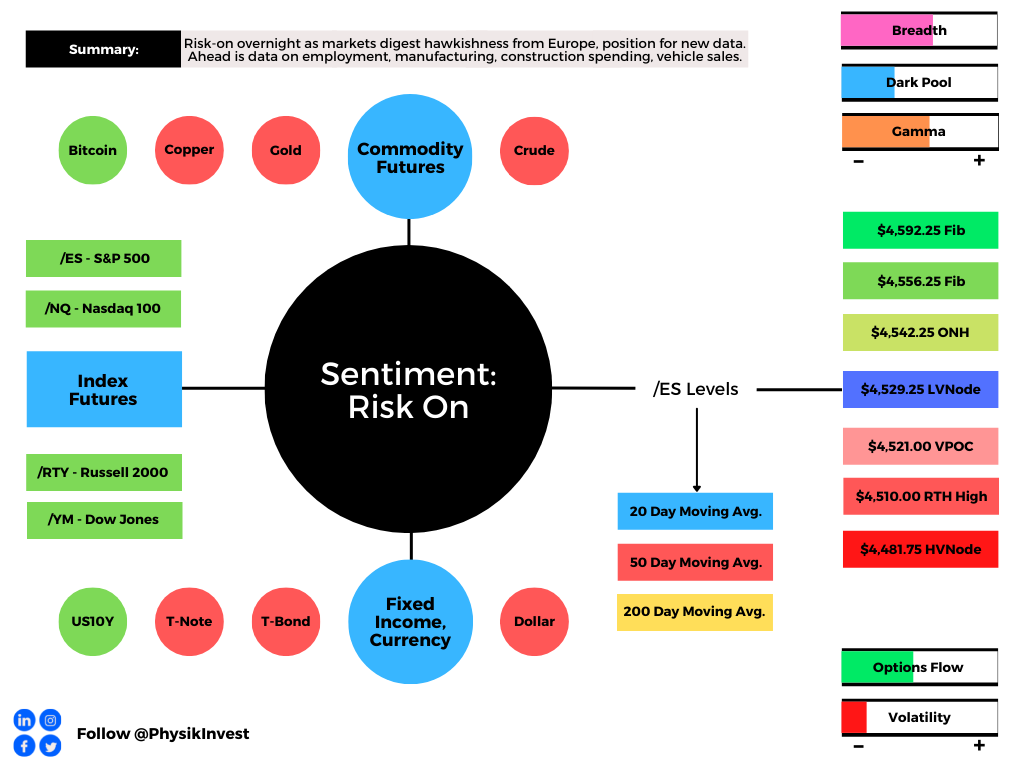
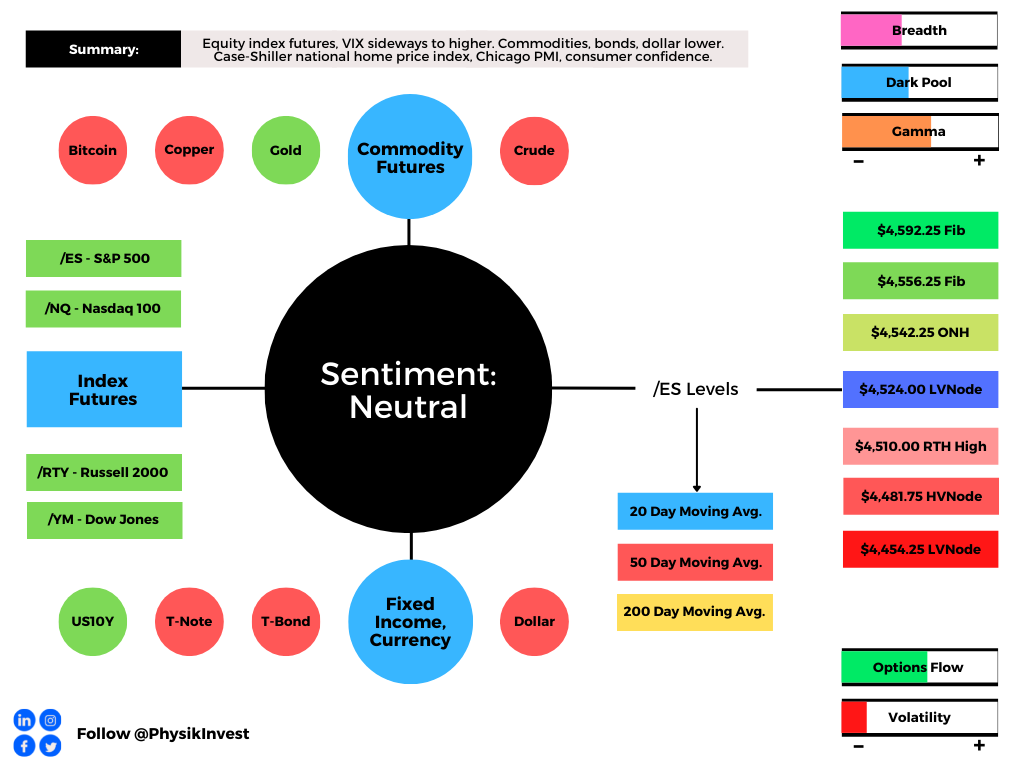
Graphic updated 5:30 AM ET. Sentiment Neutral if expected /ES open is inside of the prior day’s range. /ES levels are derived from the profile graphic at the bottom of the following section. Levels may have changed since initially quoted; click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. Learn the implications of volatility, direction, and moneyness. SHIFT data used for S&P 500 (INDEX: SPX) options activity. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect

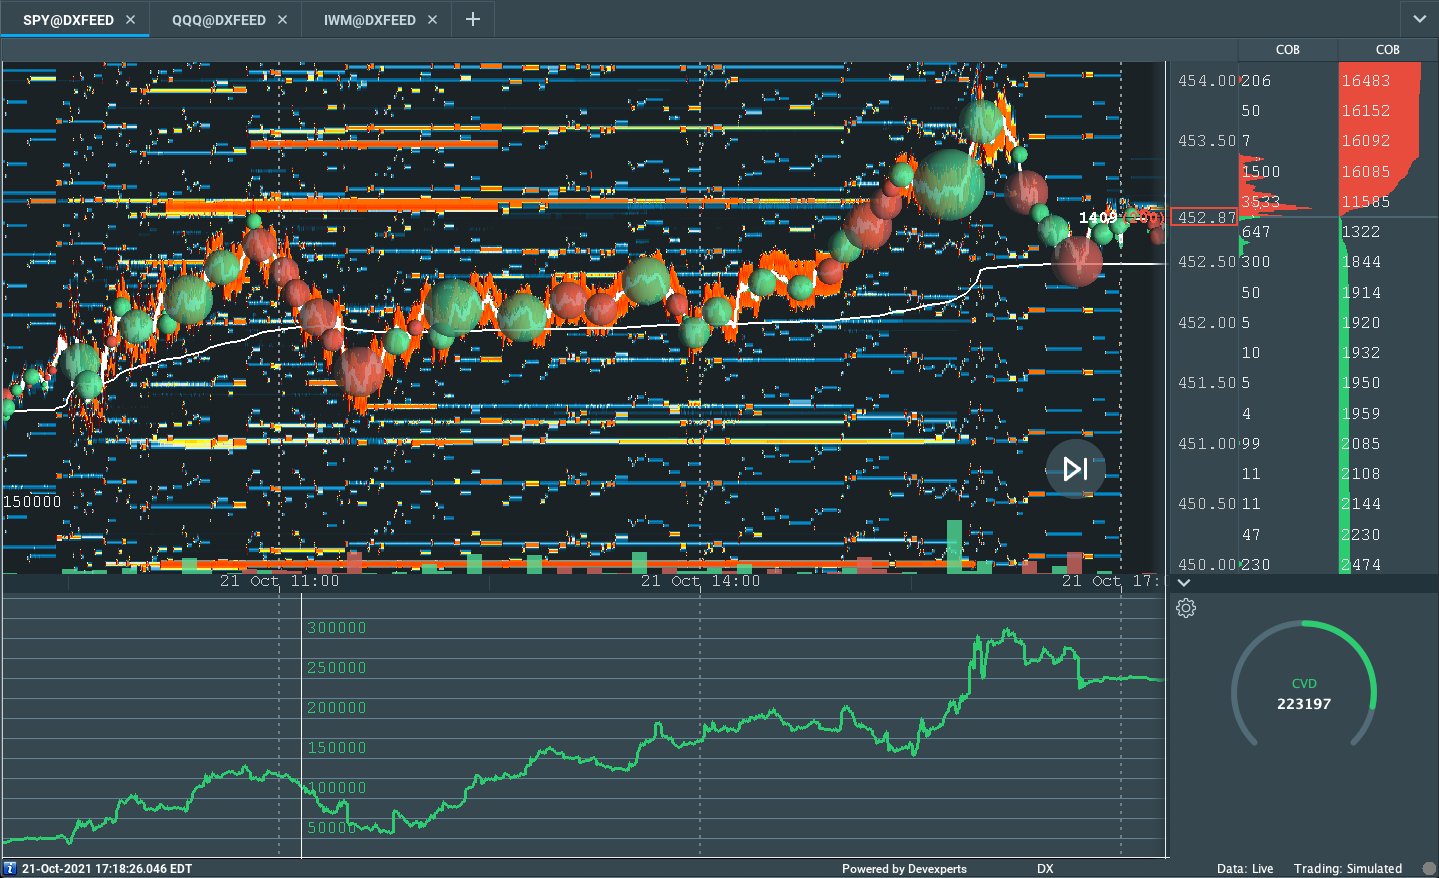
As evidenced by a b-shaped liquidation break profile distribution (i.e., morning drop on fast tempo, followed by sideways trade) there was likely selling by short-term momentum-driven participants who had poor location.

We are confident this may be the case given where the price is, relative to the volume-weighted average price (VWAP) anchored from the Federal Open Market Committee (FOMC) announcement, last week; the average buyer, since then, is losing.

To note, given the context – lackluster breadth and market liquidity metrics – the failure to expand the range, markedly, suggests there was no new money selling.

This activity, which marks a potential willingness to clear stubborn inventory and break balance, is occurring in the face of poor structure down below, a dynamic that adds to technical instability.
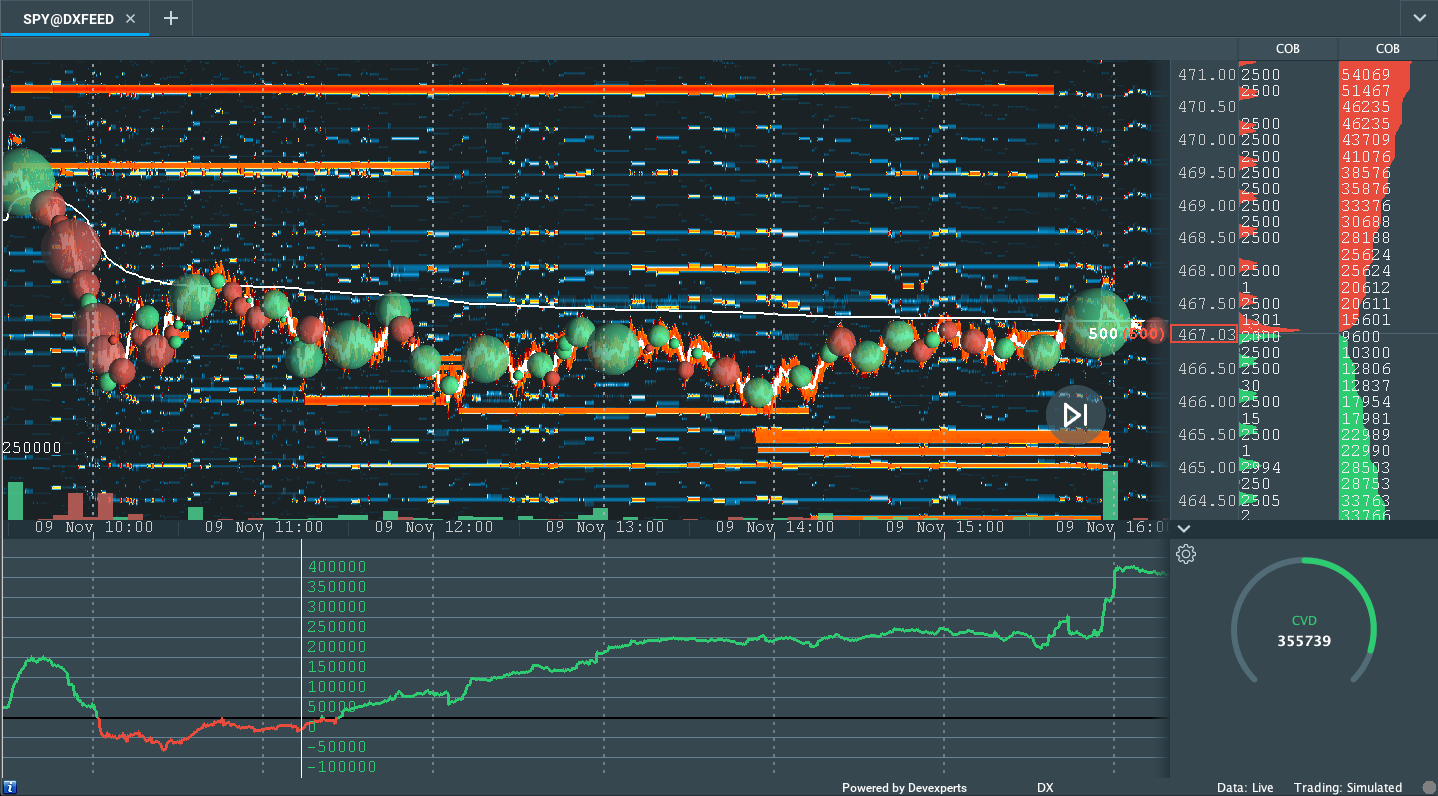
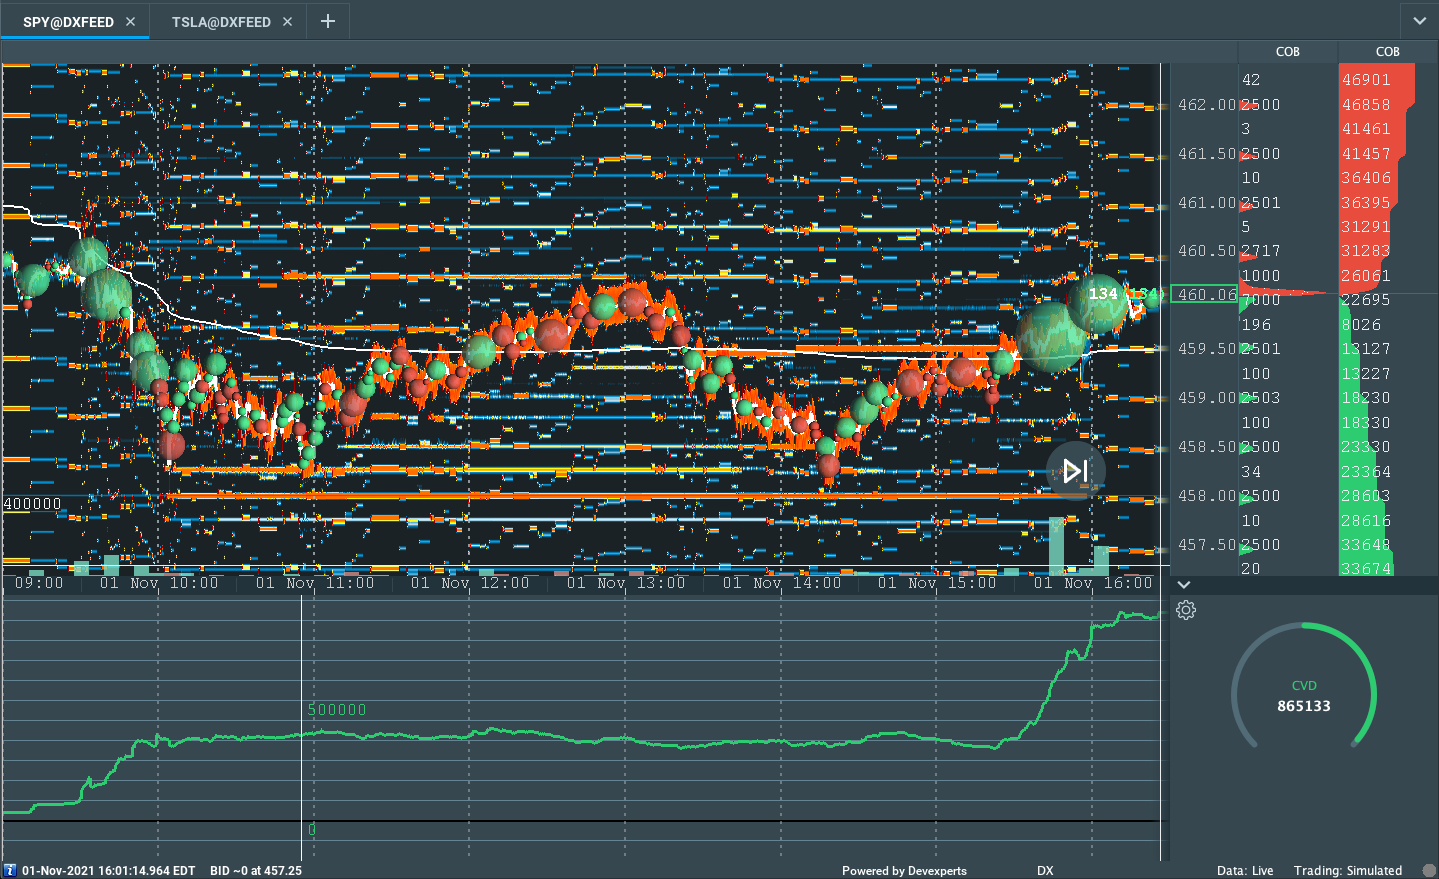
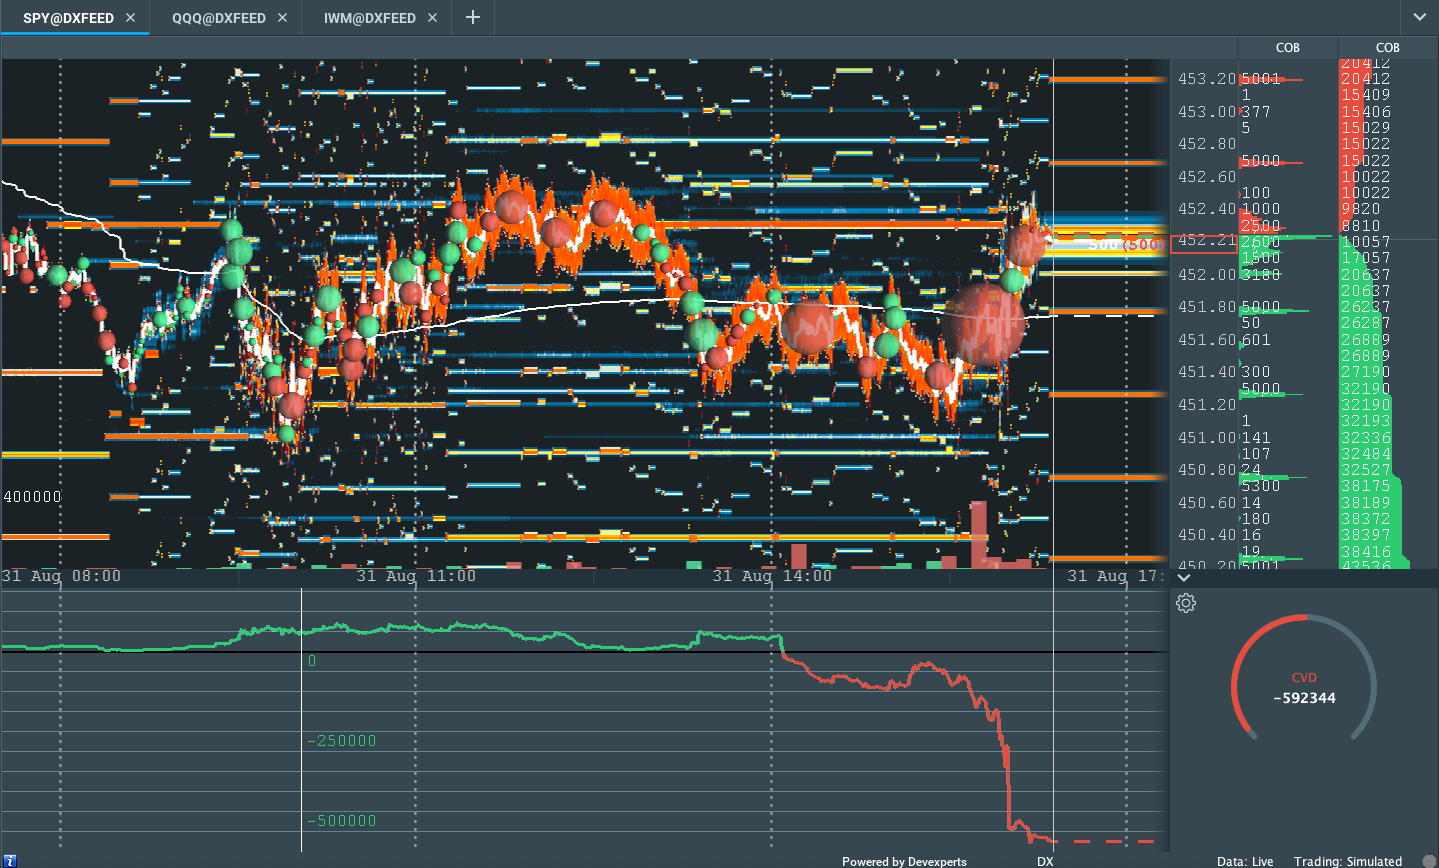
Graphic: Divergent delta (i.e., non-committed selling as measured by volume delta or buying and selling power as calculated by the difference in volume traded at the bid and offer) in SPDR S&P 500 ETF Trust (NYSE: SPY), one of the largest ETFs that track the S&P 500 index, via Bookmap. The readings are supportive of responsive trade (i.e., rotational trade that suggests current prices offer favorable entry and exit; the market is in balance).

Context: Yesterday, I made an emphasis on some of the “high leverage and risk” short-term speculators’ record call buying and put selling posed on the equity market, at large.

That’s odd. Why? 

Well, into the near-vertical price rise of highly volatile stocks like Tesla Inc (NASDAQ: TSLA), customers (you and I) signed up, through the agency of counterparties, to add liquidity to the market, via options activity.
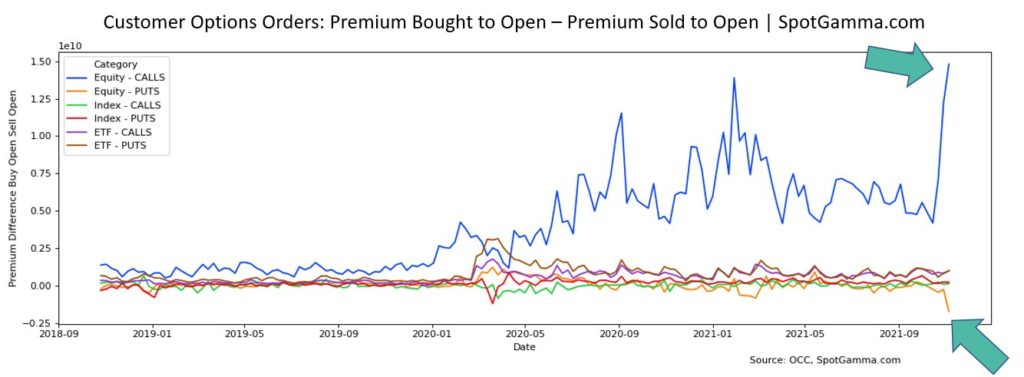
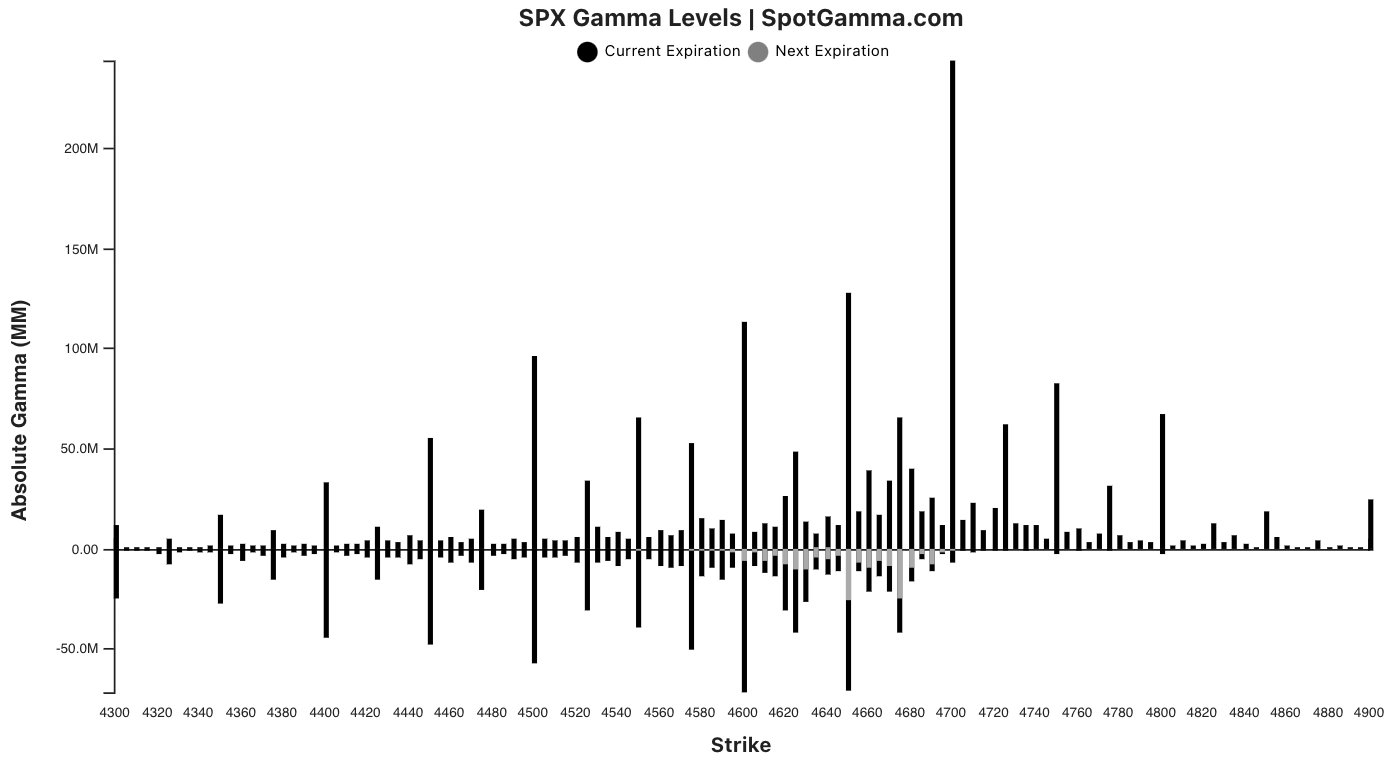
Graphic: Customers took on significant leverage in their purchase and sale of options, via SpotGamma.

So long as implied volatility remained bid (and stock prices go to the moon) – the effect of inadequate liquidity – counterparties were to exacerbate upside volatility in hedging their exposure to customer positioning. In other words, dealer short-gamma.

Note those participants that take the other side of options trades will hedge their exposure to risk by buying and selling the underlying. 

When dealers are short-gamma (e.g., Tesla), they buy into strength and sell into weakness, exacerbating volatility

When dealers are long-gamma (e.g., S&P 500), counterparties buy into weakness and sell into strength, calming volatility.

Enter shock – Elon Musk selling Tesla stock – alongside a decline in implied volatility, amidst a build of gamma at higher stock prices (which has the effect of dampening realized volatility), we saw the unthinkable happen; high-flying stocks (more so Tesla, which is a large S&P 500 index constituent) turned away from the moon and headed back to earth.

The implications of this were staggering; the bulk of customers’ short puts (long calls) quickly rose (declined) in value and traded in-the-money (out-of-the-money). 

As SpotGamma noted, yesterday, “[t]here was a serious dearth of liquidity to start today’s session,” and volatility rose, as a result, in compensating for that fact.

Now, if customer short put, counterparty long put. 

To hedge, counterparty ought to buy, right? Nope

As SqueezeMetrics explains, “Sold puts are, quite literally, a bunch of huge buy limit orders below the market, and then a bunch of liquidity-taking stop-losses further down.”
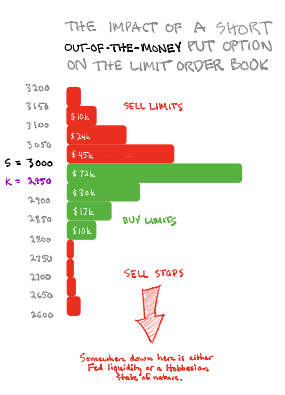
Graphic: SqueezeMetrics unpacks implications of short put options on the limit order book.

This is, to put it simply, due in part to short-term speculators lacking the wherewithal to stay in these margin-intensive positions; as price falls, put buying (covering of shorts, too) takes liquidity and destabilizes the market.

We’re starting to see this activity, in individual stocks, affect the S&P 500 complex, too

The CBOE Volatility Index (INDEX: VIX) was higher, with demand coming in across the front area of the VIX futures term structure, mostly; both suggest a demand for hedges and a reduction in the flows (e.g., vanna) that support sideways to higher trade. 
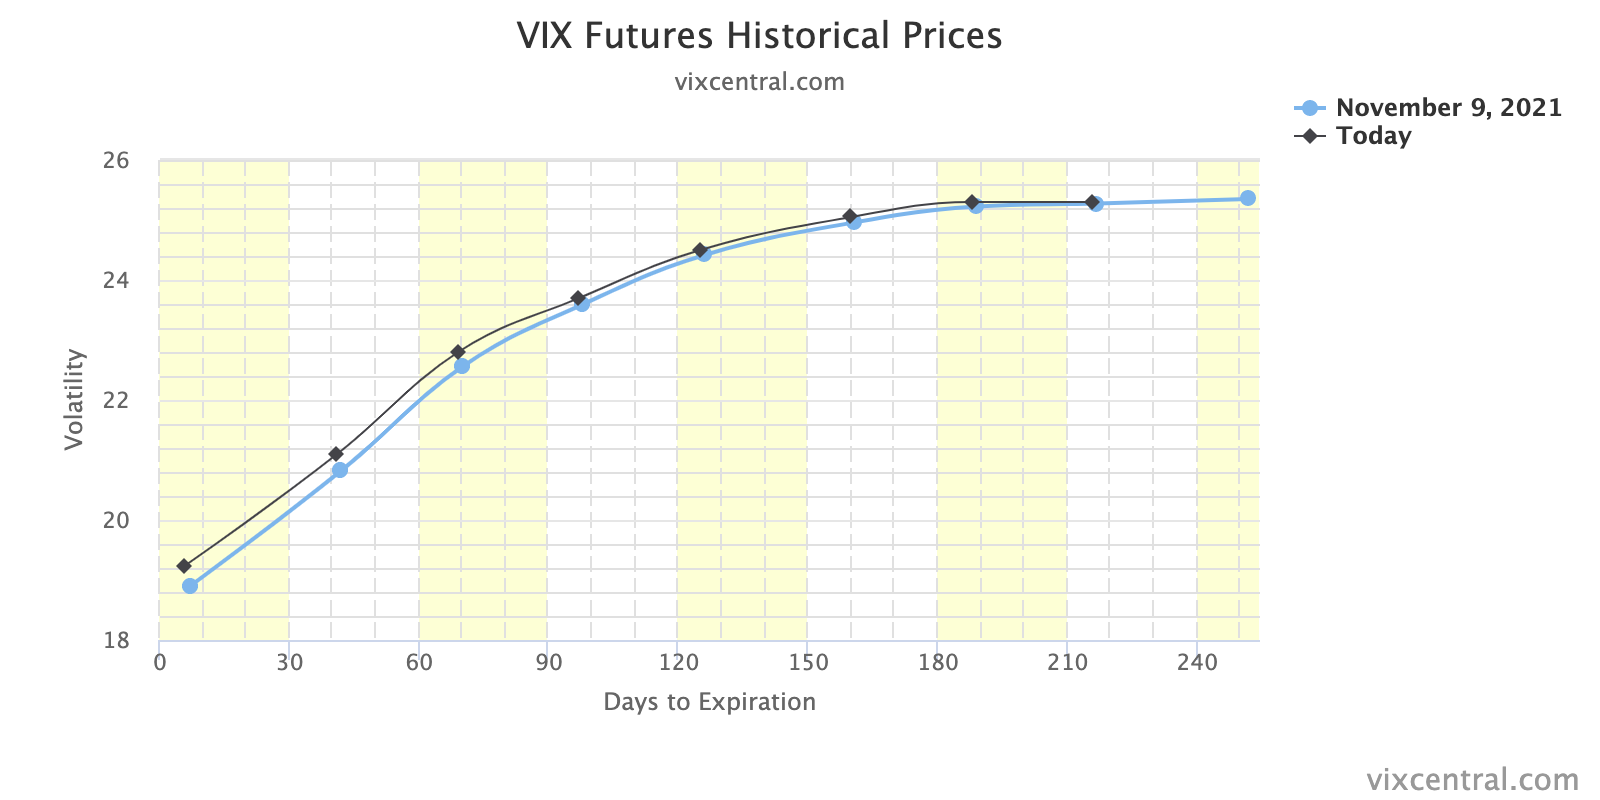
Graphic: Demand for options hedges comes in at the front end of the term structure.

That has already been reflected by the trend of outperformance in the extended day. 

In other words, the front-running of increasingly impactful (and supportive) vanna and charm flows (both of which are tied to the hedging of options exposure), as a result of increased options activity (which, at least at this juncture, exposes customers to high leverage and risk), seems to be changing, slowly. 

We’re (likely) opening sideways to lower today. That’s a change, for once!

With expectations that there may be a front-running of the monthly (OPEX) options expiration (into which the forces that promote pining usually turn stronger with counterparties supplying more liquidity as their long gamma rises), a time when dealer gamma exposure is to decline, allowing for increased realized volatility (as a result of less liquidity), the added demand for hedges (as evidenced by the bid in volatility and VIX term structure shift), is of concern. 

Participants have been uber bullish, up until early this week. Should sentiment turn, and (1) those participants cover their levered, long delta exposure alongside (2) new money hedging, tempo ought to quicken; an abrupt liquidation could be in the cards.
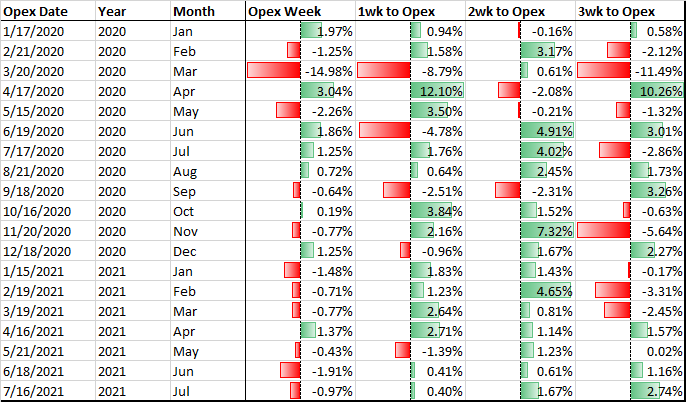
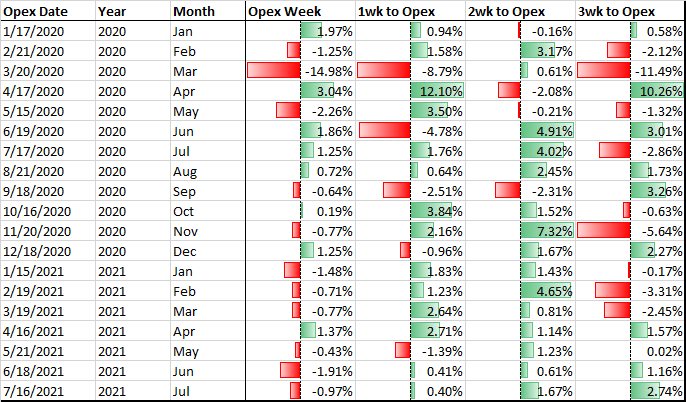
Graphic: @pat_hennessy breaks down returns for the S&P 500, categorized by the week relative to OPEX. 

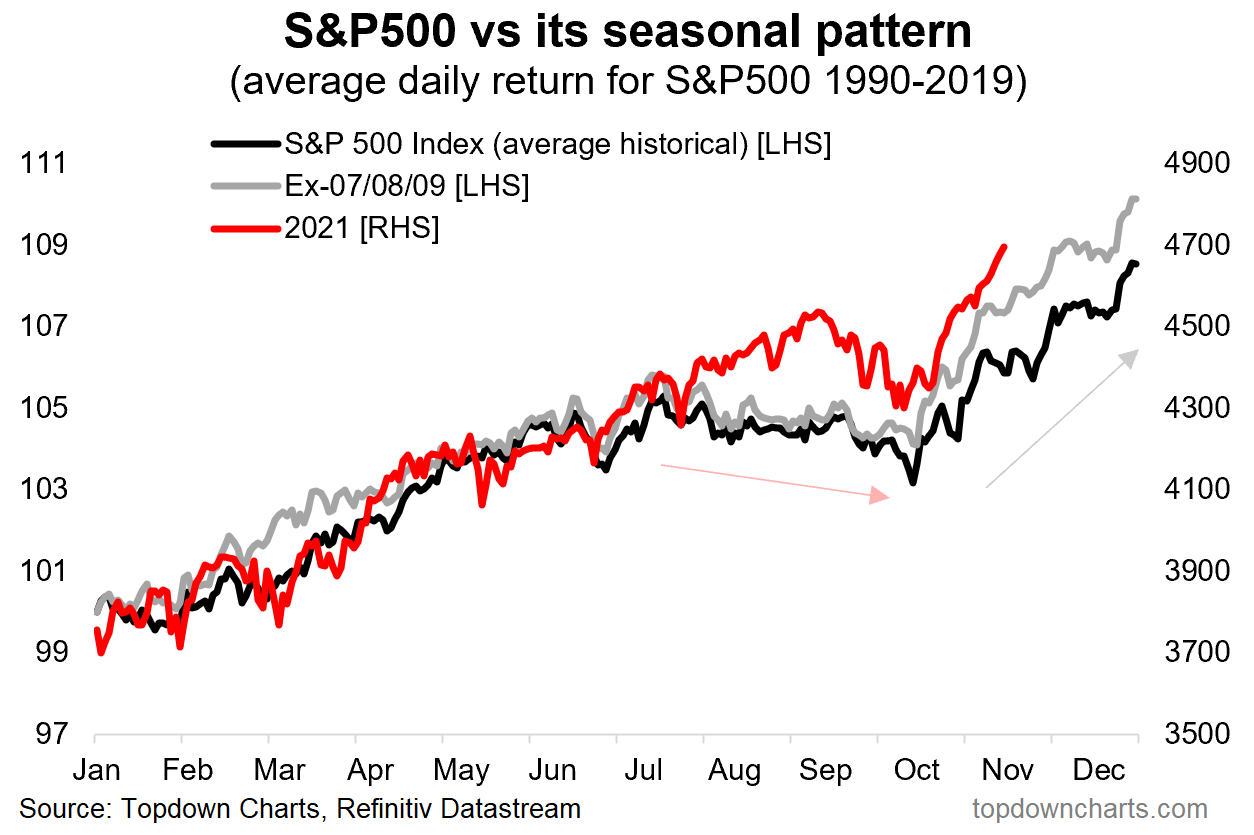
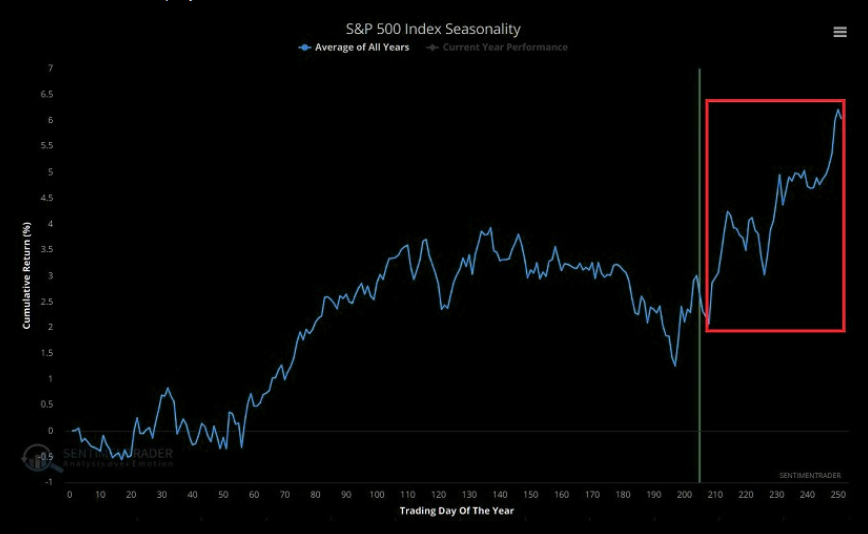
In light of seasonality, buybacks, and earnings surprises, the potential for a rally into the end of the year remains strong. As a result, we start to look for big picture references where we may see responsive buying. See the graphic below!
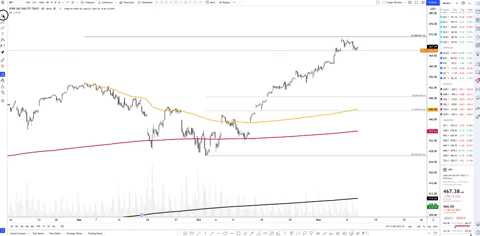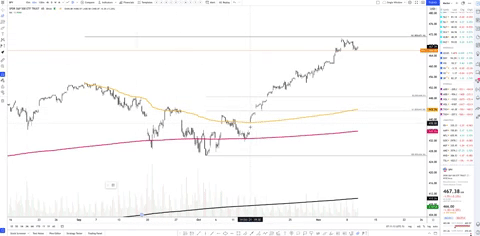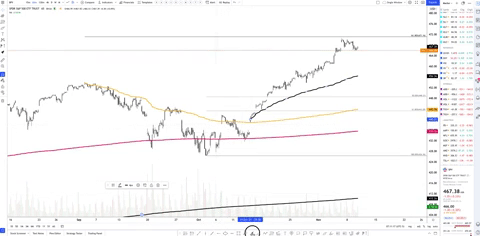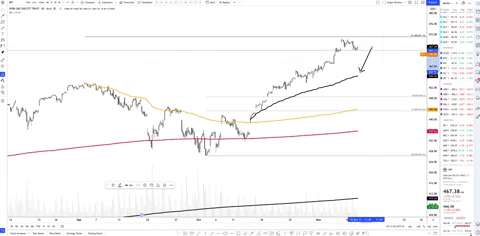
Expectations: As of 5:30 AM ET, Wednesday’s regular session (9:30 AM – 4:00 PM ET), in the S&P 500, will likely open in the middle part of a balanced overnight inventory, inside of prior-range and -value, suggesting a limited potential for immediate directional opportunity.

Balance Scenarios: Modus operandi is responsive trade (i.e., fade the edges), rather than initiative trade (i.e., play the break).

In the best case, the S&P 500 trades sideways or higher; activity above the $4,680.25 overnight high (ONH) puts in play the $4,695.25 micro composite point of control (MCPOC). Initiative trade beyond the MCPOC could reach as high as the $4,711.75 regular trade high and $4,722.00 Fibonacci, or higher.

In the worst case, the S&P 500 trades lower; activity below the $4,680.25 ONH puts in play the $4,658.75 overnight low (ONL). Initiative trade beyond the ONL could reach as low as the $4,619.00 untested point of control (VPOC) and $4,590.00 balance area boundary, or lower.

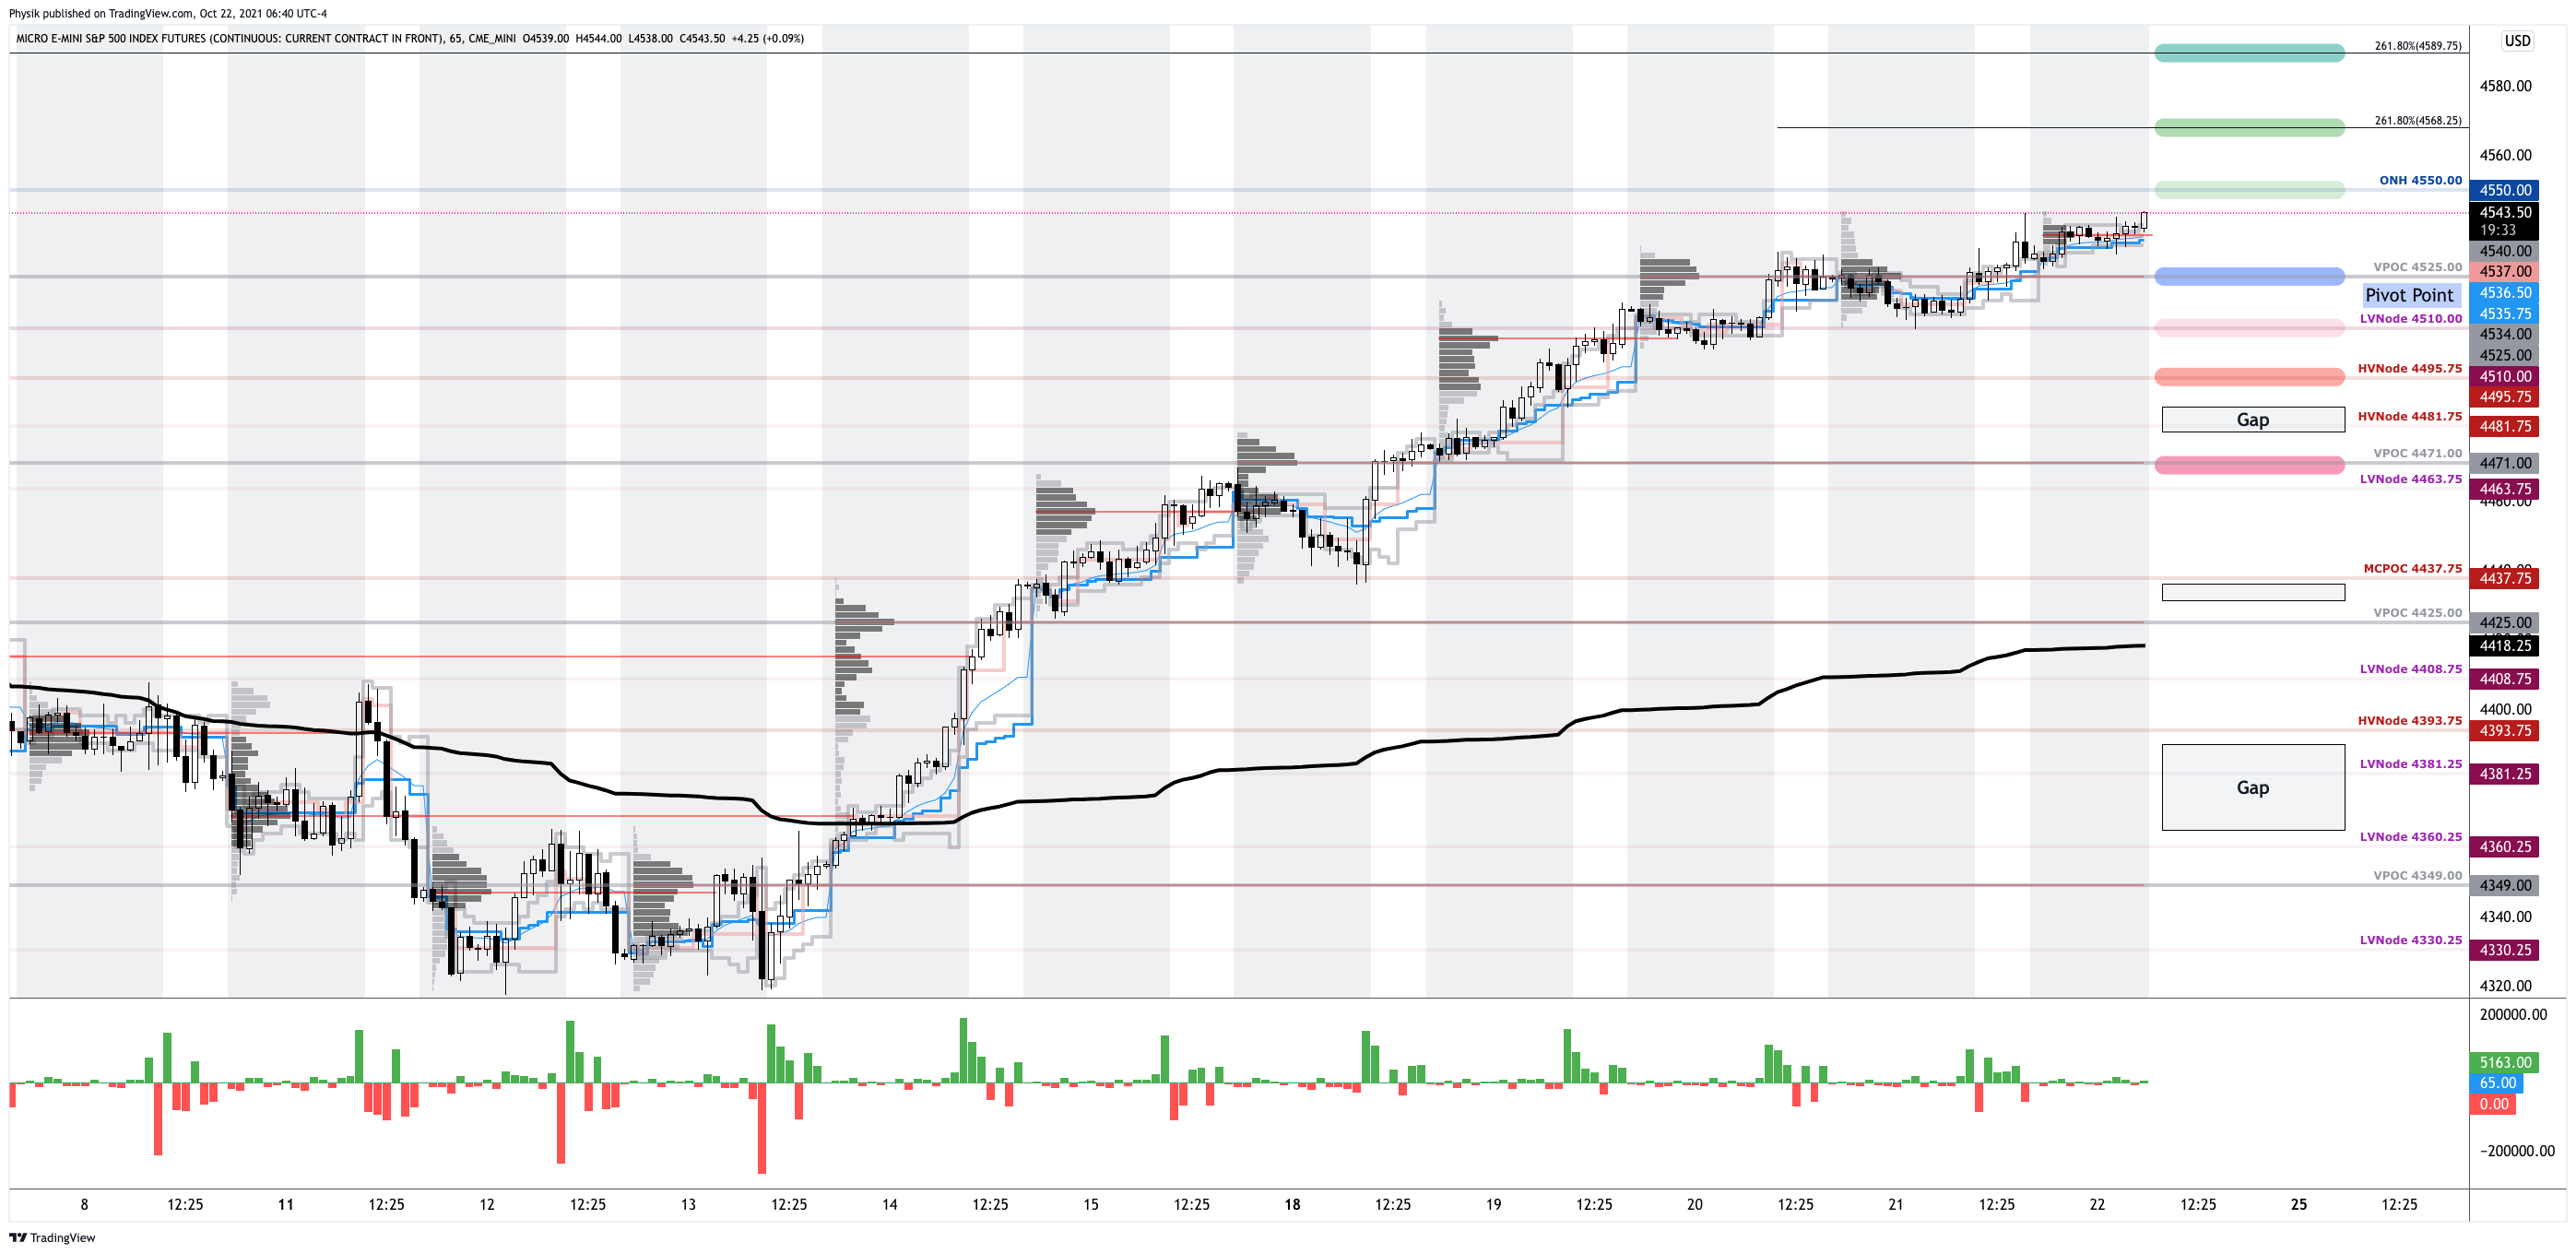
Click here to load today’s updated key levels into the web-based TradingView charting platform. Note that all levels are derived using the 65-minute timeframe. New links are produced, daily.
Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures. Note the low-volume structure beneath current prices. There is the potential for a cave-fill to widen the area deemed favorable to transact at by an increased share of participants. Learn about the profile.

Definitions

Overnight Rally Highs (Lows): Typically, there is a low historical probability associated with overnight rally-highs (lows) ending the upside (downside) discovery process.

Volume Areas: A structurally sound market will build on areas of high volume (HVNodes). Should the market trend for long periods of time, it will lack sound structure, identified as low volume areas (LVNodes). LVNodes denote directional conviction and ought to offer support on any test. 

If participants were to auction and find acceptance into areas of prior low volume (LVNodes), then future discovery ought to be volatile and quick as participants look to HVNodes for favorable entry or exit.

Vanna: The rate at which the delta of an option changes with respect to volatility.

Charm: The rate at which the delta of an option changes with respect to time.

POCs: POCs are valuable as they denote areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

MCPOCs: POCs are valuable as they denote areas where two-sided trade was most prevalent over numerous day sessions. Participants will respond to future tests of value as they offer favorable entry and exit.

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets.

Additionally, Capelj is a Benzinga finance and technology reporter interviewing the likes of Shark Tank’s Kevin O’Leary, JC2 Ventures’ John Chambers, and ARK Invest’s Catherine Wood, as well as a SpotGamma contributor, developing insights around impactful options market dynamics.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.

Categories
Commentary

Daily Brief For November 9, 2021

What Happened

Overnight, equity index futures were divergent.

The Nasdaq-100 led while the Russell 2000, which broke out of massive range, recently, slowed its pace of price discovery, trading relatively weak.

Ahead is data on the PPI (8:30 AM ET) and real household debt (11:00 AM ET).

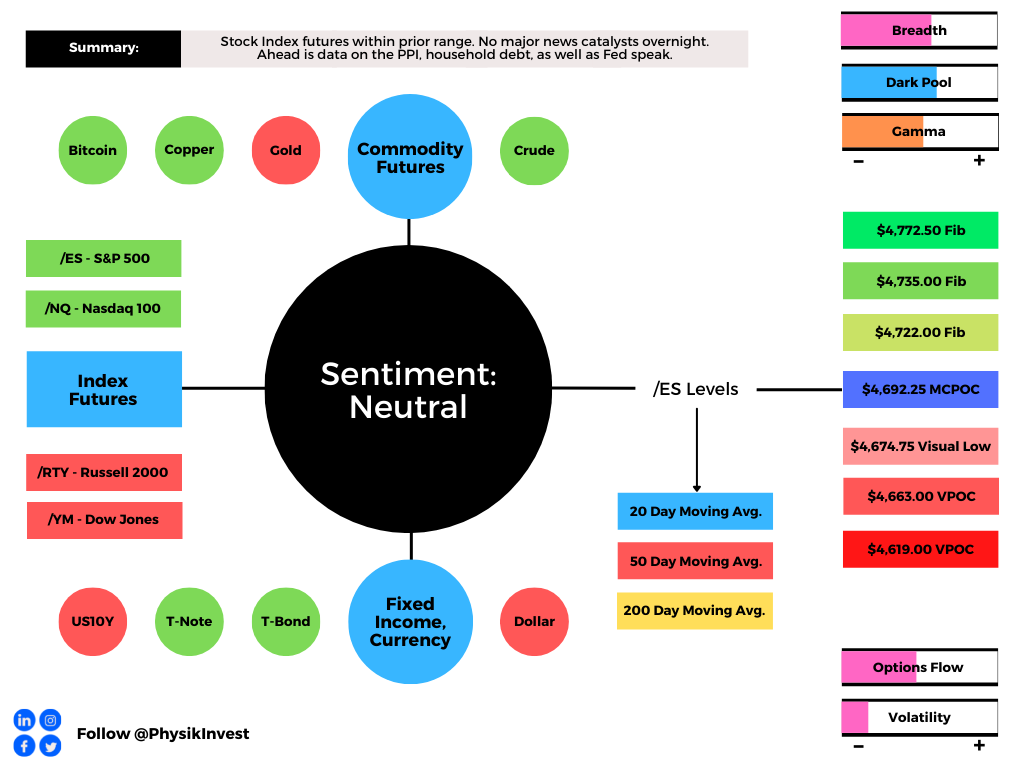
Graphic updated 6:20 AM ET. Sentiment Neutral if expected /ES open is inside of the prior day’s range. /ES levels are derived from the profile graphic at the bottom of the following section. Levels may have changed since initially quoted; click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. Learn the implications of volatility, direction, and moneyness. SHIFT data used for S&P 500 (INDEX: SPX) options activity. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect

On lackluster intraday breadth and supportive market liquidity metrics, the best case outcome occurred, evidenced by the balance and overlap of value areas (i.e., where 70% of the prior day’s trade occurred, or +/- 1 standard deviation), at the current S&P 500 prices.

This activity, which marks a potential willingness to continue balance as participants seek new information to resolve on, is built on poor structure, a dynamic that adds to technical instability.

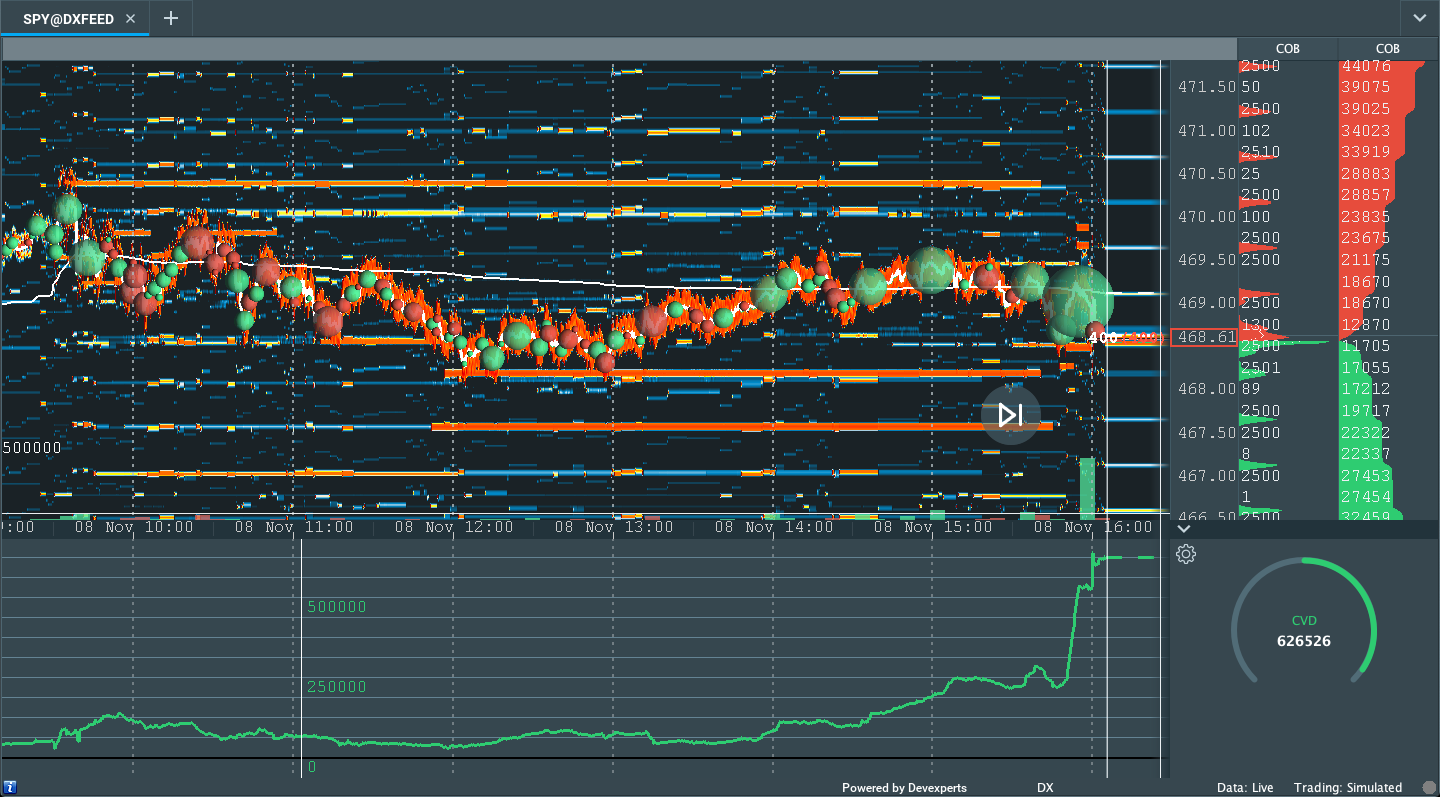
Graphic: Supportive delta (i.e., committed buying as measured by volume delta or buying and selling power as calculated by the difference in volume traded at the bid and offer) in SPDR S&P 500 ETF Trust (NYSE: SPY), one of the largest ETFs that track the S&P 500 index, via Bookmap. The readings are supportive of responsive trade (i.e., rotational trade that suggests current prices offer favorable entry and exit; the market is in balance).

Context: The aforementioned trade is happening in the context of a lot of big-picture dynamics such as the growth of derivatives exposure and tail risk, the heightened moneyness of nonmonetary assets, trends in seasonality, buybacks, earnings surprises, and more.

The implications of these themes on price are contradictory.

To elaborate, on one hand, seasonality, buybacks, and earnings surprises have bolstered (and will continue to bolster) the most recent price rise, since early October. 

Similarly, participants are seeing a trend of outperformance in the extended day, due in part to the front-running of increasingly impactful vanna and charm flows (both of which are tied to the hedging of options exposure), as a result of increased options activity (which, at least at this juncture, exposes customers to high leverage and risk). 

I say “high leverage and risk” as a result of short-term speculators’ record call buying and put selling over the past weeks.

As stated in a SpotGamma note, yesterday, “Should there be an adverse move, those short-term speculators are likely to cover (sell) their short put (long call) positions as they lack the wherewithal (capital) to maintain exposure.”

With exposure concentrated in shorter-dated expiries, the November 19 monthly options expiration (OPEX) is somewhat of a concern for us.

The reason being?

Presently, the S&P 500 is pinned near options strikes at which positive options gamma – delta sensitivity to underlying price – is highest. 

I note those participants that take the other side of options trades will hedge their exposure to risk by buying and selling the underlying. 

When dealers are short-gamma (e.g., Tesla), they buy into strength and sell into weakness, exacerbating volatility. 

When long-gamma, counterparties buy into weakness and sell into strength, calming volatility.

Coming into OPEX, the forces that promote pinning turn stronger; counterparties supply more liquidity as their long gamma becomes longer (i.e., rises), so to speak. 

As OPEX is essentially a reset (or reduction) in dealer gamma exposure, participants ought to see an increase in realized volatility as a lot of the exposure that warranted dealers’ supply of liquidity comes off the table, thus necessitating less liquidity

Less liquidity means more movement

More liquidity means less movement

Get it?

With short-term speculators taking on the risks that we’re seeing them take on, and the prospects of a front-running of post-OPEX volatility – given that, according to Pat Hennessy, “OPEX week returns peaked in 2016 and have trended lower since” – there is a potential that adverse moves force those that are off-sides cover (sell) their short put (long call) positions, thereby exacerbating near-term volatility.

We see recent options activity reflected in a sideways to higher CBOE Volatility Index (INDEX: VIX) and shift up in the VIX futures term structure; both suggest a demand for hedges and a reduction in the flows (e.g., vanna) that support sideways to higher trade. 

“The moves have been large and the demand for upside in single stock land insatiable,” said Danny Kirsch of Cornerstone Macro LLC. “Single stock vols clearly feeding into the index.”

Expectations: As of 6:20 AM ET, Tuesday’s regular session (9:30 AM – 4:00 PM ET), in the S&P 500, will likely open in the upper part of a balanced overnight inventory, inside of prior-range and -value, suggesting a limited potential for immediate directional opportunity.

Market Is In Balance: Current prices offer favorable entry and exit. Modus operandi is responsive trade (i.e., fade the edges), rather than initiative trade (i.e., play the break).

In the best case, the S&P 500 trades sideways or higher; activity above the $4,692.25 micro composite point of control (MCPOC) puts in play the $4,722.00 Fibonacci. Initiative trade beyond $4,722.00 could reach as high as the $4,735.00 and $4,772.50 Fibonacci, or higher.

In the worst case, the S&P 500 trades lower; activity below the $4,692.25 MCPOC puts in play the $4,674.75 visual low. Initiative trade beyond the visual low (likely paid attention to by short-term, technically driven market participants who seldom defend retests) could reach as low as the $4,663.00 untested point of control (VPOC) and $4,619.00 VPOC, or lower.

Click here to load today’s updated key levels into the web-based TradingView charting platform. Note that all levels are derived using the 65-minute timeframe. New links are produced, daily.
Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures. Notice Monday’s “Cave-Fill” or the act of increasing the area deemed favorable to transact at by participants. This is most obvious by observing where the bulk of Monday’s distribution sits, relative to the pocket of low-volume left behind Friday’s trade. This is a positive development. Learn about the profile.

Charts To Watch

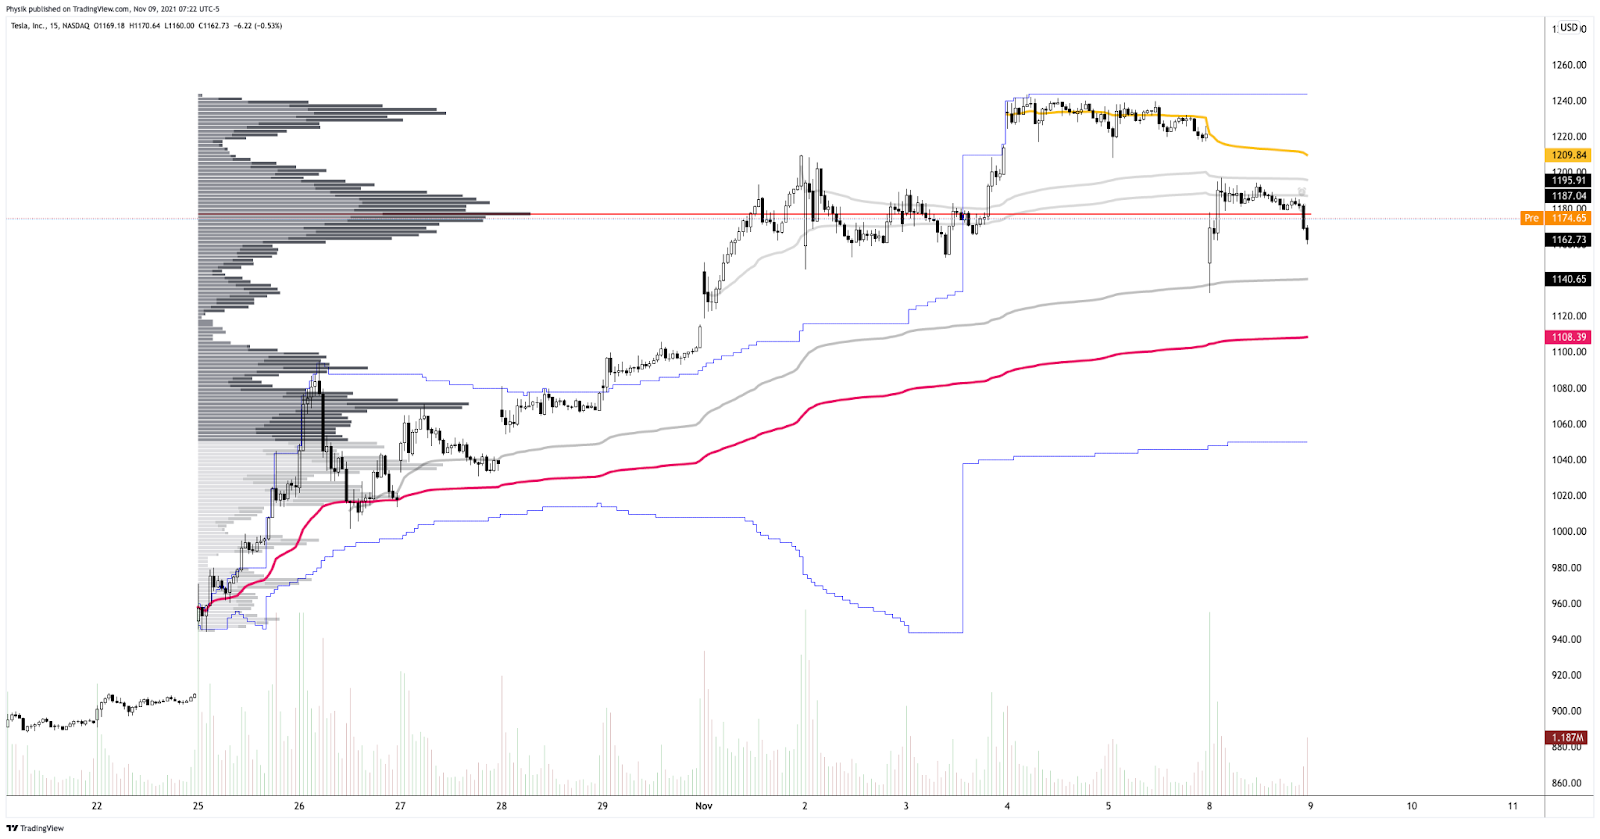
Graphic: (NASDAQ: TSLA). (S~1108, R~1187 to 1195). S is for support. R is for resistance. Looking to buy/sell responsively. 
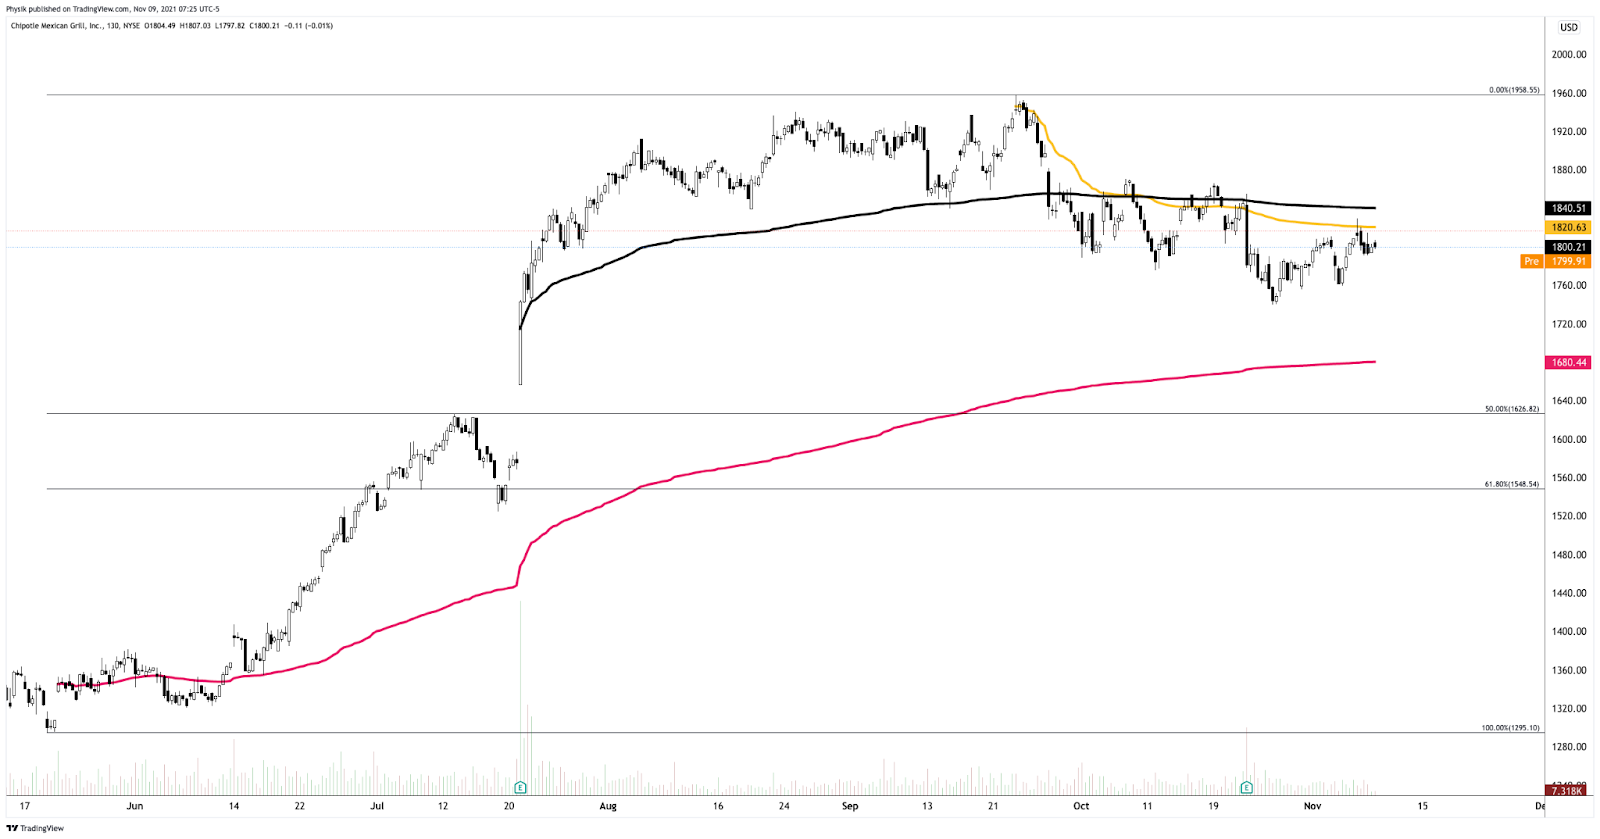
Graphic: (NYSE: CMG). (S~1680, R~1820). S is for support. R is for resistance. Looking to buy/sell responsively.
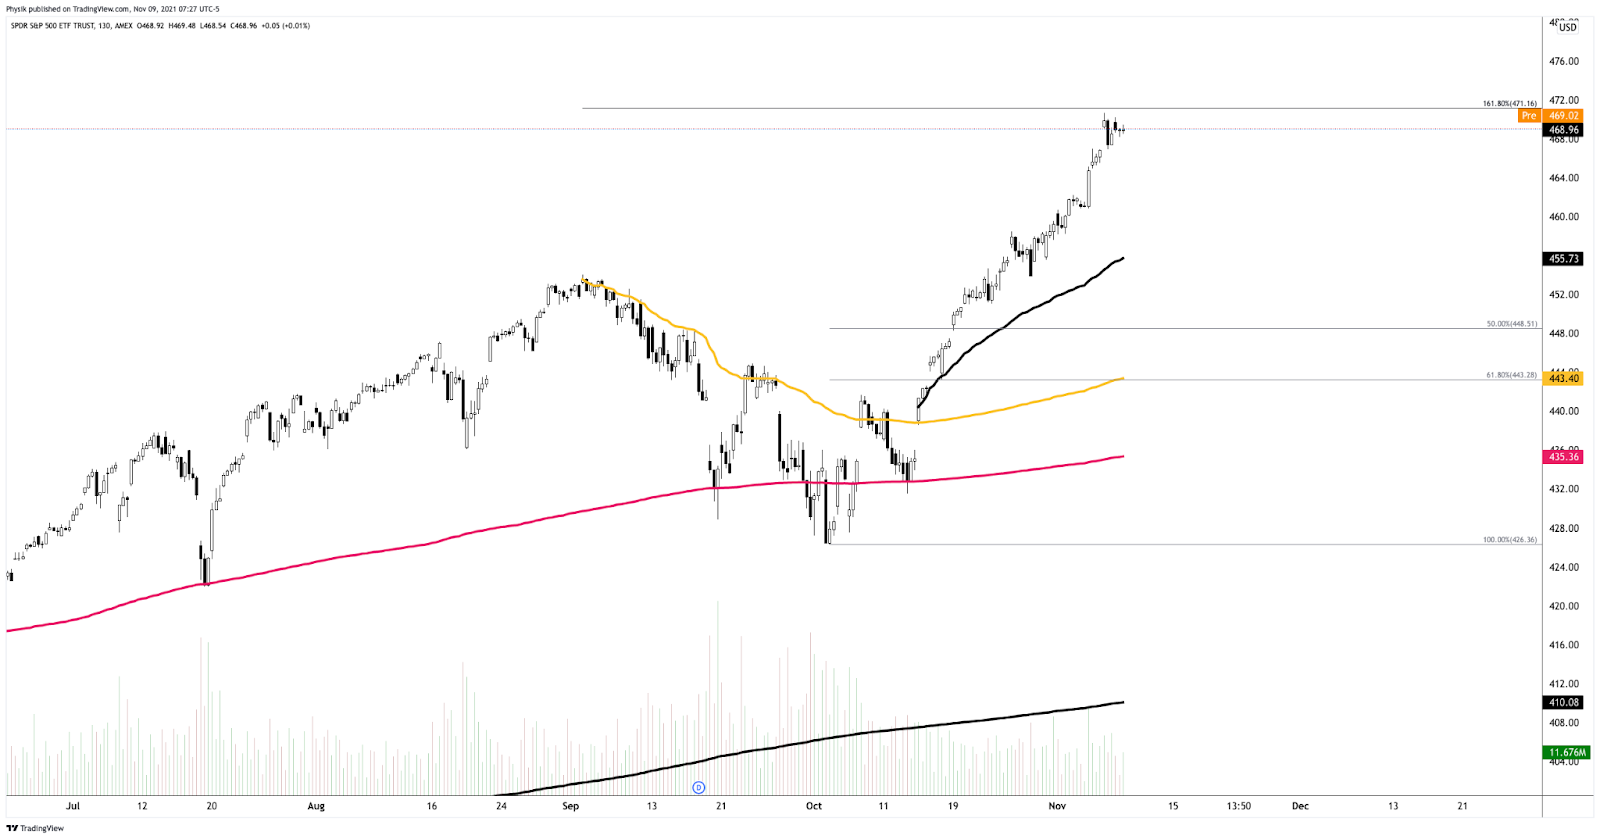
Graphic: (NYSE: SPY). (S~456, R~471). S is for support. R is for resistance. Looking to buy responsively.
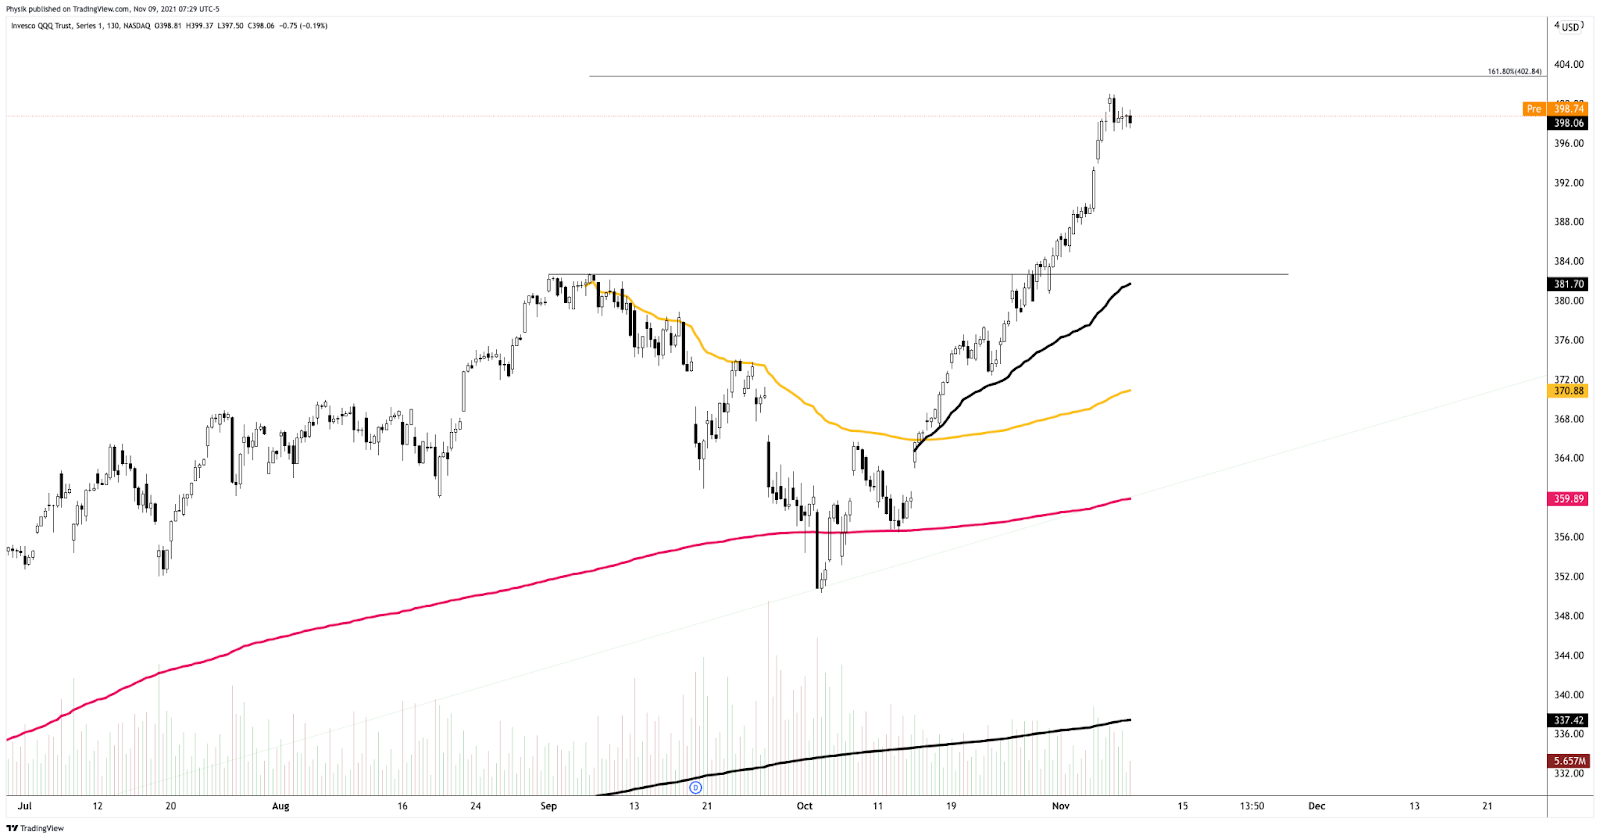
Graphic: (NASDAQ: QQQ). (S~382, R~403). S is for support. R is for resistance. Looking to buy responsively.

What People Are Saying

Definitions

Vanna: The rate at which the delta of an option changes with respect to volatility.

Charm: The rate at which the delta of an option changes with respect to time.

POCs: POCs are valuable as they denote areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

MCPOCs: POCs are valuable as they denote areas where two-sided trade was most prevalent over numerous day sessions. Participants will respond to future tests of value as they offer favorable entry and exit.

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets.

Additionally, Capelj is a Benzinga finance and technology reporter interviewing the likes of Shark Tank’s Kevin O’Leary, JC2 Ventures’ John Chambers, and ARK Invest’s Catherine Wood, as well as a SpotGamma contributor, developing insights around impactful options market dynamics.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.
Categories
Commentary

All You Need To Know For November 8, 2021

What Happened

Overnight, equity index futures auctioned sideways to higher alongside an absence in impactful fundamental developments and news catalysts.

Ahead, today, there are no major data releases scheduled.

In the following section, I unpack, in-depth, the fundamental and technical context shadowing recent trade. If you like what is said, consider sharing!
Graphic updated 6:30 AM ET. Sentiment Neutral if expected /ES open is inside of the prior day’s range. /ES levels are derived from the profile graphic at the bottom of the following section. Levels may have changed since initially quoted; click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. Learn the implications of volatility, direction, and moneyness. SHIFT data used for S&P 500 (INDEX: SPX) options activity. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect

On supportive intraday breadth and lackluster market liquidity metrics, the best case outcome occurred, evidenced by a gap and hold of newly discovered S&P 500 prices.

This activity, which marks a potential willingness to continue the trend, coincides with poor structure, a dynamic that adds to technical instability.

Graphic: Divergent delta (i.e., buying and selling power as calculated by the difference in volume traded at the bid and offer) in SPDR S&P 500 ETF Trust (NYSE: SPY). The readings are supportive of responsive trade (i.e., rotational trade that suggests current prices offer favorable entry and exit; the market is in balance).

Context: The aforementioned trade is happening in the context of interesting developments with respect to fiscal and monetary policy, as well as supply and demand imbalances.

To start, in regards to fiscal policy, ARK Invest’s Cathie Wood thinks that there will be no capital gains tax rate increases and an installment of a minimum corporate tax (about 15%). 

“I think that is one reason the market’s been rallying,” she said in an episode of In The Know

In sticking with Wood’s theses, why would the market be rallying if all that we (i.e., the market participants) see, in the news, is heavily focused around fears of inflation, so to speak? It wouldn’t; Wood feels that inflation is on its way out.

Major reasons? 

(1) Productivity increases will offset dented margins and therefore not lead to impactful price increases; (2) turmoil, with respect to China’s housing and financial sector, ought to depress commodity pricing further as “when China has caught a cold, commodity prices get pneumonia”; (3) at-home inventory build-ups may takeaway from consumption during the holidays (for which businesses are scrambling to increase inventories), and this ultimately should be reflected in commodity prices, given excess inventory; (4) disruptive innovation and declining cost curves.

“The markets are conflicting,” she explains. “You’ve got energy and financials at the top for the year, 54% and 35%, respectively. Those two sectors are associated with very strong boom time economies with a yield curve steepening, meaning long rates are rising faster than short rates.”

“That would be consistent with inflation, but the other two top-performing sectors are real estate and consumer discretionary, and those do not benefit from inflation. They benefit from inflation coming down and lower interest rates.”

The bond market, on the other hand, is in the lower inflation camp. At the same time, the dollar is going up alongside assets like bitcoin, often construed as an inflation hedge.

“Could this mean that the velocity of money is going down,” she asks. “Velocity of money has been coming down because people have been saving and putting money into assets.”

This dynamic is supported by disappointing GDP figures with growth coming mostly from inventories; “Real final sales were slightly negative. Could it be … that [millennials] would prefer not to spend on goods and services, but to invest?”

It seems that participants are increasingly extending moneyness to nonmonetary assets – given monetary policies and an environment of debt and leverage that ultimately cuts into asset price volatility – adding to the prevailing risks of carry when volatility does rise and the demand for money pushes deflation.

A great explainer on the growth of global carry is the book titled The Rise of Carry: The Dangerous Consequences of Volatility Suppression and the New Financial Order of Decaying Growth and Recurring Crisis.

“Ivy Zelman of Zelman Research came out this week. She made a fantastic call on the housing bubble and bust starting in 05-06, and she was right, just a little early. She is very concerned that the housing prices we’re seeing right now are not sustainable,” because of speculation, as well as iBuying and private equity participation. 

For instance, just last week, Zillow Group Inc (NASDAQ: Z), a major iBuyer, sought to raise liquidity, dumping properties en masse.

“This is unsustainable … and I’m wondering if even the housing market inflation is going to give way, here,” Wood added. 

That leads to the question: what effects will a taper and the eventual reduction in the Federal Reserve’s balance sheet – a removal of liquidity – have?

Thus far, given monetary frameworks and max liquidity, markets rallies have been enforced by some of the processes embedded within the volatility market

To quote Cem Karsan of Kai Volatility: “There’s this constant structural positioning that naturally drives markets higher as long as volatility is compressed, or there’s a supply of volatility.”

“As volatility is compressed, … the hedging vanna and charm flows, and whatnot will push the markets higher,” Karsan added in reference to options sliding down their term structure (vanna) and skew decaying (charm). Both dynamics have counterparties covering their hedges to the most dominant customer positioning in the market (i.e., short call, long put). 

With option volumes now comparable to stock volumes, related hedging flows can represent an increased share of volume in underlying stocks; “It’s not a coincidence that the mid-February to mid-March 2020 downturn literally started the day after February expiration and ended the day of March quarterly expiration. These derivatives are incredibly embedded in how the tail reacts and there’s not enough liquidity, given the leverage, if the Fed were to taper.”

Learn more about the implications of convexity, edge, and risk management, as well as Liquidity Cascades: The Coordinated Risk of Uncoordinated Market Participants.

Aside from a lot of these big picture dynamics – growing derivatives markets and tail risk, the heightened moneyness of nonmonetary assets, trends in seasonality, earnings surprises, and more – we have some more impactful near-term happenings to be aware of.

Graphic: “Whenever the market has been up 20%+ YTD through to October (like e.g. THIS YEAR), it has *always* had an up month in November (albeit with a n=8). Basically I would say it speaks to the momentum in the market, which despite the September stumble seems pretty much alive and well.” – Callum Thomas

The first is fragile positioning. The second is the monthly options expiration (OPEX). 

According to SqueezeMetrics analyses, “middling dark pool sentiment and middling gamma exposure [portends] … 1-month negative returns.”

Alongside that, according to data compiled and analyzed by Pat Hennessy, “2 weeks prior to OPEX (e.g., 7/30/21 to 8/6/21 in this late-cycle) [have] been extremely bullish,” while “OPEX week returns peaked in 2016 and have trended lower since.”

Graphic: @pat_hennessy breaks down returns for the S&P 500, categorized by the week relative to OPEX. 

This comes as investors marked the S&P 500 up to the $4,700.00 strike, at which positive gamma – delta sensitivity to underlying price – is highest. 

In referencing a note I wrote for SpotGamma, “as volatility continues to decline, the gamma of those options, which are now at the money, ought to increase, forcing counterparties to supply more liquidity.”

Ultimately, $4,700.00 ought to be a magnet (or resistance) into that aforementioned pre-OPEX weakness.

This is unless (1) volatility declines markedly, “a tailwind for the S&P complex as options slid[ing] down their term structure would cause dealers to continue covering their hedges in an asymmetric manner,” or (2) more capital is committed to options at higher strikes. 

Graphic: SpotGamma shows large positive gamma at the $4,700.00 strike. “Large options strikes are considered to be support or resistance zones. The change in gamma at various levels over time can shed light on how traders are viewing the market (i.e., adding calls is bullish, puts bearish).”

Expectations: As of 6:30 AM ET, Monday’s regular session (9:30 AM – 4:00 PM ET), in the S&P 500, will likely open in the upper part of a positively skewed overnight inventory, inside of prior-range and -value, suggesting a limited potential for immediate directional opportunity.

Market Is In Balance: Current prices offer favorable entry and exit. Modus operandi is responsive trade (i.e., fade the edges), rather than initiative trade (i.e., play the break).

In the best case, the S&P 500 trades sideways or higher; activity above the $4,674.75 visual low (likely paid attention to by short-term, technically driven market participants who seldom defend retests) puts in play the $4,711.75 regular trade high (RTH High). Initiative trade beyond the RTH High could reach as high as the $4,722.00 and $4,735.00 Fibonacci, or higher.

In the worst case, the S&P 500 trades lower; activity below the $4,674.75 visual low puts in play the $4,663.00 untested point of control (VPOC). Initiative trade beyond the VPOC could reach as low as the $4,619.00 VPOC and $4,590.00 balance area boundary (BAH), or lower.

As an aside, the $4,674.75 visual low corresponds with the volume-weighted average price (VWAP) anchored at last week’s Federal Open Market Committee (FOMC) meeting. 

This is a metric highly regarded by chief investment officers, among other participants, for quality of trade. Additionally, liquidity algorithms are benchmarked and programmed to buy and sell around VWAPs.

Click here to load today’s updated key levels into the web-based TradingView charting platform. Note that all levels are derived using the 65-minute timeframe. New links are produced, daily.
Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures. Learn about the profile.

Definitions

Gamma: Gamma is the sensitivity of an option to changes in the underlying price. Dealers that take the other side of options trades hedge their exposure to risk by buying and selling the underlying. When dealers are short-gamma, they hedge by buying into strength and selling into weakness. When dealers are long-gamma, they hedge by selling into strength and buying into weakness. The former exacerbates volatility. The latter calms volatility.

Vanna: The rate at which the delta of an option changes with respect to volatility.

Charm: The rate at which the delta of an option changes with respect to time.

POCs: POCs are valuable as they denote areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

Options Expiration (OPEX): Traditionally, option expiries mark an end to pinning (i.e, the theory that market makers and institutions short options move stocks to the point where the greatest dollar value of contracts will expire) and the reduction dealer gamma exposure. In recent history, this reset in dealer positioning has been front-run; prior, there was an increase in volatility after the removal of large options positions and associated hedging.

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets.

Additionally, Capelj is a Benzinga finance and technology reporter interviewing the likes of Shark Tank’s Kevin O’Leary, JC2 Ventures’ John Chambers, and ARK Invest’s Catherine Wood, as well as a SpotGamma contributor, developing insights around impactful options market dynamics.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.

Categories
Commentary

Daily Brief For November 3, 2021

Abstract

Equity index futures and commodities were mixed. Bonds sideways to higher. Volatility bid.

Ahead is a heavy day of economic releases, in the face of fundamental narratives and positioning metrics that may later support directional resolve.

What Happened

Overnight, equity index futures were flat as participants wait to initiate the next leg – higher or lower – until they are provided clarity on monetary policy frameworks, the pace of the economic recovery, and the like.

Ahead is ADP employment (8:15 AM ET), Markit services PMI (9:45 AM ET), ISM services index and factory orders (10:00 AM ET), as well as Federal Reserve statements (2:00 PM ET).

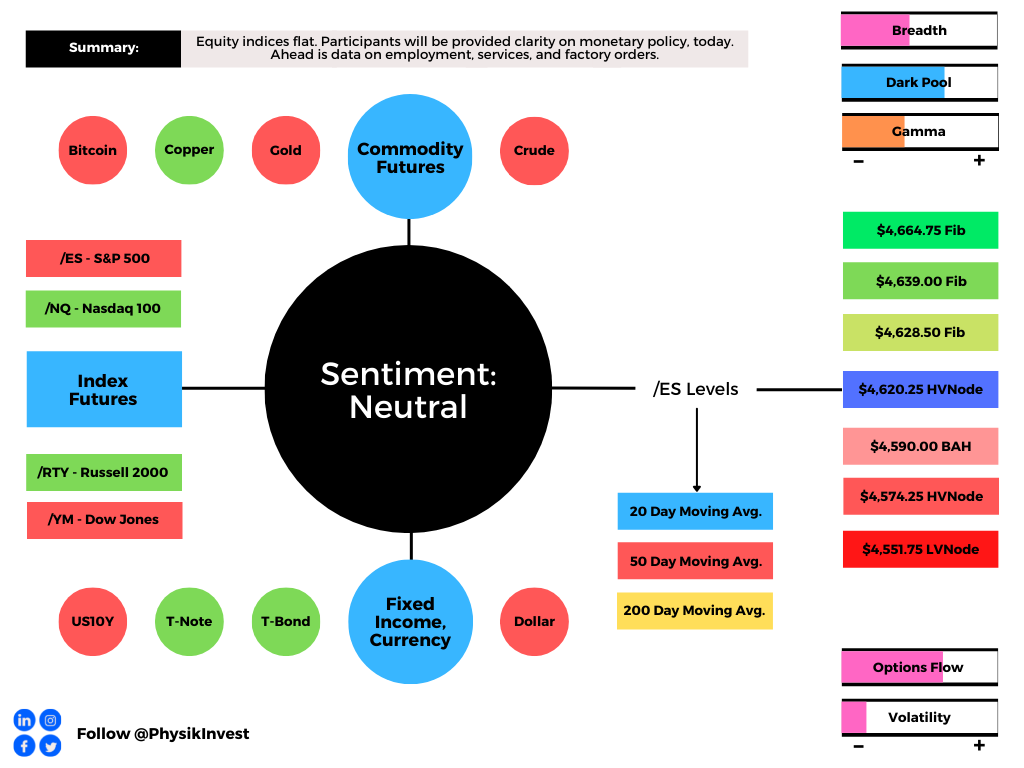
Graphic updated 6:30 AM ET. Sentiment Neutral if expected /ES open is inside of the prior day’s range. /ES levels are derived from the profile graphic at the bottom of the following section. Levels may have changed since initially quoted; click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. Learn the implications of volatility, direction, and moneyness. SHIFT data used for S&P 500 (INDEX: SPX) options activity. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect

Action: On lackluster breadth and market liquidity metrics, the best case outcome occurred, evidenced by participants’ exploration of new prices in the S&P 500.

Intent: The intraday excess high marks potential exhaustion (or willingness to end trend). Also, the rounding of the composite profile (i.e., developing ledge) suggests participants are either painting themselves into a corner or there is a lack of conviction to take price higher.

Validation: Sideways trade, above the $4,590.00 balance area high (BAH), and overlapping value areas, validates the market’s intent to pause ahead of new information.

Consideration: Poor structure left behind prior initiative trade (as evidenced by the presence of numerous gaps and p-shaped emotional, multiple-distribution profile structures which denote short-covering and a lack of material, new-money buying) adds to technical instability.

Should the market crack, participants will likely look to check old value (i.e., revisit, repair, and strengthen) these pockets of low-volume. This is called the “cave-fill” process, in volume profile terms.

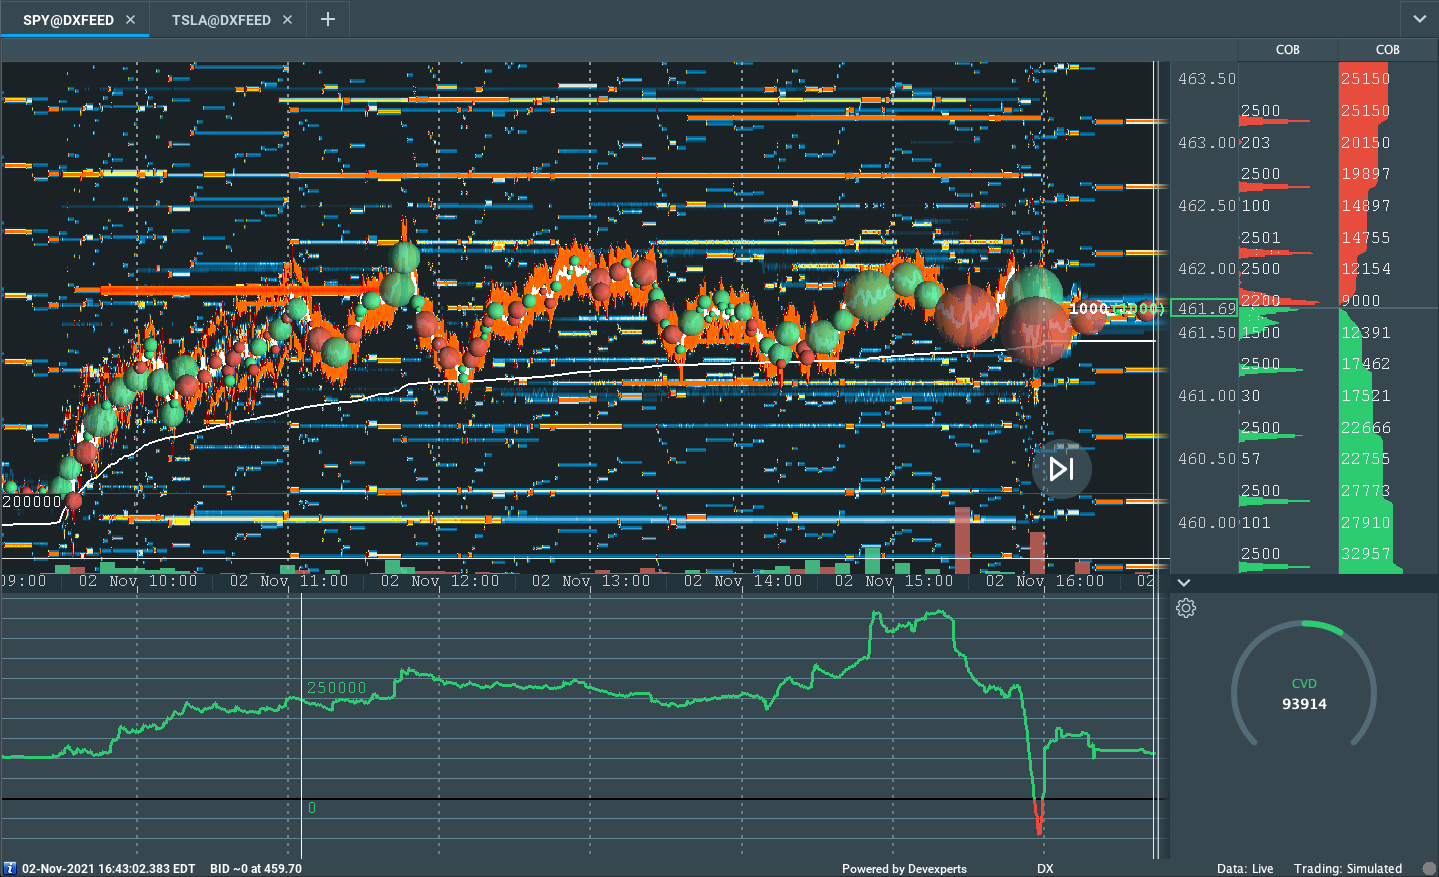
Graphic: Flat delta (i.e., non-committed buying as measured by volume delta or buying and selling power as calculated by the difference in volume traded at the bid and offer) in SPDR S&P 500 ETF Trust (NYSE: SPY), one of the largest ETFs that track the S&P 500 index, via Bookmap. The readings are supportive of responsive trade (i.e., rotational trade that suggests current prices offer favorable entry and exit; the market is in balance).

Context: Federal Open Market Committee (FOMC) announcement later today.

The announcement will provide participants with color on the economic recovery and the Federal Reserve’s intent to continue supporting the economy, at the rate it has. 

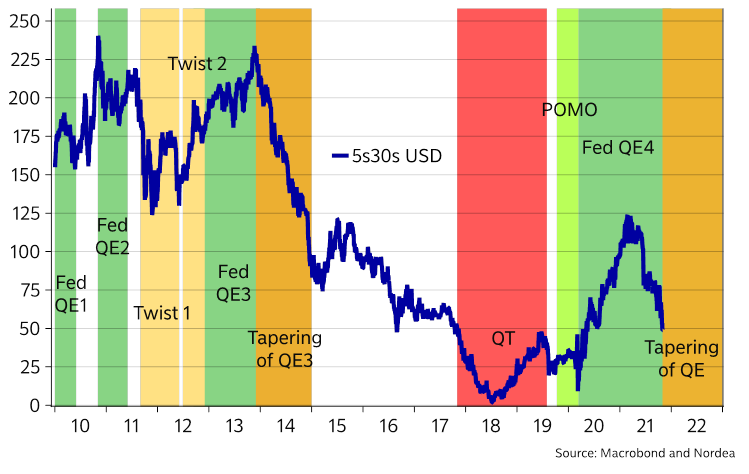
Nordea’s Andreas Steno Larsen states: “Jay Powell will have to walk on eggshells to prevent an acceleration of the front-end of the USD yield curve. Arguments for the Fed to tighten policy keep piling up and hence we see a swift tapering process (30B a meeting) and a first hike in June.” 

“The combination of 1) even higher inflation prints during Q4 (with several extremely volatile base effects), 2) a removal of USD liquidity, 3) a historically weak credit impulse into 2022 (due to a massive credit expansion 20/21) sounds like the perfect flattener setup to us,” which may weigh on sentiment and long term investments.

Graphic: “Keep flattening the yield curve during tapering,” via Nordea.

In terms of positioning, the CBOE Volatility Index (INDEX: VIX) was a touch higher, while spreads across the VIX futures term structure widened with demand coming in at the front.

Such a situation, as touched on yesterday, in addition to the long-gamma environment (in which counterparties hedge their warehoused options risk by buying underlying into weakness and selling into strength), has the effect of making it difficult to resolve directionally.

The reasons are: (1) options will slide down their term structure (vanna) and (2) skew decays (charm). When this happens, we expect to see supportive flows as dealers cover their short equity/futures hedges. 

With volatility bid, the effect of vanna and charm is dulled. As a result, it is likely that participants see more movement after the FOMC announcement.

To note, the potential for upside resolve comes down to how participants take the FOMC announcement. We know that, according to SpotGamma, there is increased capital being committed to higher and higher options strikes, a development often seen as bullish.

Expectations: As of 6:30 AM ET, Wednesday’s regular session (9:30 AM – 4:00 PM ET), in the S&P 500, will likely open in the middle part of a neutral overnight inventory, inside of prior-range and -value, suggesting a limited potential for immediate directional opportunity.

Balance (Two-Timeframe Or Bracket) Is The Status Quo: Rotational trade that denotes current prices offer favorable entry and exit. Modus operandi is responsive trade (i.e., fade the edges), rather than initiative trade (i.e., play the break).

In the best case, the S&P 500 trades sideways or higher; activity above the $4,620.25 high volume area (HVNode) pivot puts in play the $4,628.50 Fibonacci extension. Initiative trade beyond $4,628.50 could reach the $4,639.00 and $4,664.75 Fibonacci levels, or higher.

In the worst case, the S&P 500 trades lower; activity below the $4,620.25 HVNode puts in play the $4,590.00 balance area high (BAH). Initiative trade beyond the BAH could reach as low as the $4,574.25 HVNode and $4,551.75 low volume area (LVNode), or lower.

Click here to load today’s updated key levels into the web-based TradingView charting platform. Note that all levels are derived using the 65-minute timeframe. New links are produced, daily.
Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures. Learn about the profile.

What People Are Saying

Definitions

Cave-Fill Process: Widened the area deemed favorable to transact at by an increased share of participants. This is a good development.

Volume Areas: A structurally sound market will build on areas of high volume (HVNodes). Should the market trend for long periods of time, it will lack sound structure, identified as low volume areas (LVNodes). LVNodes denote directional conviction and ought to offer support on any test. 

If participants were to auction and find acceptance into areas of prior low volume (LVNodes), then future discovery ought to be volatile and quick as participants look to HVNodes for favorable entry or exit.

Excess: A proper end to price discovery; the market travels too far while advertising prices. Responsive, other-timeframe (OTF) participants aggressively enter the market, leaving tails or gaps which denote unfair prices.

Ledges: Flattened area on the profile which suggests responsive participants are in control, or initiative participants lack the confidence to continue the discovery process. The ledge will either hold and force participants to liquidate (cover) their positions, or crack and offer support (resistance).

Value-Area Placement: Perception of value unchanged if value overlapping (i.e., inside day). Perception of value has changed if value not overlapping (i.e., outside day). Delay trade in the former case.

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets.

Additionally, Capelj is a Benzinga finance and technology reporter interviewing the likes of Shark Tank’s Kevin O’Leary, JC2 Ventures’ John Chambers, and ARK Invest’s Catherine Wood, as well as a SpotGamma contributor, developing insights around impactful options market dynamics.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.
Categories
Commentary

Daily Brief For November 2, 2021

Abstract

Equity index futures mixed. Commodities mixed. Bonds sideways to lower. Volatility expanded.

Ahead is a light day of economic releases, in the face of fundamental narratives and positioning metrics that support intraday price stability.

What Happened

Overnight, equity index futures auctioned sideways as participants sought to position themselves for guidance on monetary policy, later this week.

Ahead is data on homeownership rates (10:00 AM ET).

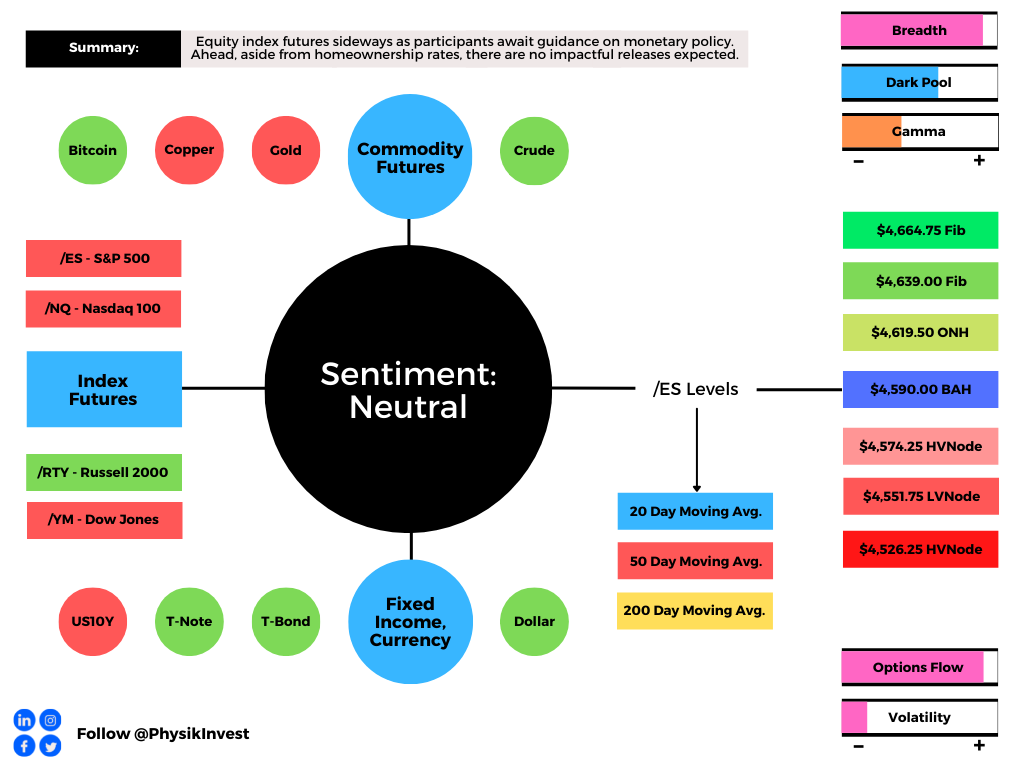
Graphic updated 6:30 AM ET. Sentiment Neutral if expected /ES open is inside of the prior day’s range. /ES levels are derived from the profile graphic at the bottom of the following section. Levels may have changed since initially quoted; click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. Learn the implications of volatility, direction, and moneyness. SHIFT data used for S&P 500 (INDEX: SPX) options activity. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect

Action: On divergent intraday breadth and supportive market liquidity metrics, the worst-case outcome occurred, evidenced by the S&P 500’s acceptance of prices within Friday’s late-day spike, out of balance.

Intent: As also evidenced by the overlap of value areas, the acceptance of prices, within Friday’s late-day spike, out of balance, marks a potential willingness to continue sideways.

Validation: Sideways trade, above the $4,590.00 balance area high (BAH), validates the market’s prevailing intent to base ahead of the Federal Open Market Committee (FOMC) decision, later this week.

Consideration: Weak structure left behind prior initiative trade adds to technical instability. 

To elaborate, for instance, Monday’s trade found responsive buyers at the $4,587.00 untested point of control (VPOC). This level likely was only known by participants who act on visual cues. 

These technically-driven participants are generally thought to not be able to defend retests. Therefore, these participants ought to quickly liquidate, if proven wrong, on a break of the BAH.

Graphic: Supportive delta (i.e., committed buying as measured by volume delta or buying and selling power as calculated by the difference in volume traded at the bid and offer) in SPDR S&P 500 ETF Trust (NYSE: SPY), one of the largest ETFs that track the S&P 500 index, via Bookmap. The readings are supportive of responsive trade (i.e., rotational trade that suggests current prices offer favorable entry and exit; the market is in balance).

Context: Ample liquidity, peak growth, inflation, strong seasonality and buybacks, as well as monetary and fiscal policy uncertainties, and single-stock volatility.

Graphic: S&P 500 seasonality via The Market Ear.

Based on this context, Moody’s Corporation (NYSE: MCO) forecasts a peak; “The Dow Jones Industrial Average has peaked and will gradually decline during the next year. Risks are heavily weighted to the upside, but peak growth, inflation uncertainty around fiscal policy, and the Fed tapering could weigh on equity markets.”

In terms of positioning, the CBOE Volatility Index (INDEX: VIX) was higher, while demand came in across the VIX futures term structure, suggesting participants are inclined to hedge against near-term equity market instability.

Such a situation, in addition to the long-gamma environment (in which counterparties hedge their warehoused options risk by buying underlying into weakness and selling into strength), has the effect of making it difficult to resolve directionally.

The reason is, there are two knowns; as volatility contracts, (1) options will slide down their term structure (vanna) and (2) skew decays (charm). 

When this happens, we expect to see supportive flows when the dealers cover their short equity/futures hedges. With volatility bid, the effect of vanna and charm is dulled. It is likely that participants see more robust movement after the FOMC announcement, later this week.

In a separate note on volatility in stocks like Tesla Inc (NASDAQ: TSLA), SpotGamma says the following: “These rampant moves are appearing to be more widespread, and we believe this invokes instability that usually ends badly.”

Expectations: As of 6:30 AM ET, Monday’s regular session (9:30 AM – 4:00 PM ET), in the S&P 500, will likely open in the top part of a negatively skewed overnight inventory, inside of prior-range and -value, suggesting a limited potential for immediate directional opportunity.

Balance-Break Scenarios: A change in the market (i.e., the transition from two-time frame trade, or balance, to one-time frame trade, or trend) occurred.

We monitor for continued acceptance outside of the balance area. Rejection (i.e., a move below the balance area high) portends a move to the opposite end of the balance, lower.

In the best case, the S&P 500 trades sideways or higher; activity above the $4,590.00 BAH puts in play the $4,619.50 overnight high (ONH). Initiative trade beyond the ONH could reach as high as the $4,639.00 and $4,664.75 Fibonacci figures, or higher.

In the worst case, the S&P 500 trades lower; activity below the $4,590.00 BAH puts in play the $4,574.25 high volume area (HVNode). Initiative trade beyond the HVNode could reach as low as the $4,551.75 low volume area (LVNode), and $4,526.25 HVNode, or lower.

Click here to load today’s updated key levels into the web-based TradingView charting platform. Note that all levels are derived using the 65-minute timeframe. New links are produced, daily.
Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures. Learn about the profile.

What People Are Saying

Definitions

Spikes: Spike’s mark the beginning of a break from value. Spikes higher (lower) are validated by trade at or above (below) the spike base (i.e., the origin of the spike).

Overnight Rally Highs (Lows): Typically, there is a low historical probability associated with overnight rally-highs (lows) ending the upside (downside) discovery process.

Volume Areas: A structurally sound market will build on areas of high volume (HVNodes). Should the market trend for long periods of time, it will lack sound structure, identified as low volume areas (LVNodes). LVNodes denote directional conviction and ought to offer support on any test. 

If participants were to auction and find acceptance into areas of prior low volume (LVNodes), then future discovery ought to be volatile and quick as participants look to HVNodes for favorable entry or exit.

Gamma: Gamma is the sensitivity of an option to changes in the underlying price. Dealers that take the other side of options trades hedge their exposure to risk by buying and selling the underlying. When dealers are short-gamma, they hedge by buying into strength and selling into weakness. When dealers are long-gamma, they hedge by selling into strength and buying into weakness. The former exacerbates volatility. The latter calms volatility.

Vanna: The rate at which the delta of an option changes with respect to volatility.

Charm: The rate at which the delta of an option changes with respect to time.

Options: If an option buyer was short (long) stock, he or she would buy a call (put) to hedge upside (downside) exposure. Option buyers can also use options as an efficient way to gain directional exposure.

Value-Area Placement: Perception of value unchanged if value overlapping (i.e., inside day). Perception of value has changed if value not overlapping (i.e., outside day). Delay trade in the former case.

POCs: POCs are valuable as they denote areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets.

Additionally, Capelj is a Benzinga finance and technology reporter interviewing the likes of Shark Tank’s Kevin O’Leary, JC2 Ventures’ John Chambers, and ARK Invest’s Catherine Wood, as well as a SpotGamma contributor, developing insights around impactful options market dynamics.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.
Categories
Commentary

Daily Brief For October 22, 2021

Editor’s Note: Due to travel commitments, the Daily Brief will not be sent 10/25-10/27.

Apologies and have a great weekend!

Market Commentary

Out of sync with bonds, equity index futures were mostly sideways to higher. Commodities were higher. Volatility compressed.

  • Ahead is manufacturing, services PMI.
  • Participants discover uncharted prices.
  • Options positioning presented tailwind.

What Happened: U.S. stock index futures, less the Nasdaq 100, auctioned sideways to higher overnight as participants looked to discover new prices.

Ahead is data on manufacturing and services PMI (9:45 AM ET), as well as Fed-speak (10:00 and 11:00 AM ET).

Graphic updated 6:40 AM ET. Sentiment Risk-On if expected /ES open is above the prior day’s range. /ES levels are derived from the profile graphic at the bottom of the following section. Levels may have changed since initially quoted; click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. SHIFT data used for S&P 500 (INDEX: SPX) options activity. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect: As of 6:30 AM ET, Friday’s regular session (9:30 AM – 4:00 PM EST) in the S&P 500 will likely open on a small gap, just outside of prior-range and -value, suggesting a potential for immediate directional opportunity.

Gap Scenarios: Gaps ought to fill quickly. Should they not, that’s a signal of strength; do not fade. Leaving value behind on a gap-fill or failing to fill a gap (i.e., remaining outside of the prior session’s range) is a go-with indicator.

Auctioning and spending at least 1-hour of trade back in the prior range suggests a lack of conviction; in such a case, do not follow the direction of the most recent initiative activity.

During the prior day’s regular trade, on light volume, nonparticipatory intraday breadth, and supportive market liquidity metrics, the best case outcome occurred, evidenced by upside resolve, above flattened day timeframe profile structures, or ledges.

This activity comes after prior sessions left behind numerous gaps and emotional, multiple-distribution profile structures.

Further, Thursday’s overnight gap in range, below value, set indices up for what is called the cave-fill process (characterized by repair and strengthening of low volume areas).

The day timeframe activity rejected lower prices; participants auctioned to new highs in both regular and overnight trade, putting in play a recovery of the un-adjusted overnight high (ONH) at $4,550.00.

Graphic: Supportive delta (i.e., committed buying as measured by volume delta or buying and selling power as calculated by the difference in volume traded at the bid and offer) in SPDR S&P 500 ETF Trust (NYSE: SPY), one of the largest ETFs that track the S&P 500 index, via Bookmap. The readings are supportive of initiative trade.

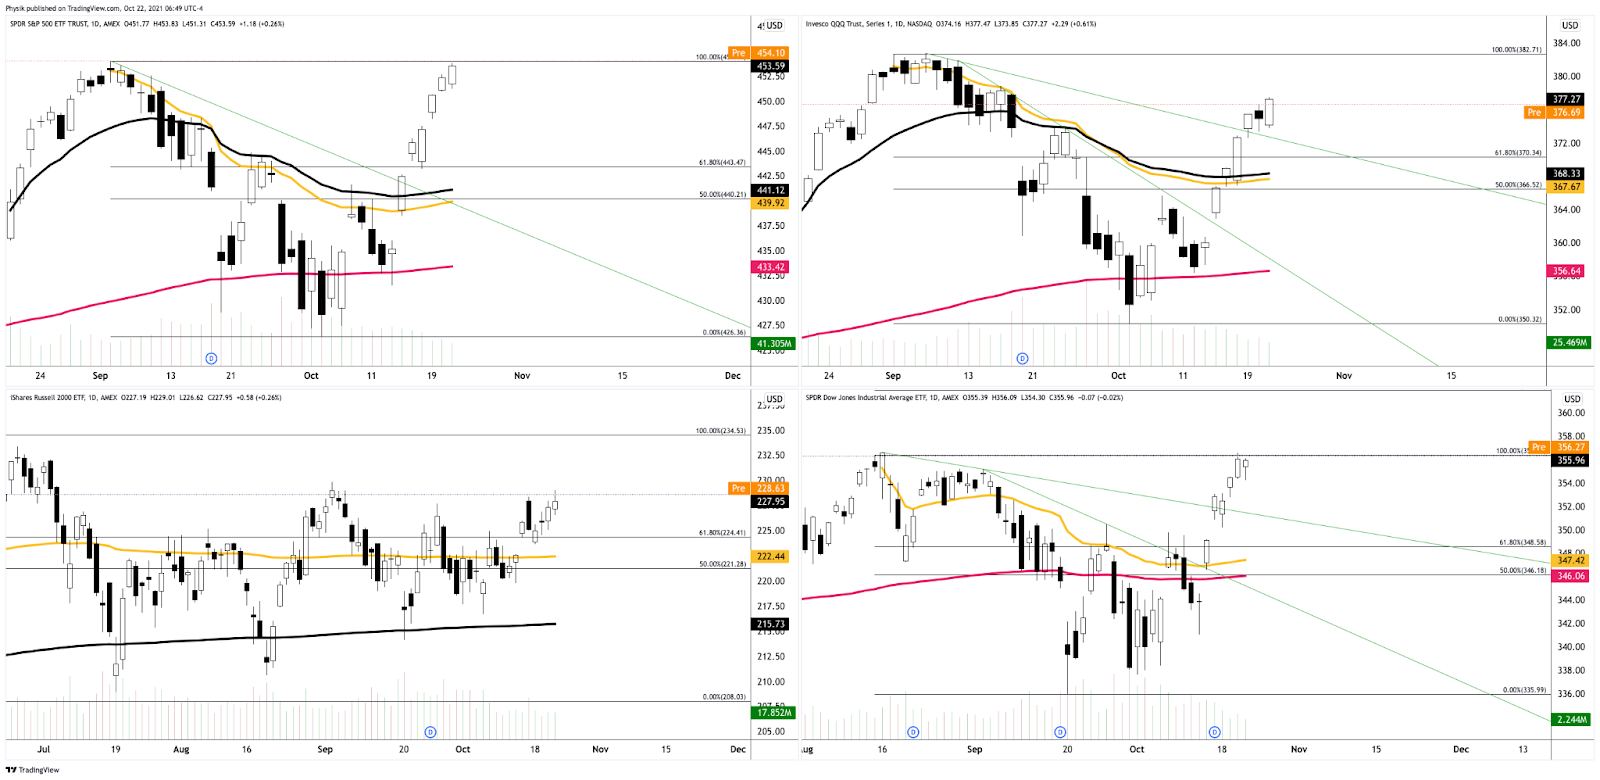
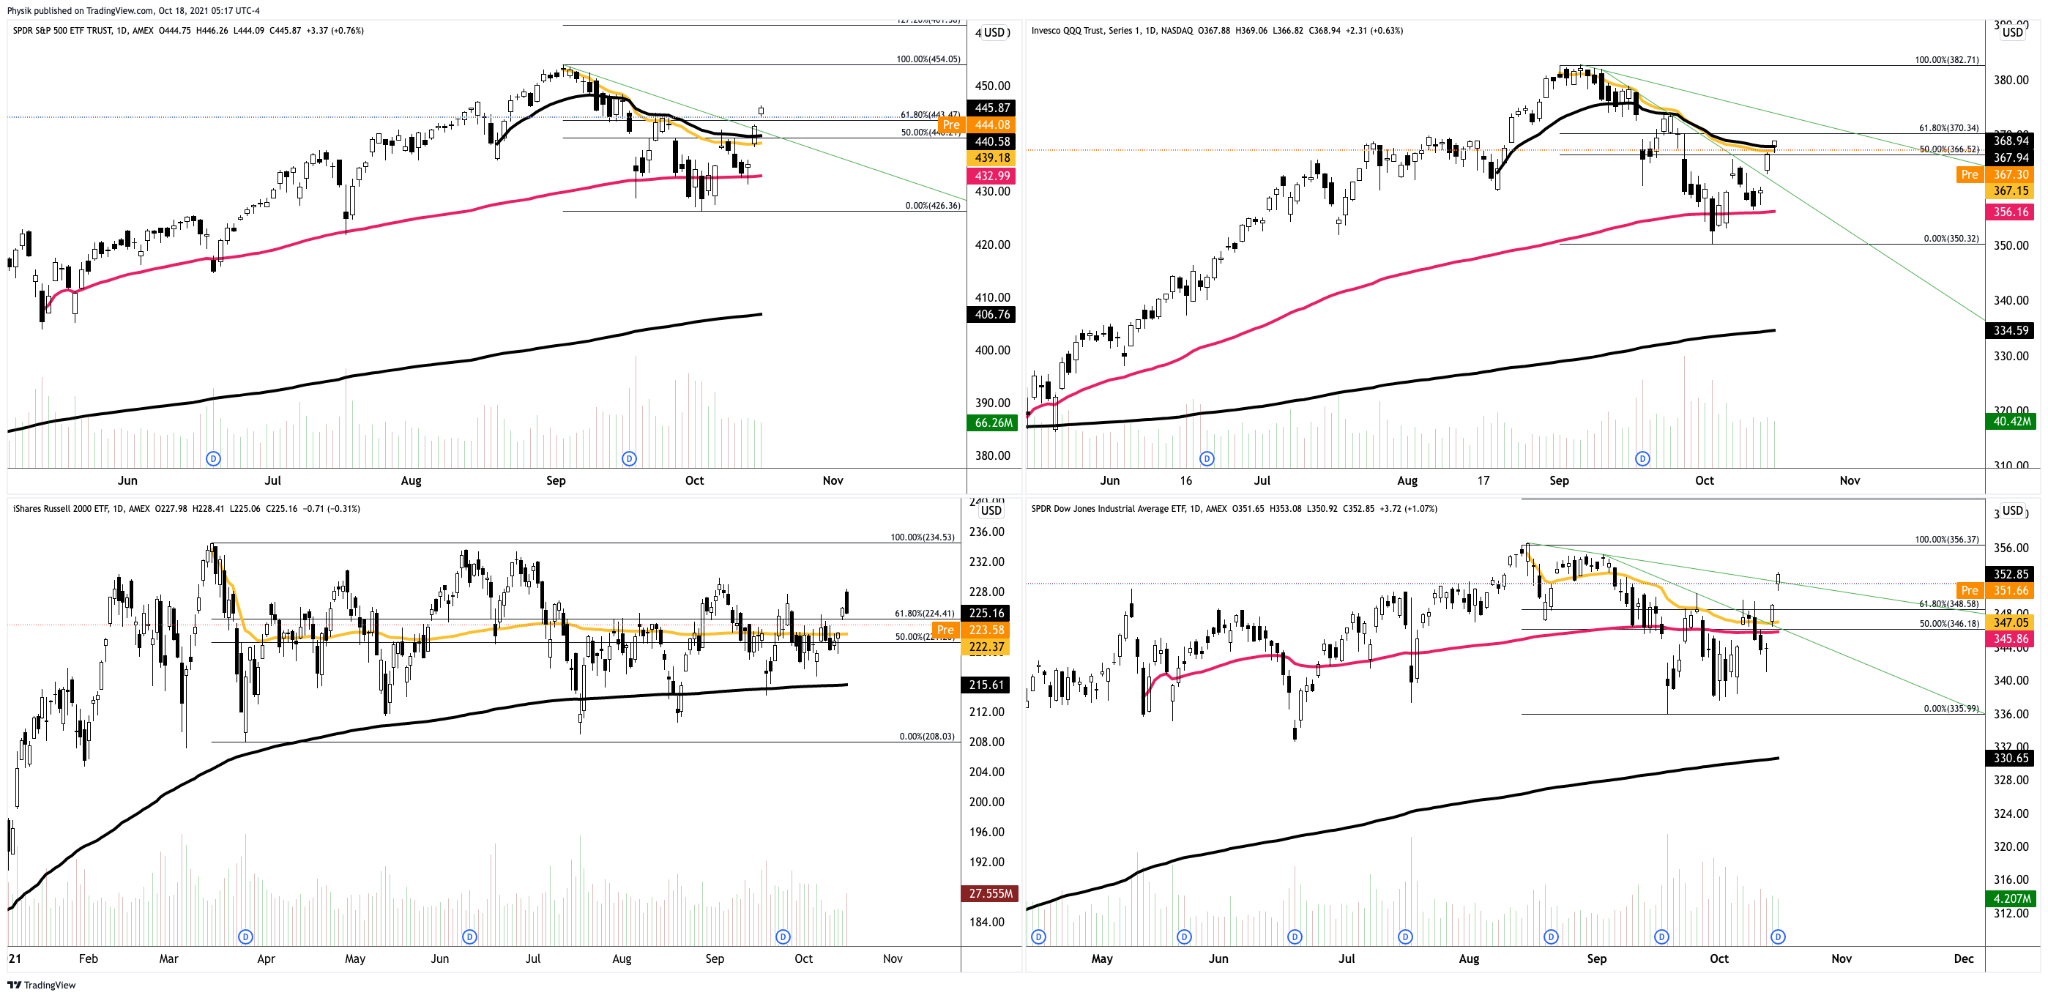
Zooming out, we see that though the Nasdaq 100 firmed this week, it did not recover as much ground as its peers, the S&P 500 and Dow Jones Industrial Average, both of which are trading at or above their all-time high figures. 

Graphic: SPDR S&P 500 ETF (NYSE: SPY) top left, Invesco QQQ Trust Series 1 (NASDAQ: QQQ) top right, iShares Russell 2000 ETF (NYSE: IWM) bottom left, SPDR Dow Jones Industrial Average ETF Trust (NYSE: DIA) bottom right.

This recovery has been swift and built on relatively poor – low volume – structures that ought to offer minimal support; what this simply means is that higher prices need validation.

Note: Value is defined by where 70% of the day’s trade happened, the bulk of where volume is. 

Think of the absence of high volume structures, on the way up, leaving no value to base off of. If prices are followed by value, that means that they are supported. If there is an open above (below) value, a market will auction lower (higher) in search of buyers (sellers). After auctioning too far from value, the response by higher timeframe participants will introduce single-print buying and selling tails as those participants look to take advantage of higher (lower) prices to sell (buy). 

Please read this excerpt from Mind Over Markets, for additional context.

Further, the aforementioned trade is happening in the context of improving breadth amidst a seasonally bullish cycle of contributions, rebalancing, and earnings, as well as the risks associated with a taper in asset purchases and a hike in rates.

In terms of positioning, the CBOE Volatility Index (INDEX: VIX) was lower, while the VIX futures term structure settled in contango; supply at the front end of the curve, alongside the long-gamma environment, signals a potential for near-term equity market stability.

According to SpotGamma analyses, this is where the so-called vanna (i.e., inflows as a result of options sliding down their term structure) dynamic comes to dominate. Adding, we look for increased interest in options strikes that are higher in price and further out in time.

Moreover, for today, participants may make use of the following frameworks.

In the best case, the S&P 500 trades sideways or higher; activity above the $4,525.00 untested point of control (VPOC) puts in play the $4,550.00 overnight high (ONH). Initiative trade beyond the ONH could reach as high as the $4,568.25 and $4,589.75 Fibonacci extensions, or higher.

In the worst case, the S&P 500 trades lower; activity below the $4,525.00 VPOC puts in play the $4,510.00 low volume area (LVNode). Initiative trade beyond the LVNode could reach as low as the $4,495.75 high volume area (HVNode) and $4,471.00 VPOC, or lower.

Click here to load today’s updated real-time key levels into the web-based TradingView charting platform. Please note that all levels are derived using the 65-minute timeframe.
Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures updated 6:30 AM ET.

Definitions

Cave-Fill Process: Widened the area deemed favorable to transact at by an increased share of participants. This is a good development.

Overnight Rally Highs (Lows): Typically, there is a low historical probability associated with overnight rally-highs (lows) ending the upside (downside) discovery process.

Volume Areas: A structurally sound market will build on areas of high volume (HVNodes). Should the market trend for long periods of time, it will lack sound structure, identified as low volume areas (LVNodes). LVNodes denote directional conviction and ought to offer support on any test. 

If participants were to auction and find acceptance into areas of prior low volume (LVNodes), then future discovery ought to be volatile and quick as participants look to HVNodes for favorable entry or exit.

POCs: POCs are valuable as they denote areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

Excess: A proper end to price discovery; the market travels too far while advertising prices. Responsive, other-timeframe (OTF) participants aggressively enter the market, leaving tails or gaps which denote unfair prices.

Ledges: Flattened area on the profile which suggests responsive participants are in control, or initiative participants lack the confidence to continue the discovery process. The ledge will either hold and force participants to liquidate (cover) their positions, or crack and offer support (resistance).

Volume-Weighted Average Prices (VWAPs): A metric highly regarded by chief investment officers, among other participants, for quality of trade. Additionally, liquidity algorithms are benchmarked and programmed to buy and sell around VWAPs.

News And Analysis

U.K. consumer confidence falls amidst cheerless news.

Growth digitalization of finance intensifying competition.

Supply issues could haunt the holidays after sales rise.

Substantial progress toward Fed’s mandates. Tapering?

Think everything’s expensive now? Wait there is more.

Big jump in home sales – impressive considering supply.

Biden: U.S. would defend Taiwan from attack by China.

Online wager, engagement key to sports betting growth.

What People Are Saying

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets. 

Additionally, Capelj is a finance and technology reporter. Some of his biggest works include interviews with leaders such as John Chambers, founder and CEO, JC2 Ventures, Kevin O’Leary, businessman and Shark Tank host, Catherine Wood, CEO and CIO, ARK Invest, among others.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.
Categories
Commentary

Daily Brief For October 18, 2021

Market Commentary

In sync with bonds, equity index futures were sideways to lower, overnight. Commodities were mixed. Volatility expanded.

  • More support for an EOY run-up.
  • Ahead is a light day for releases.
  • Positioned for sideways balance.

What Happened: U.S. stock index futures auctioned sideways to lower overnight alongside conflicting narratives.

Ahead is data on industrial production and capacity utilization (9:15 AM ET), as well as the National Association of Home Builders Index (10:00 AM ET).

Graphic updated 6:00 AM ET. Sentiment Neutral if expected /ES open is inside of the prior day’s range. Sentiment Risk-On if expected /ES open is above the prior day’s range. Sentiment Risk-Off if expected /ES open is below the prior day’s range. /ES levels are derived from the profile graphic at the bottom of the following section. Levels may have changed since initially quoted; click here for the latest levels. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. SHIFT data used for S&P 500 (INDEX: SPX) options activity. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect: As of 6:00 AM ET, Monday’s regular session (9:30 AM – 4:00 PM EST) in the S&P 500 may open inside of prior-range and -value, suggesting a limited potential for immediate directional opportunity.

Adding, during the prior day’s regular trade, on lackluster intraday breadth and market liquidity metrics, the best case outcome occurred, evidenced by an expansion of range above the $4,437.75 micro composite point of control (MCPOC), to a new overnight high (ONH) at $4,469.75.

Coupled with that dynamic is the presence of numerous gaps and p-shaped emotional, multiple-distribution profile structures (i.e., old-money shorts covering); participants will likely look to revisit, repair, and strengthen – build out areas of high volume (HVNodes) via the cave-fill process – these areas of low volume (LVNodes). 

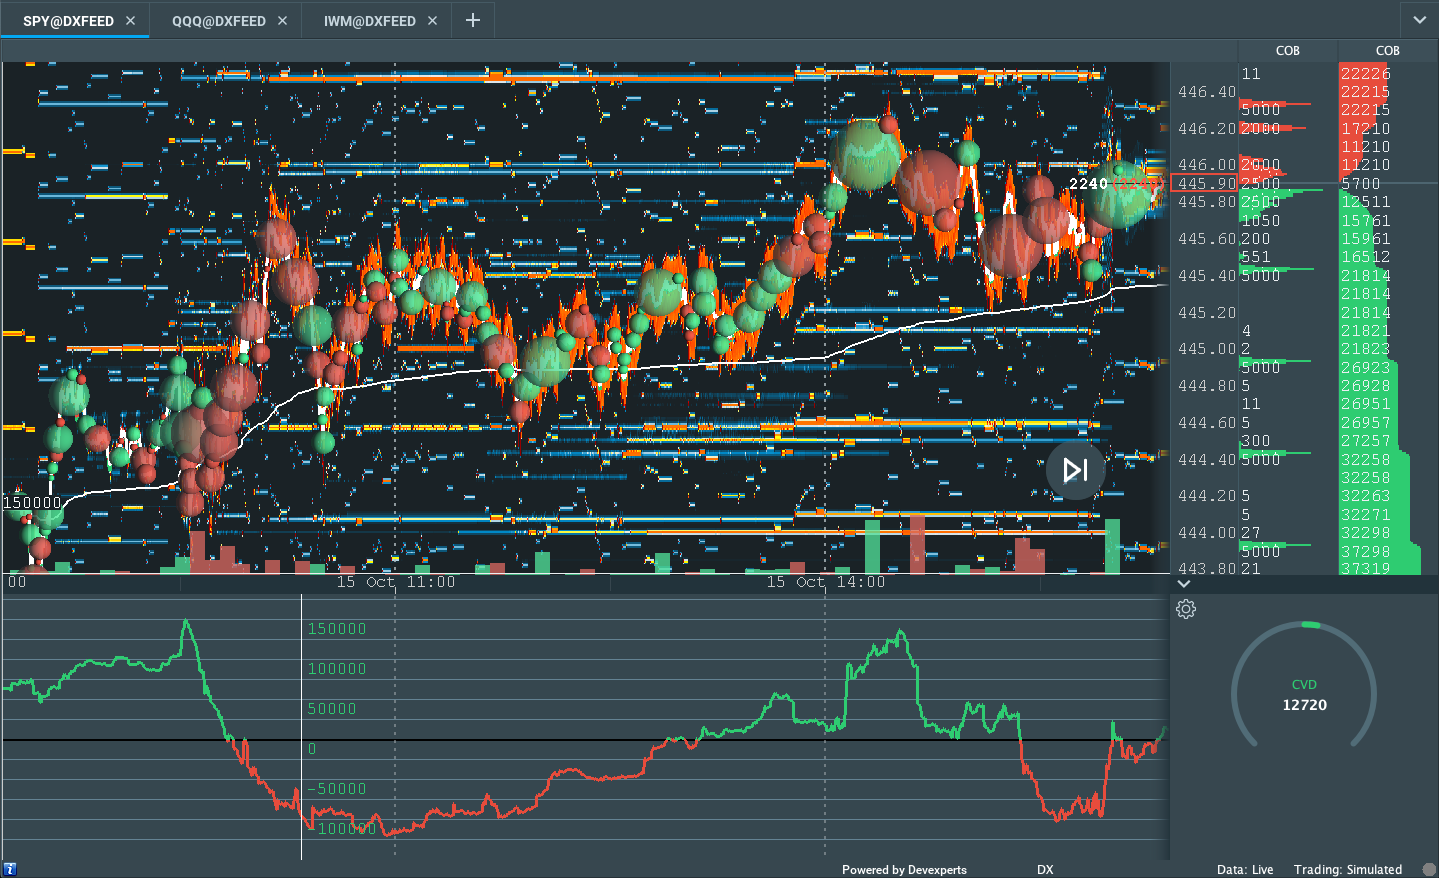
Graphic: Unsupportive delta (i.e., non-committed buying and selling as measured by volume delta or buying and selling power as calculated by the difference in volume traded at the bid and offer) in SPDR S&P 500 ETF Trust (NYSE: SPY), one of the largest ETFs that track the S&P 500 index, via Bookmap. The readings are supportive of responsive trade or balance (i.e., rotational trade that suggests current prices offer favorable entry and exit).

Zooming out, we saw the Nasdaq 100 firming, relative to its peers, last week, a significant change in tone.

Given where the S&P 500’s price is in relation to the yellow anchored volume-weighted average price (VWAP), the average buyer, since the all-time high, holds a winning position; sideways-to-higher trade, above the upward sloping trendline, as well as the 50.00% and 61.8% retracements, likely puts in play a recovery of the all-time high.

Graphic: SPDR S&P 500 ETF (NYSE: SPY) top left, Invesco QQQ Trust Series 1 (NASDAQ: QQQ) top right, iShares Russell 2000 ETF (NYSE: IWM) bottom left, SPDR Dow Jones Industrial Average ETF Trust (NYSE: DIA) bottom right.

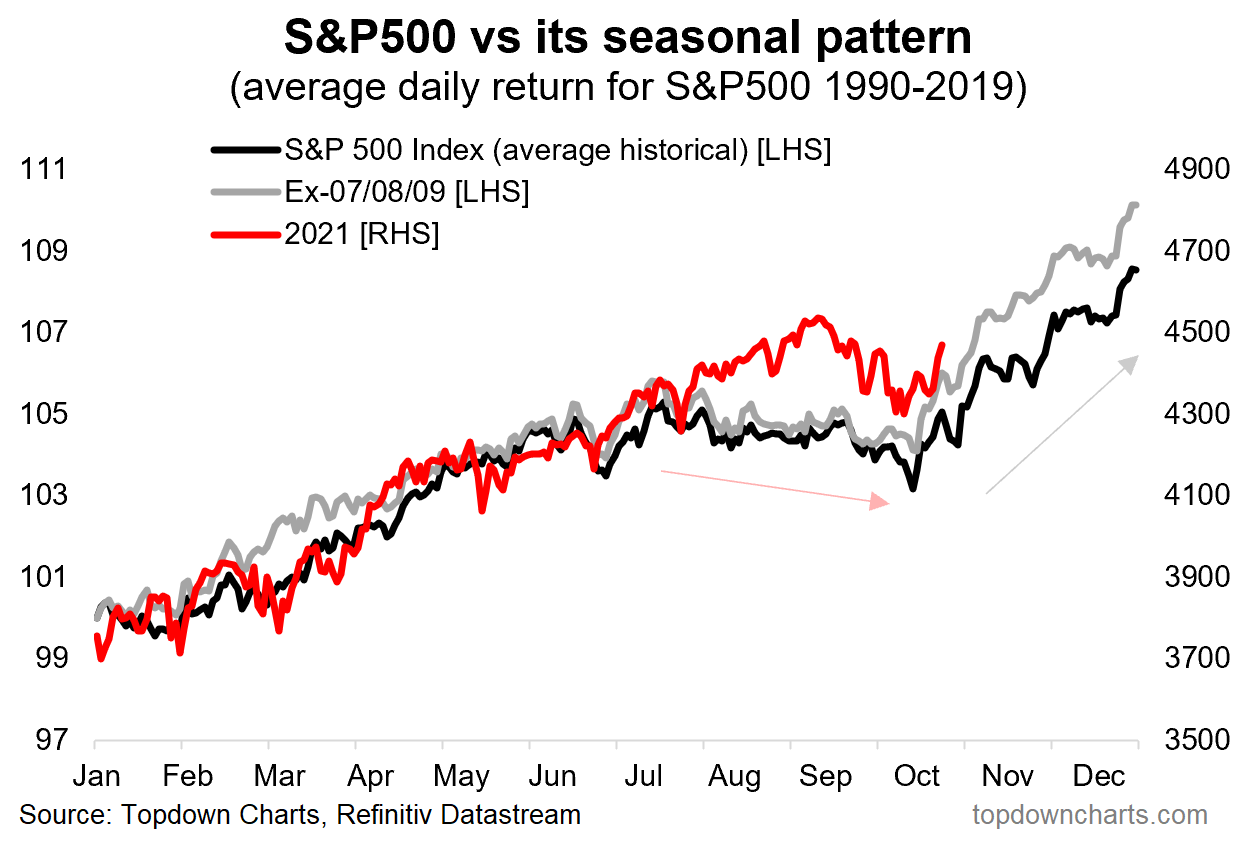
Further, the aforementioned trade is happening in the context of improving breadth amidst a seasonally bullish cycle of contributions, rebalancing, and earnings, as well as the risks associated with a taper in asset purchases and a hike in rates.

Graphic: S&P 500 seasonality via @topdowncharts

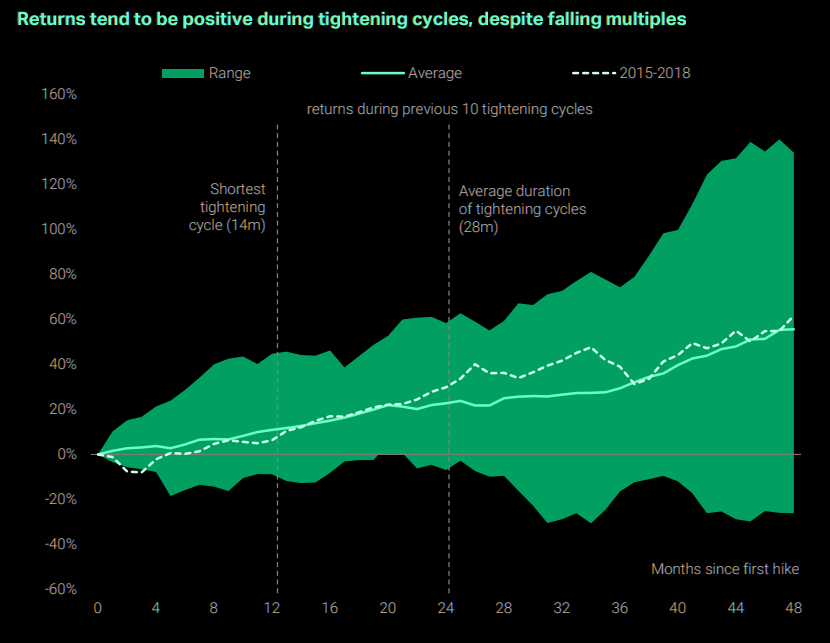
According to a TS Lombard note featured by The Market Ear, the odds are that a tightening in monetary policy should not douse the bullish narrative:

“Tightening monetary policy cycles have historically been positive for stocks. The exceptions were in the 1970s, when inflation was counter-cyclical and the Fed tightened despite slowing growth. In ‘regular’ cycles the Fed raises rates only when the economy (and corporate earnings) warrants a tighter policy stance. What is interesting is that positive returns happen despite falling P/E multiples. Higher rates tend to lead to falling valuations, but earnings growth is typically strong enough to compensate for the derating. Since multiples are still much higher than normal, favouring Growth (faster EPS growth) over Value (slower EPS growth) is a good strategy at this stage.”

Graphic: TS Lombard’s analysis of tightening cycles, via The Market Ear.

In terms of positioning, the CBOE Volatility Index (INDEX: VIX) was higher, overnight, while the VIX futures term structure was in contango; supply at the front end of the curve, alongside the long-gamma environment, signals a potential for near-term equity market stability.

To note, according to SpotGamma models, last week’s near-vertical price rise was responsively sold as dealers looked to hedge their increasing positive directional market exposure; going forward, hedging pressures may dampen volatility, potentially setting the market up for balance (i.e., sideways trade) as participants muster the conviction to initiate the next leg.

Moreover, for today, participants may make use of the following frameworks.

In the best case, the S&P 500 trades sideways or higher; activity above the $4,437.75 MCPOC puts in play the $4,463.75 low volume area (LVNode). Initiative trade beyond the LVNode could reach as high as the $4,481.75 high volume area (HVNode) and $4,510.00 LVNode, or higher.

In the worst case, the S&P 500 trades lower; activity below the $4,437.75 MCPOC puts in play the $4,425.00 untested point of control (VPOC). Initiative trade beyond the VPOC could reach as low as the $4,393.75 HVNode and $4,349.00 VPOC, or lower.

Click here to load today’s updated real-time key levels into the web-based TradingView charting platform. Please note that all levels are derived using the 65-minute timeframe.
Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures updated 5:15 AM ET.

Definitions

Overnight Rally Highs (Lows): Typically, there is a low historical probability associated with overnight rally-highs (lows) ending the upside (downside) discovery process.

Cave-Fill Process: Widened the area deemed favorable to transact at by an increased share of participants. This is a good development.

Volume Areas: A structurally sound market will build on areas of high volume (HVNodes). Should the market trend for long periods of time, it will lack sound structure, identified as low volume areas (LVNodes). LVNodes denote directional conviction and ought to offer support on any test. 

If participants were to auction and find acceptance into areas of prior low volume (LVNodes), then future discovery ought to be volatile and quick as participants look to HVNodes for favorable entry or exit.

Gamma: Gamma is the sensitivity of an option to changes in the underlying price. Dealers that take the other side of options trades hedge their exposure to risk by buying and selling the underlying. When dealers are short-gamma, they hedge by buying into strength and selling into weakness. When dealers are long-gamma, they hedge by selling into strength and buying into weakness. The former exacerbates volatility. The latter calms volatility.

POCs: POCs are valuable as they denote areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

MCPOCs: POCs are valuable as they denote areas where two-sided trade was most prevalent over numerous day sessions. Participants will respond to future tests of value as they offer favorable entry and exit.

Inversion Of VIX Futures Term Structure: Longer-dated VIX expiries are less expensive; is a warning of elevated near-term risks for equity market stability.

Balance (Two-Timeframe Or Bracket): Rotational trade that denotes current prices offer favorable entry and exit. Balance-areas make it easy to spot a change in the market (i.e., the transition from two-time frame trade, or balance, to one-time frame trade, or trend). 

Modus operandi is responsive trade (i.e., fade the edges), rather than initiative trade (i.e., play the break).

More On Volume-Weighted Average Prices (VWAPs): A metric highly regarded by chief investment officers, among other participants, for quality of trade. Additionally, liquidity algorithms are benchmarked and programmed to buy and sell around VWAPs.

Rates: Low rates have to potential to increase the present value of future earnings making stocks, especially those that are high growth, more attractive. To note, inflation and rates move inversely to each other. Low rates stimulate demand for loans (i.e., borrowing money is more attractive). In conjunction with the rapid recovery, lower rates may solicit hawkish commentary as policymakers look to inhibit inflation.

News And Analysis

Forbearances declining faster, plans drop by 10%.

Morgan Stanley CEO is calling for Fed rate hiking.

Analysts warn that 60/40 portfolio will be battered.

Moody’s: Fundamental siding with Fed on inflation.

S&P Global: Data on job gains has come up short.

Global energy turning to fossil fuels amid demand.

How the asset management industry got disrupted.

What People Are Saying

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets. 

Additionally, Capelj is a finance and technology reporter. Some of his biggest works include interviews with leaders such as John Chambers, founder and CEO, JC2 Ventures, Kevin O’Leary, businessman and Shark Tank host, Catherine Wood, CEO and CIO, ARK Invest, among others.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.
Categories
Commentary

Weekly Brief For September 19, 2021

Editor’s Note: Late today. So sorry! The main takeaway is that we’re in a window of volatility and participants should focus on leveraging rich skew and complex spreads to hedge or speculate on sideways to lower trade.

Market Commentary

  • SPX below balance, 50-day SMA.
  • Ahead is a 2-day FOMC meeting.
  • Concerns around the debt ceiling.
  • Rich skew makes hedging easier.
  • Post OPEX volatility likely in play.

What Happened: U.S. stock index futures auctioned lower, last week, into Friday’s quadruple witching derivatives expiry. 

Of interest this week is a meeting of the Federal Open Market Committee (FOMC).

Graphic updated 5:30 PM ET Sunday. Sentiment Neutral if expected /ES open is inside of the prior day’s range. /ES levels are derived from the profile graphic at the bottom of the following section. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. SHIFT data used for S&P 500 (INDEX: SPX) options activity. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect: During the prior week’s trade, on weak breadth, the worst-case outcome occurred, evidenced by a balance-area breakout and separation of value below the S&P 500’s 50-day simple moving average (i.e., a visual level likely paid attention to by short-term, technically-driven market participants who generally are unable to defend retests).

Balance-Break Scenarios: A change in the market (i.e., the transition from two-time frame trade, or balance, to one-time frame trade, or trend) has occurred.

We now monitor for rejection (i.e., return inside of balance) which portends a move to the opposite end of the balance.

Further, the aforementioned trade is happening in the context of a waning economic recovery, heightened valuations in the face of strong EPS expectations, the prospects of stimulus reduction, non-seasonally aligned flows, impactful options and equity market dynamics, divergent sentiment, as well as fears of a mid-cycle transition.

In a Goldman Sachs Group Inc (NYSE: GS) note posted by The Market Ear, analysts “believe it is a critical period for many investors and companies that manage performance to calendar year-end. Such pressures boost volumes and volatility as investors observe earnings reports, analyst days and managements’ guidance for the following year.”

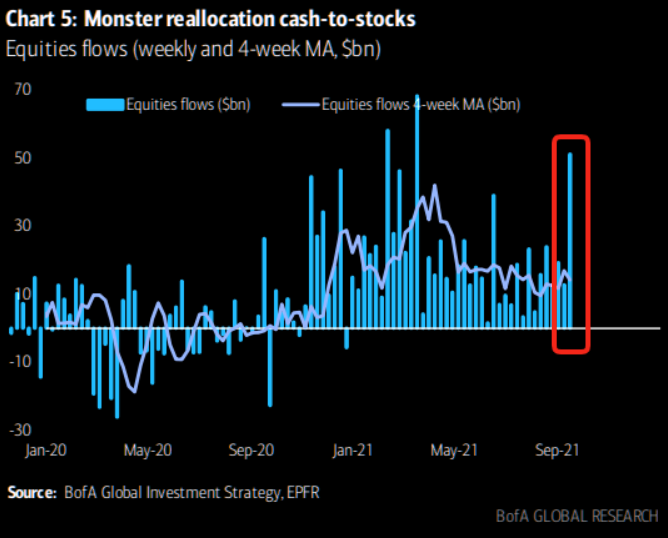
At the same time, inflows into equities are exploding to the upside as JPMorgan Chase & Co (NYSE: JPM) technicians “do not see a pattern on the [S&P 500] chart or any cross-market dynamics that would suggest the market is set for a lasting bearish reversal. The late-Aug systematic sell signals lose statistical significance into next week and the seasonal trends improve into early-Oct.”

Graphic: Bank of America Corporation (NYSE: BAC) charts equity flows, via The Market Ear.

That said, we hone in on risks.

If concerns like the debt ceiling are not resolved, some economists argue, according to Bloomberg, “that an announcement on tapering is likely to be delayed to December, and that Treasury yields could fall further as a result.”

We note that – as Goldman Sachs writes – “The upcoming debt limit deadline is beginning to look as risky as the 2011 debt limit showdown that led to Standard & Poor’s downgrade of the US sovereign rating and eventually to budget sequestration, or the 2013 deadline that overlapped with a government shutdown.”

On the other hand, according to SqueezeMetrics, “the current combination of weak put flows and large customer vanna exposure” is fragile; “people are [still] overexposed to changes in VIX, and will be hurt more than usual if VIX starts moving up. Historically, this means SPX down, VIX up.”

Following SqueezeMetrics’ remarks, SpotGamma adds that “over 50% of stocks [had] their largest gamma position” roll-off Friday. This suggests an increased potential for volatility heading into the September 21-22 FOMC event.

In this post-quad-witching window of non-strength, we may, as a result, use the rich skew to hedge (see below Weekly Trade Idea section).

Moreover, for today, given an increased potential for heightened volatility and initiative trade, participants may make use of the following frameworks.

In the best case, the S&P 500 trades sideways or higher; activity above the $4,437.75 micro-composite point of control (MCPOC) puts in play the $4,481.75 high volume area (HVNode). Initiative trade beyond the $4,481.75 HVNode could reach as high as the $4,510.00 low volume area (LVNode) and $4,526.25 HVNode, or higher.

In the worst case, the S&P 500 trades lower; activity below the $4,437.75 MCPOC puts in play the $4,393.75 HVNode. Initiative trade beyond the $4,393.75 HVNode could reach as low as the $4,365.25 LVNode and $4,341.00 untested point of control (VPOC), or lower.

We note that the $4,481.75 and $4,393.75 HVNodes intersect key anchored volume-weighted average price levels. These are metrics highly regarded by chief investment officers, among other participants, for quality of trade. Additionally, liquidity algorithms are benchmarked and programmed to buy and sell around VWAPs.

Graphic: 4-hour profile chart of the Micro E-mini S&P 500 Futures updated 5:30 PM ET Sunday.

Key Definitions

Volume Areas: A structurally sound market will build on areas of high volume (HVNodes). Should the market trend for long periods of time, it will lack sound structure, identified as low volume areas (LVNodes). LVNodes denote directional conviction and ought to offer support on any test. 

If participants were to auction and find acceptance into areas of prior low volume (LVNodes), then future discovery ought to be volatile and quick as participants look to HVNodes for favorable entry or exit.

POCs: POCs are valuable as they denote areas where two-sided trade was most prevalent in a prior day session. Participants will respond to future tests of value as they offer favorable entry and exit.

MCPOCs: POCs are valuable as they denote areas where two-sided trade was most prevalent over numerous day sessions. Participants will respond to future tests of value as they offer favorable entry and exit.

Weekly Trade Idea

Please Note: In no way is the below a trade recommendation. Derivatives carry a substantial risk of loss. All content is for informational purposes only.

Options offer an efficient way to gain directional exposure. 

If an option buyer was short (long) stock, he or she could buy a call (put) to hedge upside (downside) exposure. Additionally, one can spread, or buy (+) and sell (-) options together, strategically.

Commonly discussed spreads include credit, debit, ratio, back, and calendar.

  • Credit: Sell -1 option closer to the money. Buy +1 option farther out of the money.
  • Debit: Buy +1 option closer to the money. Sell -1 option farther out of the money.
  • Ratio: Buy +1 option closer to the money. Sell -2 options farther out of the money. 
  • Back: Sell -1 option closer to the money. Buy +2 options farther out of the money.
  • Calendar: Sell -1 option. Buy +1 option farther out in time, at the same strike.

Typically, if bullish (bearish), sell at-the-money put (call) credit spread and/or buy a call (put) debit/ratio spread structured around target price. Alternatively, if the expected directional move is great (small), opt for a back spread (calendar spread). Also, if credit spread, capture 50-75% of the premium collected. If debit spread, capture 2-300% of the premium paid.

Be cognizant of risk exposure to direction (delta), time (theta), and volatility (vega). 

  • Negative (positive) delta = synthetic short (long). 
  • Negative (positive) theta = time decay hurts (helps).
  • Negative (positive) vega = volatility hurts (helps).

Trade Idea: SELL -1 1/2 BACKRATIO SPX 100 (Weeklys) 29 SEP 21 4400/4300 PUT @.65 CREDIT LMT

I’m neutral to bearish on the S&P 500 and I think the index may slide toward $4,300. I will structure a spread below the current index price, expiring in about 2 weeks. I will buy the 4400 put option once (+1) and sell the 4300 put option twice (-2) for a $0.65 credit. Should the index not move to my target, I keep the $65 credit. Should it move to $4,300, I could make $10,065.00 at expiry. Should the index move past $4,200.00 or so, I may incur unlimited losses. My goal, with this spread, is to capture the initial credit and close for additional credit if the index moves lower. 

If necessary, I will hedge the position by either (A) selling futures, (B) widening strikes, (C) buying a far out-of-the-money put option to cap downside in case of an unpredictable move lower, or (D) roll strikes down in price and out in time.

News And Analysis

An essay on why you keep losing money as a trader.

August retail sales reflect strong consumer demand.

UBS: Resist temptation to time market despite highs.

U.S. debt ceiling fight could cause markets to tumble.

Nasdaq on whether Rule 605 works better in dollars.

Rally driven less by reflation prospects; TINA to stock.

Higher U.S. CGT proposal spurs a PE and M&A rush.

If a CEO talks like Kant, think twice before investing.

New vehicle prices surge amid global chip shortages.

Active managers’ performance disappointing in 2021.

DeFi is disrupting but not derailing traditional finance.

OpenSea admitted recent incident as insider trading.

SEC looks to greater oversight of the crypto markets.

Central bank digital currency; cash for the digital age.

White House to put forward three CFTC nominations.

Some key lessons from NYC’s first SALT conference. 

Let’s Hang Out

Salt Lake City, UT September 28-30

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets. 

Additionally, Capelj is a finance and technology reporter. Some of his biggest works include interviews with leaders such as John Chambers, founder and CEO, JC2 Ventures, Kevin O’Leary, businessman and Shark Tank host, Catherine Wood, CEO and CIO, ARK Invest, among others.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.
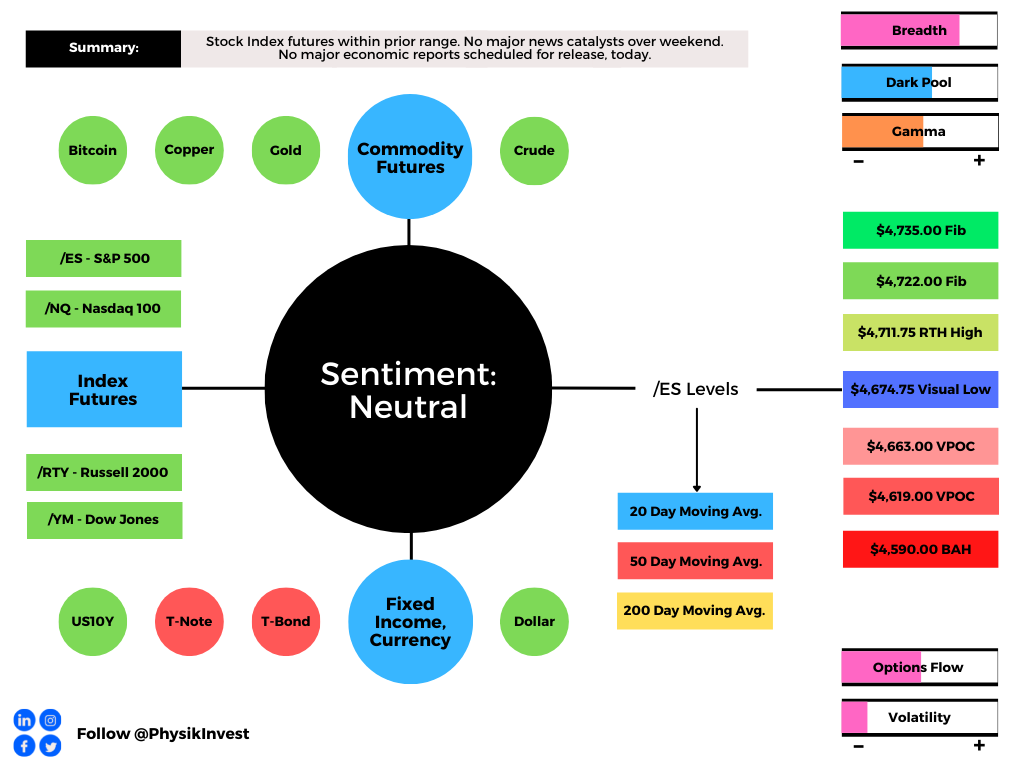
Categories
Commentary

Daily Brief For September 1, 2021

Market Commentary

Equity index futures trade sideways to higher overnight. VIX, bonds, dollar were all lower.

  • Inflows and options and peak growth, oh my!
  • Ahead: Employment and manufacturing data.
  • Indexes are positioned for directional resolve.

What Happened: U.S. stock index futures auctioned sideways to higher overnight as participants get past reports of European hawkishness, as well as position for directional resolve on the basis of new fundamental data.

Ahead is data on ADP employment (8:15 AM ET), Markit manufacturing PMI (9:45 AM ET), ISM manufacturing index, and construction spending (10:00 AM ET).

Graphic updated 6:30 AM ET. Sentiment Risk-On if expected /ES open is above the prior day’s range. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. SHIFT data used for S&P 500 (INDEX: SPX) options activity approximation. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect: As of 6:30 AM ET, Wednesday’s regular session (9:30 AM – 4:00 PM EST) in the S&P 500 will likely open outside of prior-range and -value, suggesting a potential for immediate directional opportunity.

Adding, during the prior day’s regular trade, on positive but weak intraday breadth and middling market liquidity metrics, the best case outcome occurred, evidenced by trade within Monday’s range. This is significant because it was a validation of Monday’s emotional price discovery.

Graphic: Divergent delta (i.e., non-committed buying as measured by volume delta or buying and selling power as calculated by the difference in volume traded at the bid and offer) in SPDR S&P 500 ETF Trust (NYSE: SPY), one of the largest ETFs that track the S&P 500 index, via Bookmap. The readings are supportive of responsive trade or balance (i.e., rotational trade that suggests current prices offer favorable entry and exit). 
Graphic: Market Internals (Advance/Decline, Up-Volume/Down-Volume, Tick) displayed as Peter Reznicek at ShadowTrader teaches. Though positive, readings were weak and supportive of responsive trade, similar to what market liquidity (via Bookmap) was showing.
Gap Scenarios In Play: Gaps ought to fill quickly. Should they not, that’s a signal of strength; do not fade. Leaving value behind on a gap-fill or failing to fill a gap (i.e., remaining outside of the prior session’s range) is a go-with indicator.

Auctioning and spending at least 1-hour of trade back in the prior range suggests a lack of conviction; in such a case, do not follow the direction of the most recent initiative activity.

Further, the aforementioned responsive trade is happening in the context of peak growth and a moderation in the economic recovery, as well as some of the dynamics unpacked in-depth yesterday (e.g., non-seasonally aligned inflows, impactful options market dynamics, divergent sentiment, and fears of a mid-cycle transition). 

The implications of these themes on price are contradictory; to elaborate, on one hand, yes, inflows and divergent sentiment are a green light with respect to the advance in equities (i.e., markets tend to climb a wall of worry given – all else equal – a decay in options skew and removal of hedges, among other things). 

“I use this analogy of a jet,” Kai Volatility’s Cem Karsan explained, referencing the three factors – the change in the underlying price (gamma), implied volatility (vanna), and time (charm) – that are well known to impact an options exposure to directional risk or delta. “As volatility is compressed, those jets will keep firing because … the hedging vanna and charm flows, and whatnot will push the markets higher.”

On the other hand, as Moody’s Corporation (NYSE: MCO) believes, “The Dow is forecast to have peaked and will gradually decline during the next year. Risks are heavily weighted to the upside, but peak growth, inflation and Fed tapering could weigh on equity markets.”

Graphic: Bloomberg data on S&P 500 seasonality.

Moreover, for today, given the increased potential for balanced trade, participants may make use of the following frameworks.

In the best case, the S&P 500 trades sideways or higher; activity above the $4,529.25 low volume area (LVNode) pivot puts in play the $4,542.25 overnight high (ONH). Initiative trade beyond the ONH could reach as high as the $4,556.25 and $4,592.25 Fibonacci extensions.

In the worst case, the S&P 500 trades lower; activity below the $4,529.25 LVNode puts in play the $4,521.00 untested point of control (VPOC). Initiative trade beyond the VPOC could reach as low as the $4,510.00 figure (which corresponds with a regular-trade high and small gap) and $4,481.75 HVNode.

Overnight Rally Highs (Lows): Typically, there is a low historical probability associated with overnight rally-highs (lows) ending the upside (downside) discovery process.

Volume Areas: A structurally sound market will build on past areas of high volume. Should the market trend for long periods of time, it will lack sound structure (identified as a low volume area which denotes directional conviction and ought to offer support on any test). 

If participants were to auction and find acceptance into areas of prior low volume, then future discovery ought to be volatile and quick as participants look to areas of high volume for favorable entry or exit.

POCs: POCs are valuable as they denote areas where two-sided trade was most prevalent. Participants will respond to future tests of value as they offer favorable entry and exit.

Balance (Two-Timeframe Or Bracket): Rotational trade that denotes current prices offer favorable entry and exit. Balance-areas make it easy to spot a change in the market (i.e., the transition from two-time frame trade, or balance, to one-time frame trade, or trend). 

Modus operandi is responsive trade (i.e., fade the edges), rather than initiative trade (i.e., play the break).
Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures updated 6:30 AM ET. Note the developing balance area (HVNode) surrounding just short of the ONH. 

News And Analysis

Home prices continue to gain, more double-digit growth.

There is no such thing as an independent central bank.

Beginning to see churn below the surface amid outlook.

Shell plans to install 50,000 U.K. on-street EV chargers.

China manufacturing slows first time since March 2020.

Wall Street traders driving record are loaded on hedges. 

China Evergrande says construction of projects stalled.

‘Forever Changed’: CEOs are dooming business travel.

SEC boss: Crypto platforms need regulation to survive.

‘Egregiously mishandled’: Afghanistan dents Biden team.

SEC boss: Banning Payment for Order Flow is on table.

Euro-area inflation may justify end to ECB’s crisis mode.

What People Are Saying

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets. 

Additionally, Capelj is a finance and technology reporter. Some of his biggest works include interviews with leaders such as John Chambers, founder and CEO, JC2 Ventures, Kevin O’Leary, businessman and Shark Tank host, Catherine Wood, CEO and CIO, ARK Invest, among others.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.
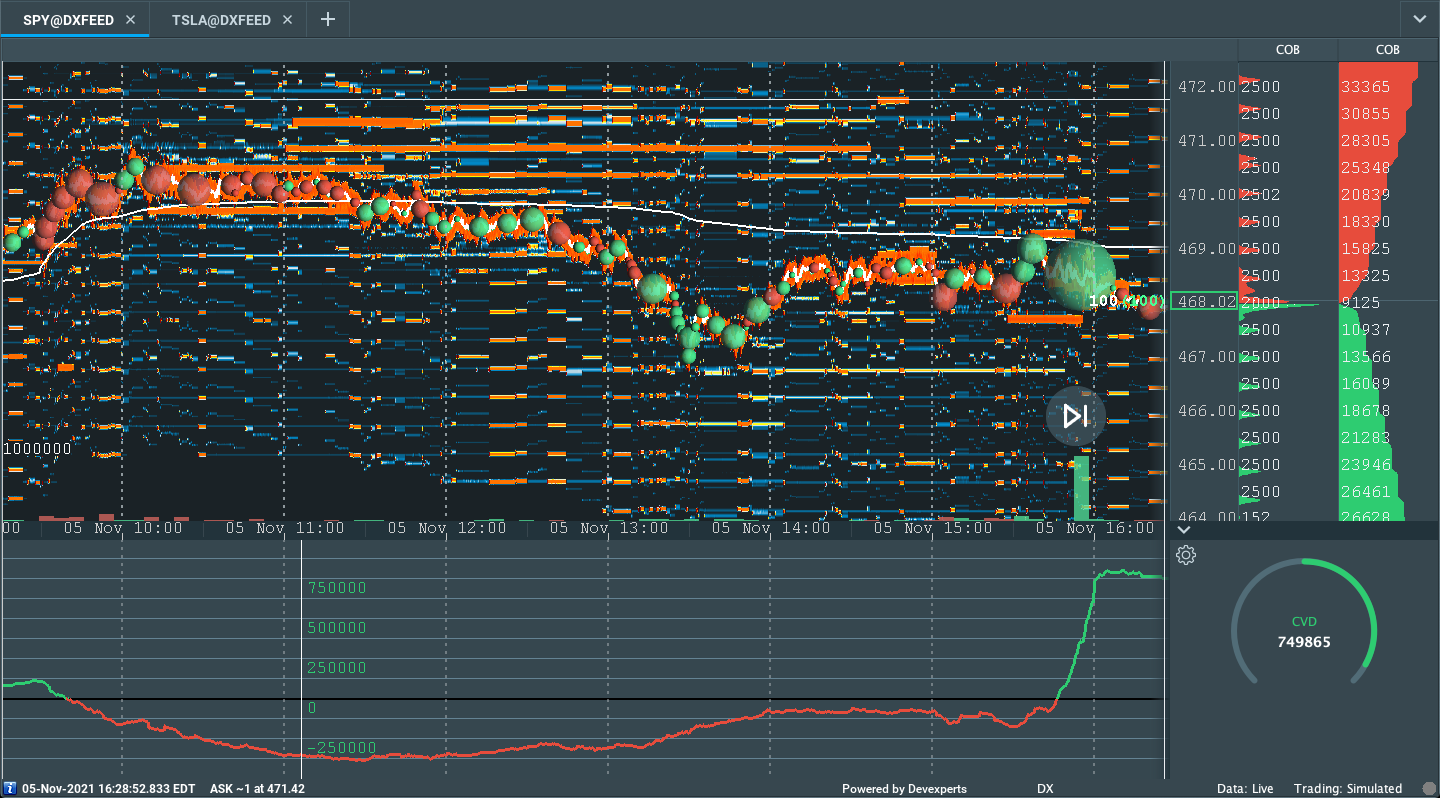
Categories
Commentary

Daily Brief For August 31, 2021

Market Commentary

Equity index futures, VIX sideways to higher. Commodities, bonds, dollar lower.

  • Ahead: Home prices, PMI, and more.
  • The path of least resistance is higher.

What Happened: U.S. stock index futures auctioned sideways to higher overnight alongside an absence in fundamental catalysts.

Ahead is data on the Case-Shiller national home price index (9:00 AM ET), Chicago PMI (9:45 AM ET), and consumer confidence index (10:00 AM ET).

Graphic updated 6:30 AM ET. Sentiment Neutral if expected /ES open is inside of the prior day’s range. SqueezeMetrics Dark Pool Index (DIX) and Gamma (GEX) calculations are based on where the prior day’s reading falls with respect to the MAX and MIN of all occurrences available. A higher DIX is bullish. At the same time, the lower the GEX, the more (expected) volatility. SHIFT data used for S&P 500 (INDEX: SPX) options activity approximation. Note that options flow is sorted by the call premium spent; if more positive then more was spent on call options. Breadth reflects a reading of the prior day’s NYSE Advance/Decline indicator. VIX reflects a current reading of the CBOE Volatility Index (INDEX: VIX) from 0-100.

What To Expect: As of 6:30 AM ET, Tuesday’s regular session (9:30 AM – 4:00 PM EST) in the S&P 500 will likely open inside of prior-range and -value, suggesting a limited potential for immediate directional opportunity.

Adding, during the prior day’s regular trade, on weak intraday breadth and middling market liquidity metrics, the best case outcome occurred, evidenced by further price discovery. 

Price Discovery (One-Timeframe Or Trend): Market seeking new prices to establish value, or acceptance (i.e., more than 30-minutes of trade at a particular price level). 

Despite the low volume, p-shaped profile structures (which denote short covering), and a lack of intraday range expansion, the aforementioned trade is significant because it suggests continued bullishness after a v-pattern recovery.

V-Pattern: A pattern that forms after a market establishes a high, retests some support, and then breaks above said high. In most cases, this pattern portends continuation.

Further, the aforementioned trade is happening in the context of non-seasonally aligned inflows, impactful options market dynamics, divergent sentiment, and fears of a mid-cycle transition. 

The implications of these themes on price are contradictory; to elaborate, on one hand, August, over the past 25 years, has historically been the largest month for equity outflows. According to Goldman Sachs Group Inc’s (NYSE: GS) Scott Rubner, “We have seen none of these outflows and it has been buying the dip (TINA).”

Given this divergence from the norm, an advance (such as the one we’re in presently) is not “welcomed and may lead to a quick right tail edging … [as] option volume notional is 120% of stock volume notional.”

To put it simply, 75% of the options being traded expire within two weeks. The related hedging flows of these directionally sensitive options can represent an increased share of volume in underlying stocks.

To put it simply, option flows impact the underlying’s price, markedly.

We couple this so-called right-tail hedging with the structural positioning that drives the market through the three factors – the change in the underlying price (gamma), implied volatility (vanna), and time (charm) – that are well known to impact an options exposure to directional risk or delta.

“Charm is a major driver for support in the markets,” said Cem Karsan of Kai Volatility Advisors. “All of that support is leading up to and accelerating into that Monday-Wednesday window” ahead of OpEx. “And then the window really opens for lack of support. It’s not like there’s a bunch of selling all of a sudden. It’s a window of non-strength; a lack of these supportive flows that have been there prior.”

With the August monthly options expiration (OPEX) behind, the focus shifts to September, at and around the same time Morgan Stanley’s (NYSE: MS) Michael Wilson expects a formal signal – which would align with Karsan’s window of non-strength – on the taper of asset purchases, leading to a mid-cycle transition and 10% S&P 500 correction.

Options Expiration (OPEX): Option expiries mark an end to pinning (i.e, the theory that market makers and institutions short options move stocks to the point where the greatest dollar value of contracts will expire worthless) and the reduction dealer gamma exposure.

“Assuming a stable equity risk premium at 345bp, P/Es would fall to 19x, or 10% lower.”

Graphic: Morgan Stanley unpacks mid-cycle transition thesis. Image retrieved from ZeroHedge.

Moreover, for today, participants may make use of the following frameworks.

In the best case, the S&P 500 trades sideways or higher; activity above the $4,524.00 low volume area (LVNode) pivot puts in play the $4,542.25 overnight high (ONH). Initiative trade beyond the ONH could reach as high as the $4,556.25 and $4,592.25 Fibonacci extensions.

In the worst case, the S&P 500 trades lower; activity below the $4,524.00 LVNode puts in play $4,510.00, the convergence of a regular-trade high and LVNode. Initiative trade beyond the $4,510.00 figure could reach as low as the $4,481.75 high volume area (HVNode) and $4,454.25 LVNode.

To note, the $4,454.25 LVNode corresponds with an anchored volume-weighted average price (VWAP), a metric highly regarded by chief investment officers, among other participants, for quality of trade. Additionally, liquidity algorithms are benchmarked and programmed to buy and sell around VWAPs.

Overnight Rally Highs (Lows): Typically, there is a low historical probability associated with overnight rally-highs (lows) ending the upside (downside) discovery process.

Volume Areas: A structurally sound market will build on past areas of high volume. Should the market trend for long periods of time, it will lack sound structure (identified as a low volume area which denotes directional conviction and ought to offer support on any test). 

If participants were to auction and find acceptance into areas of prior low volume, then future discovery ought to be volatile and quick as participants look to areas of high volume for favorable entry or exit.
Graphic: 65-minute profile chart of the Micro E-mini S&P 500 Futures updated 6:30 AM ET.

News And Analysis

Inventories continue to constrain home purchase activity.
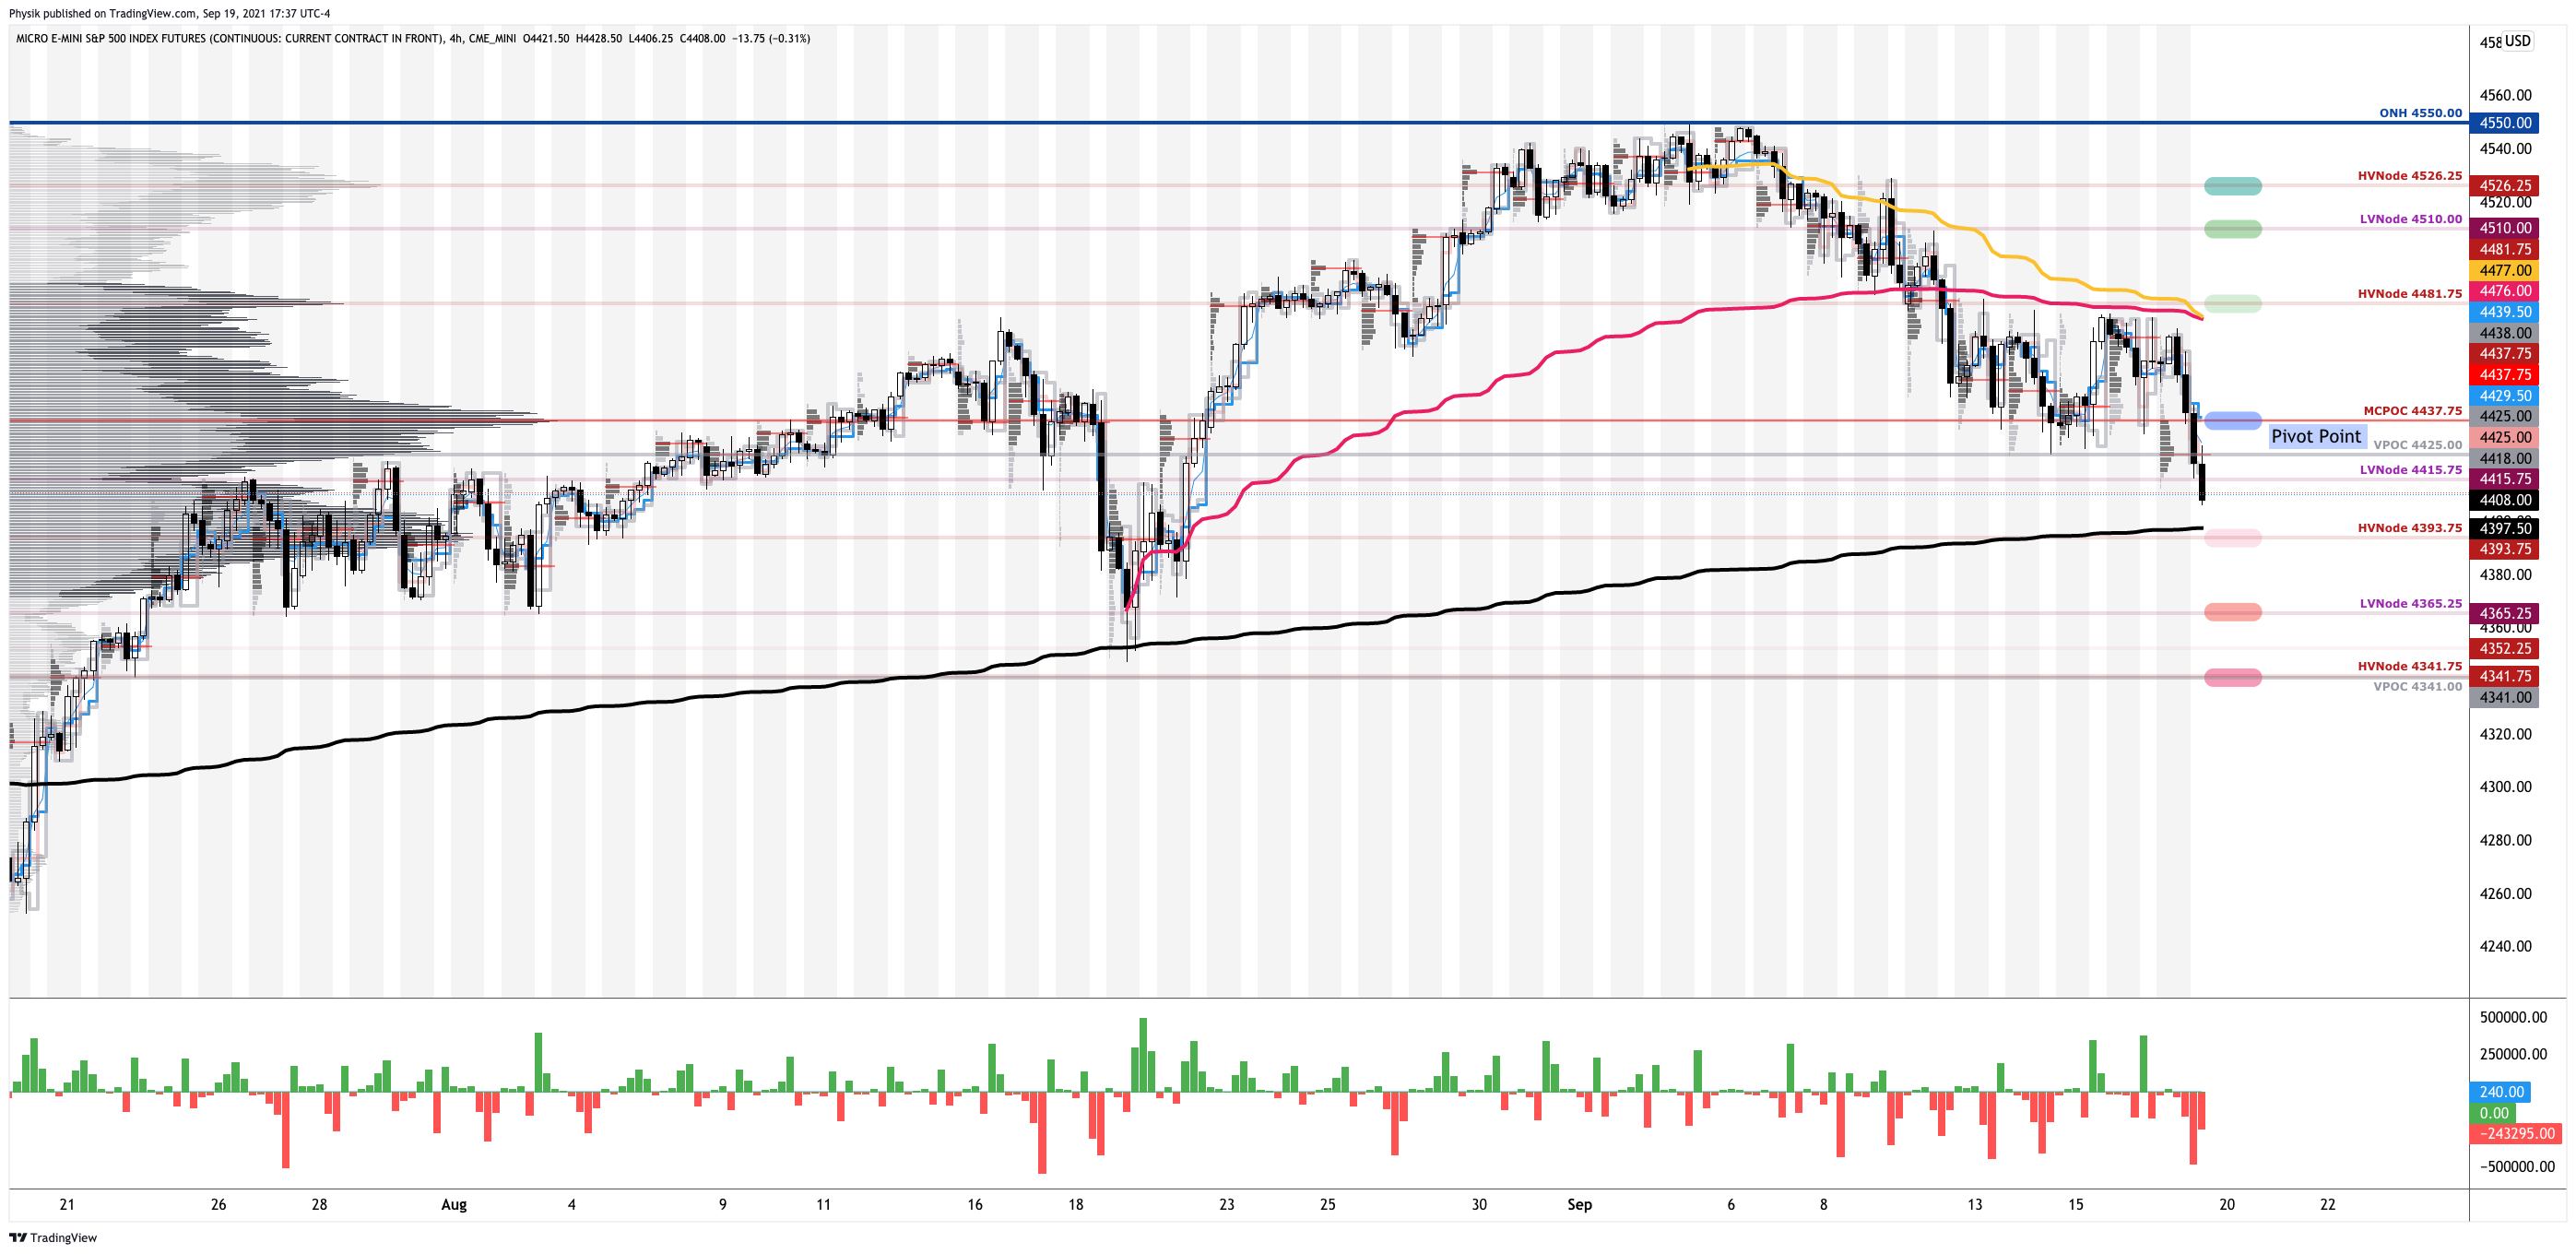
The Fed now risking too-slow taper after too-fast in 2013.
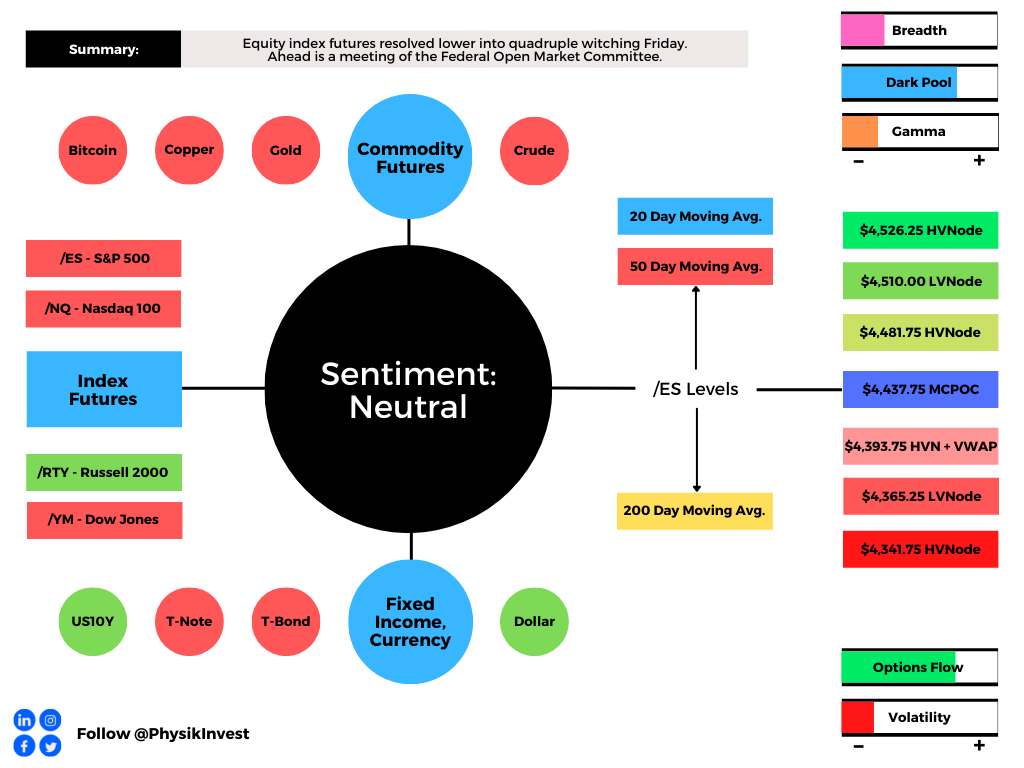
A fast lane for the ECB to taper purchases ahead of Fed.

OPEC+ faces mixed market signals after U.S. pressures.

Capital raises from infotech sector simmering down July.

Fitch Ratings unpacks commodities and energy research.

Battery storage capacity likely to double inside California.

Moderna creates twice as many antibodies as Pfizer vax.

What People Are Saying

About

After years of self-education, strategy development, and trial-and-error, Renato Leonard Capelj began trading full-time and founded Physik Invest to detail his methods, research, and performance in the markets. 

Additionally, Capelj is a finance and technology reporter. Some of his biggest works include interviews with leaders such as John Chambers, founder and CEO, JC2 Ventures, Kevin O’Leary, businessman and Shark Tank host, Catherine Wood, CEO and CIO, ARK Invest, among others.

Disclaimer

At this time, Physik Invest does not manage outside capital and is not licensed. In no way should the materials herein be construed as advice. Derivatives carry a substantial risk of loss. All content is for informational purposes only.